India Macro Daily(Beta Mode)
Flash PMIs Lift Equities, Rupee Firms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
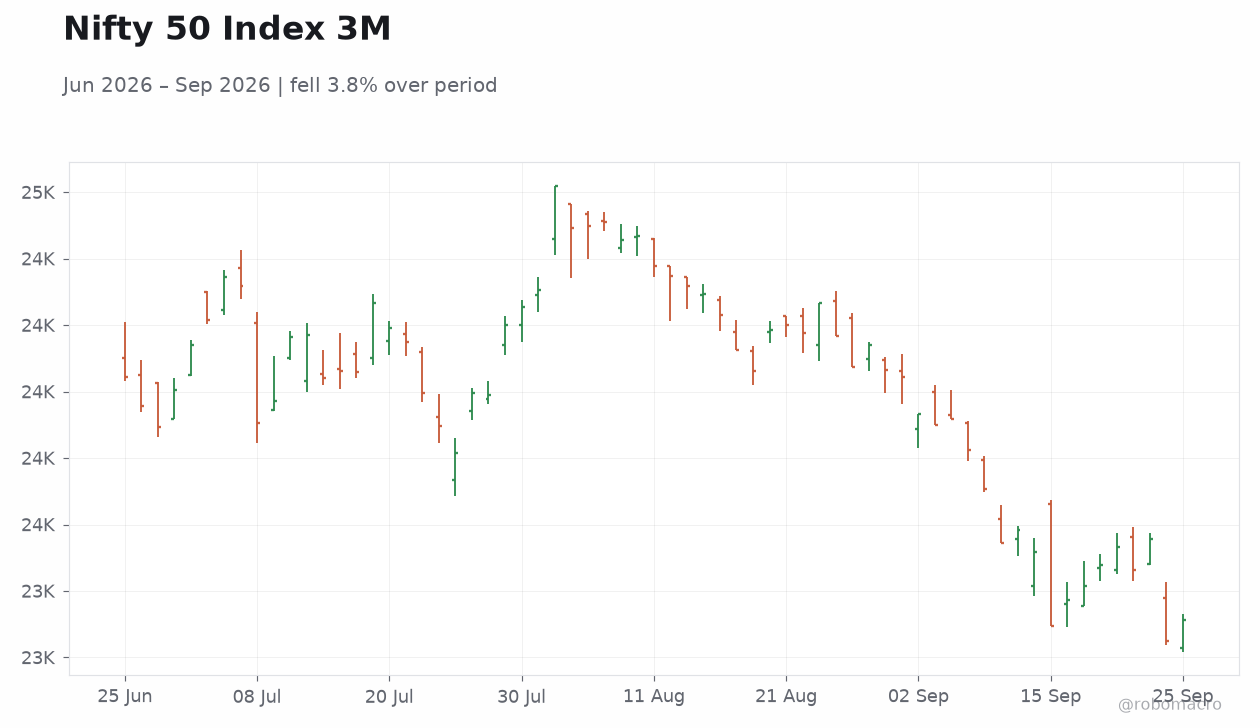
| Nifty 50 | 23,140.50 | +0.34% |
| Sensex | 73,895.74 | +0.43% |
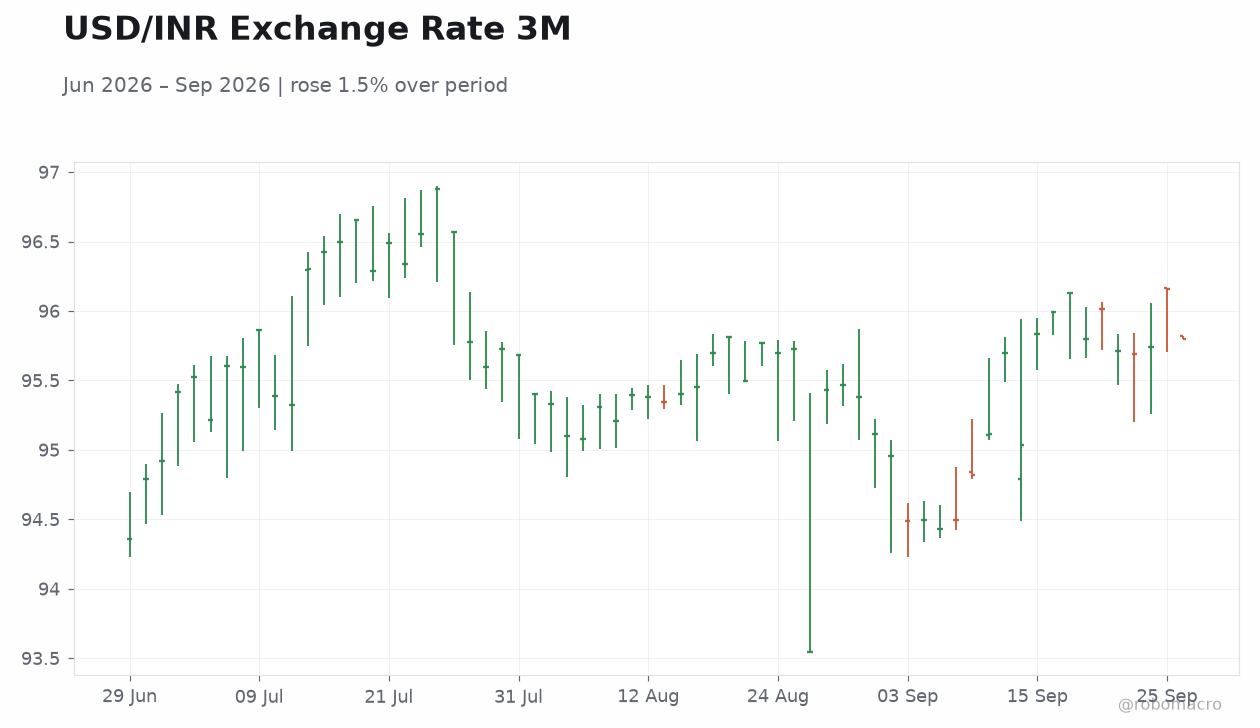
| USD/INR | 95.80 | -0.37% |
| EUR/INR | 109.05 | -0.03% |
| Reliance | 1,226.00 | +0.56% |
| HDFC Bank | 735.60 | +0.92% |
| Brent Crude | 98.44 | -5.64% |
| Gold | 4,289.50 | -0.73% |
| Bitcoin | 84,744.39 | +0.40% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| HSBC Composite PMI Flash | 54.30 | - | 56.50 |
| HSBC Manufacturing PMI Flash | 52.80 | - | 55.70 |
| HSBC Services PMI Flash | 54.10 | - | 55.80 |
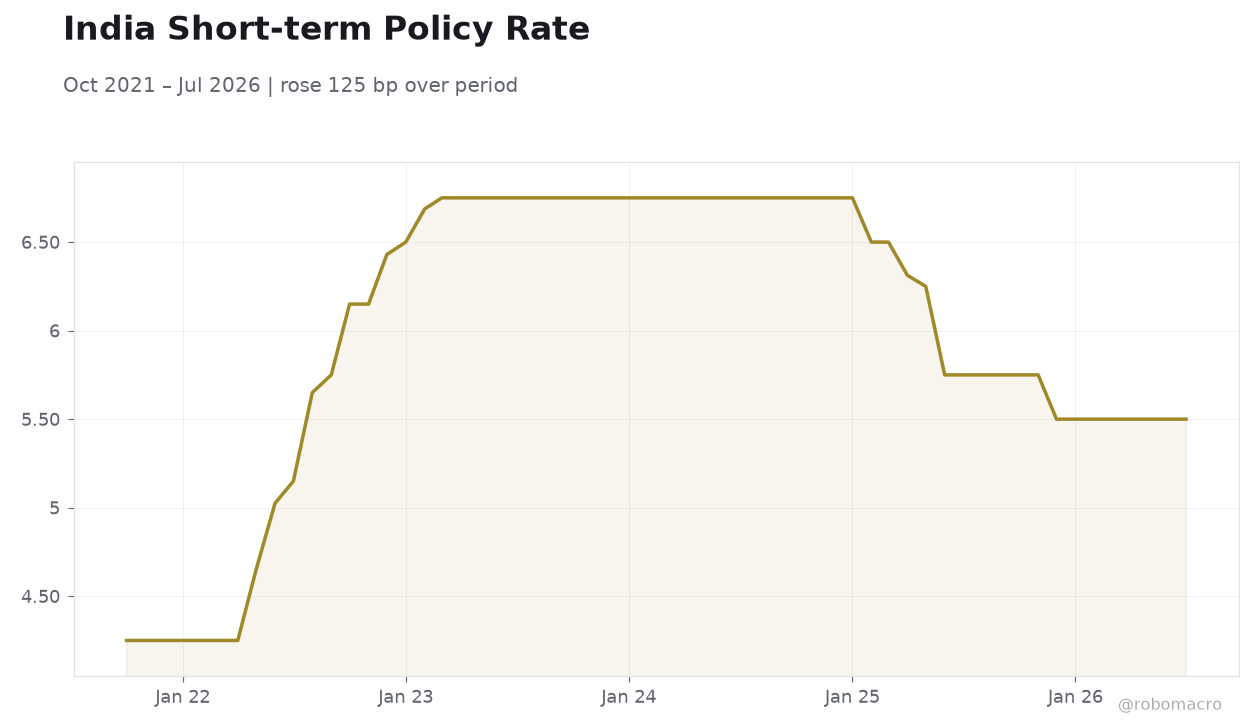 India Short-term Policy Rate | Type: macro_line | %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- HSBC Flash PMIs rose sharply across manufacturing, services and composite readings
- Nifty and Sensex closed higher while USD/INR eased on likely RBI support
- RBI bulletin highlighted resilient growth and external sector strength despite global risks
Yesterday's Recap
HSBC Flash PMI data released on 22 September showed clear acceleration in activity. Composite PMI climbed to 56.5 from 54.3, manufacturing PMI jumped to 55.7 from 52.8, and services PMI advanced to 55.8 from 54.1. Equity benchmarks responded positively, with Nifty 50 rising 0.34 percent to 23,140.50 and Sensex gaining 0.43 percent to 73,895.74.
Reliance Industries added 0.56 percent while HDFC Bank rose 0.92 percent. The rupee strengthened 0.37 percent to 95.80 against the dollar, supported by reported RBI intervention. Forex reserves declined $14.89 billion to $766 billion according to the latest RBI data.
Brent crude fell 5.64 percent to 98.44 while gold slipped 0.73 percent.
The Day Ahead
No scheduled economic releases or RBI events appear on the calendar for 27 or 28 September. Markets will therefore focus on external cues including US-Iran developments and movements in global bond yields. Traders are expected to monitor USD/INR closely after Friday’s intervention-driven gain.
Equity sentiment may draw support from the upbeat PMI prints and the RBI bulletin’s positive tone on domestic demand. Private-sector capex plans estimated at Rs 3.2 lakh crore for 2026-27 could also feature in investor discussions.
Other Economic Notes
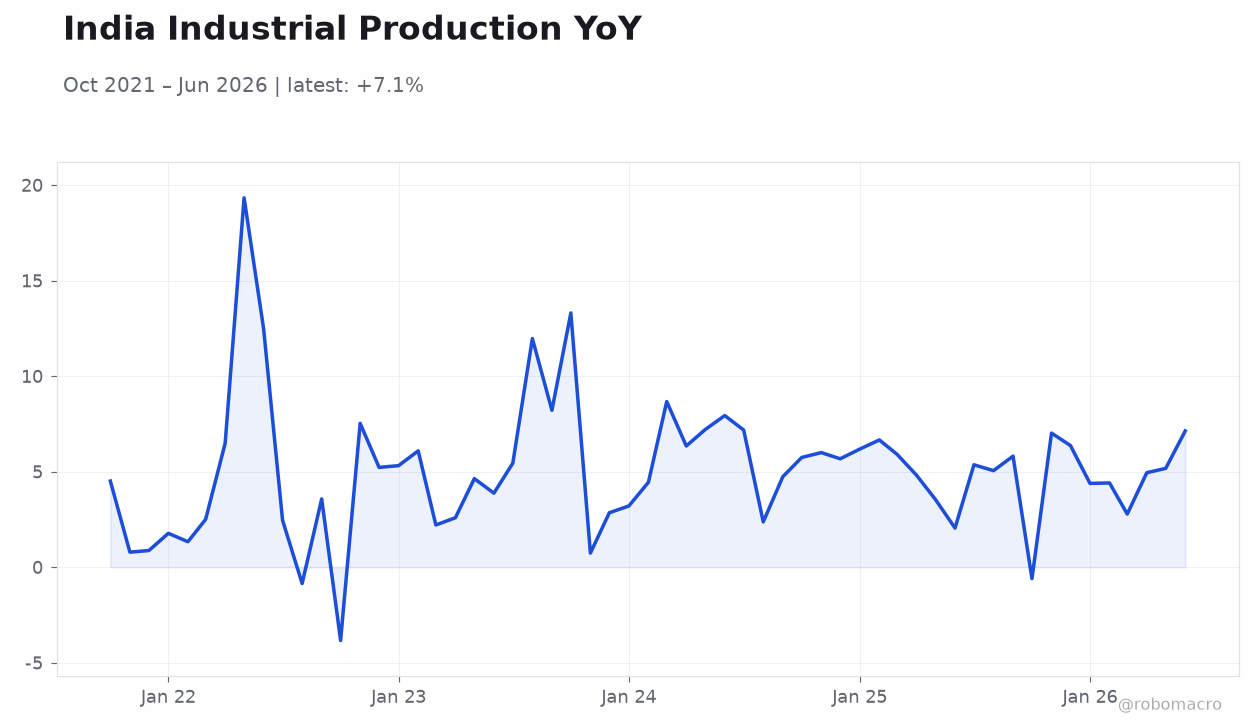
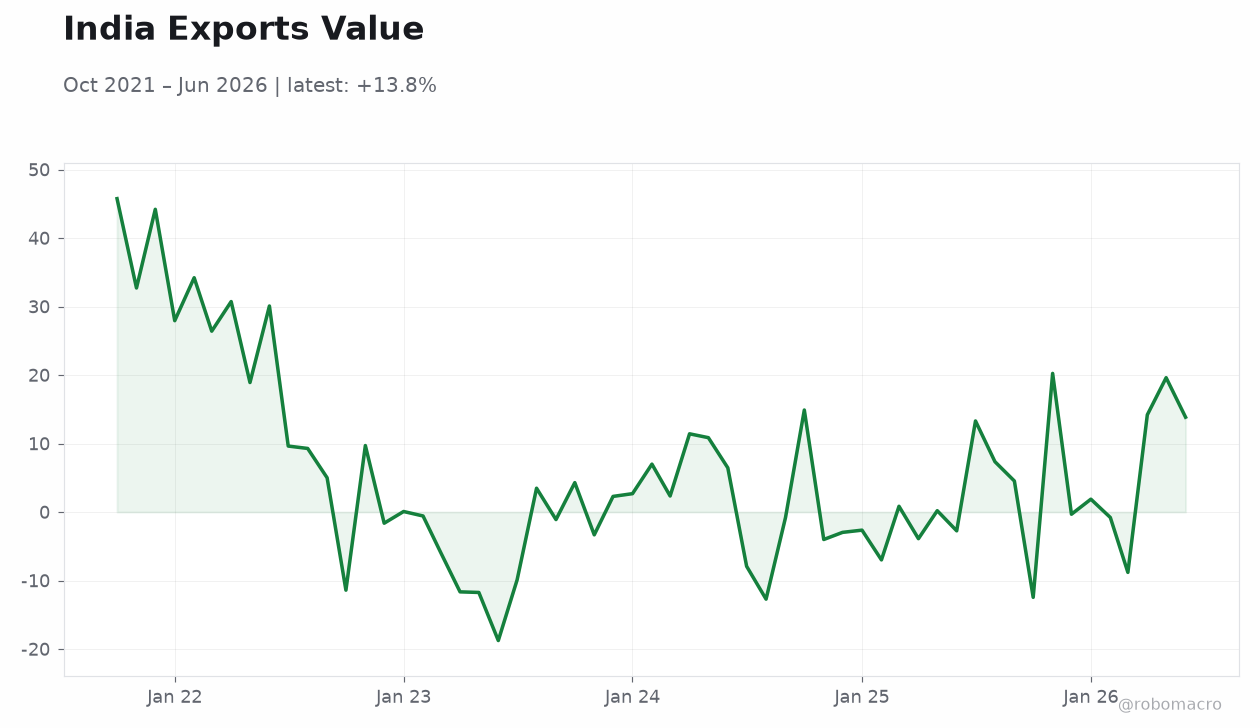
The RBI bulletin stressed that India’s financial and external sectors remain resilient amid global headwinds, citing strong Q1 FY27 growth, record net FDI inflows, and robust services exports. RBI Deputy Governor Poonam Gupta noted that the bond market has performed well and equities could regain attractiveness. Private capex projections of Rs 3.2 lakh crore for the current fiscal year point to sustained investment momentum.
Reports of job reductions at global capability centres contrast with India’s expanding role in higher-value mandates. Heavy rainfall in Uttar Pradesh caused significant local damage but is unlikely to alter national growth trajectories.