India Macro Daily(Beta Mode)
Robust IP Data Fuels RBI Hike Bets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 23,140.50 | +0.34% |
| Sensex | 73,895.74 | +0.43% |
| USD/INR | 95.97 | +0.19% |
| EUR/INR | 109.11 | +3.06% |
| Reliance | 1,226.00 | +0.56% |
| HDFC Bank | 735.60 | +0.92% |
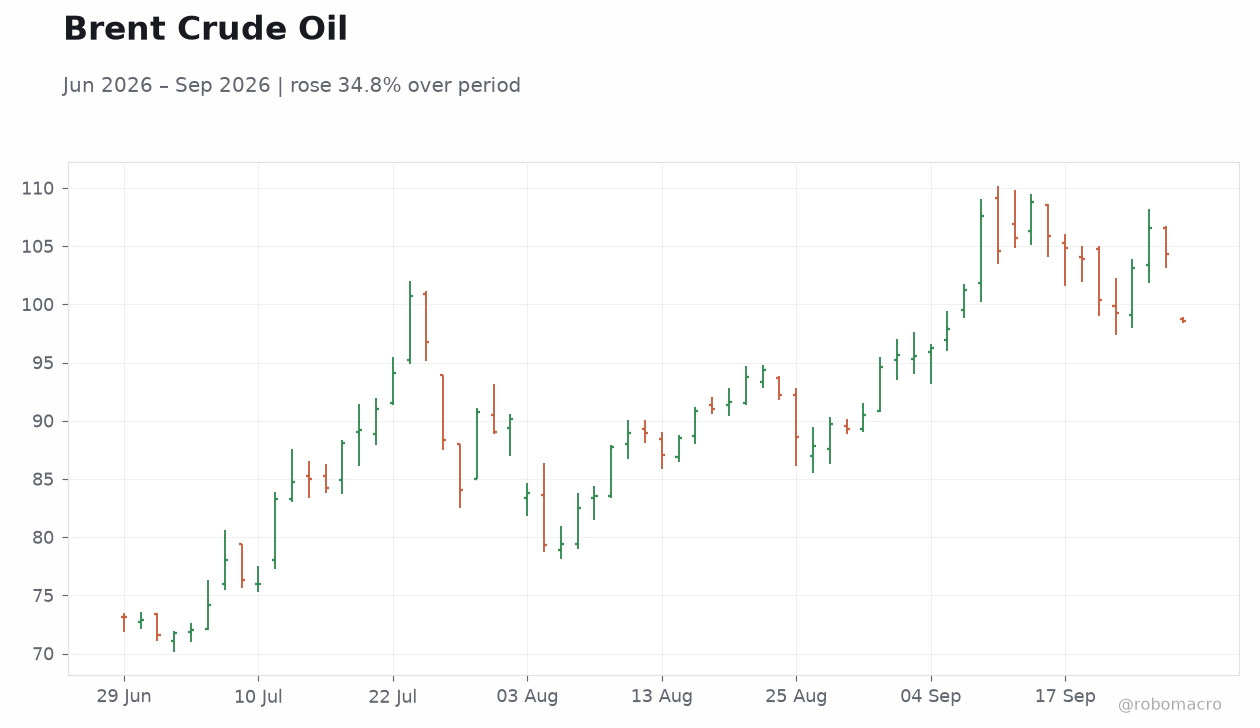
| Brent Crude | 98.82 | -5.27% |
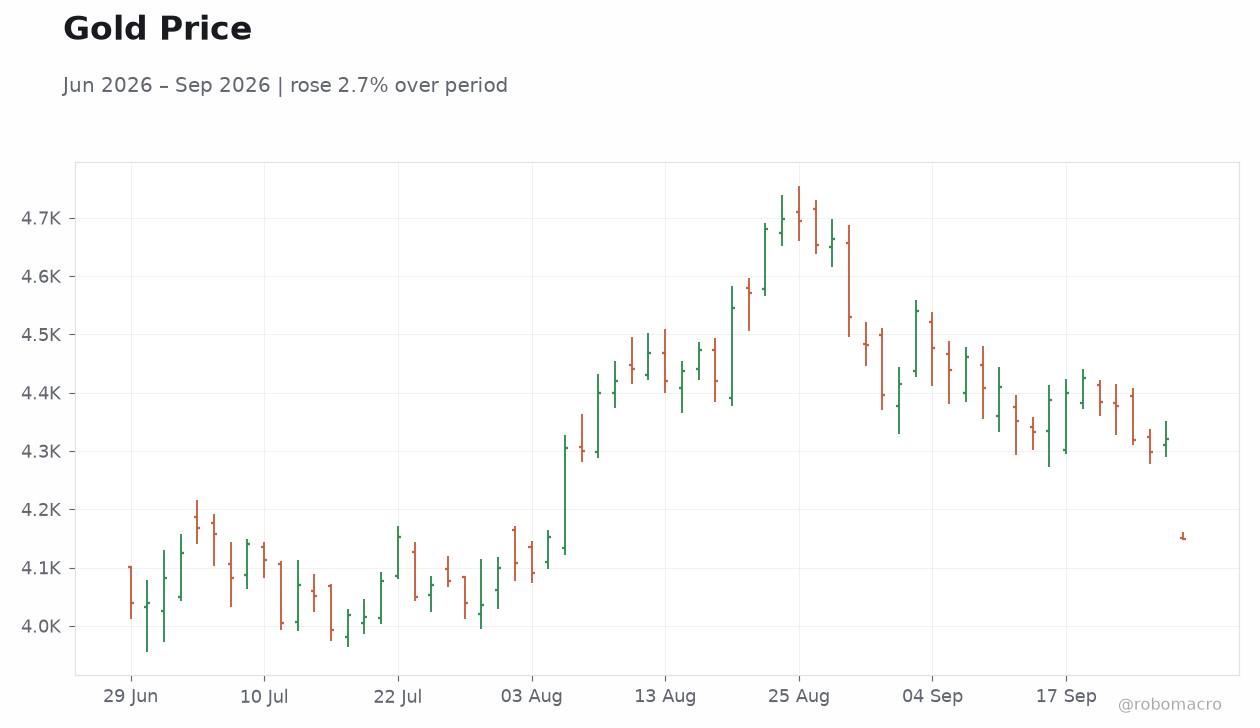
| Gold | 4,149.10 | -3.98% |
| Bitcoin | 83,501.91 | -1.13% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
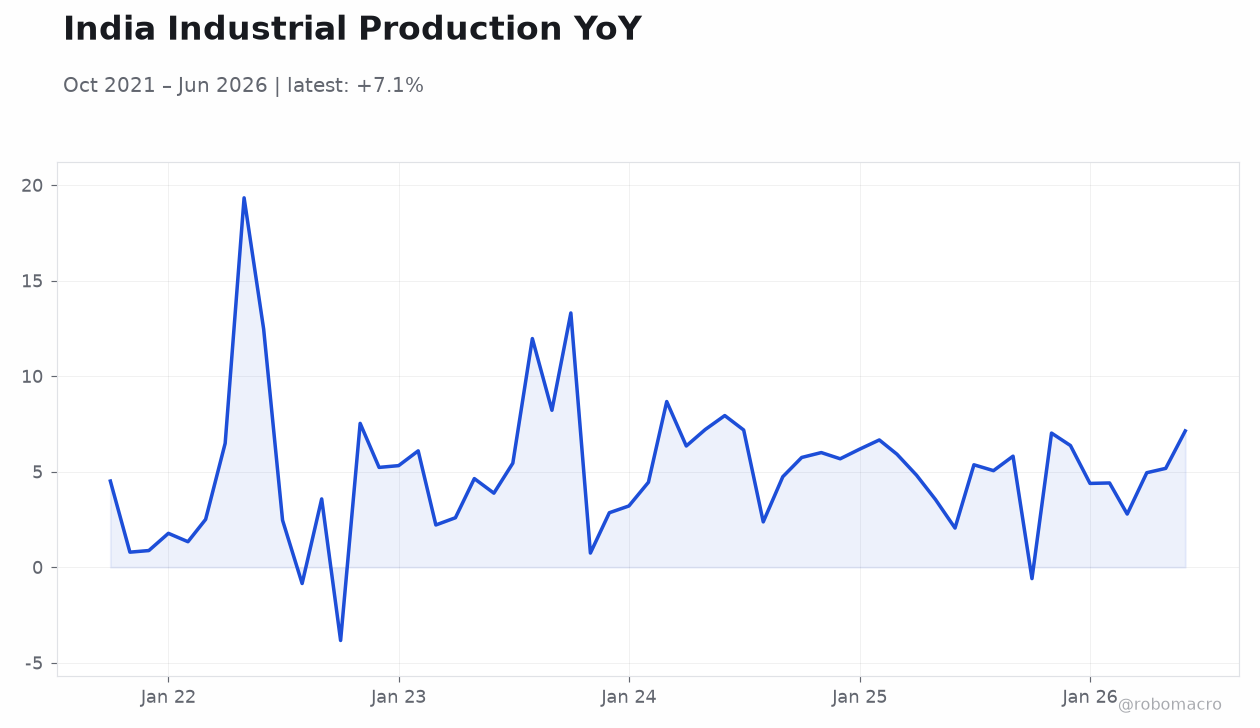
| Industrial Production Year-over-Year | 6.70 | 6.50 | 8 |
| Manufacturing Production Year-over-Year | 7.30 | - | 9 |
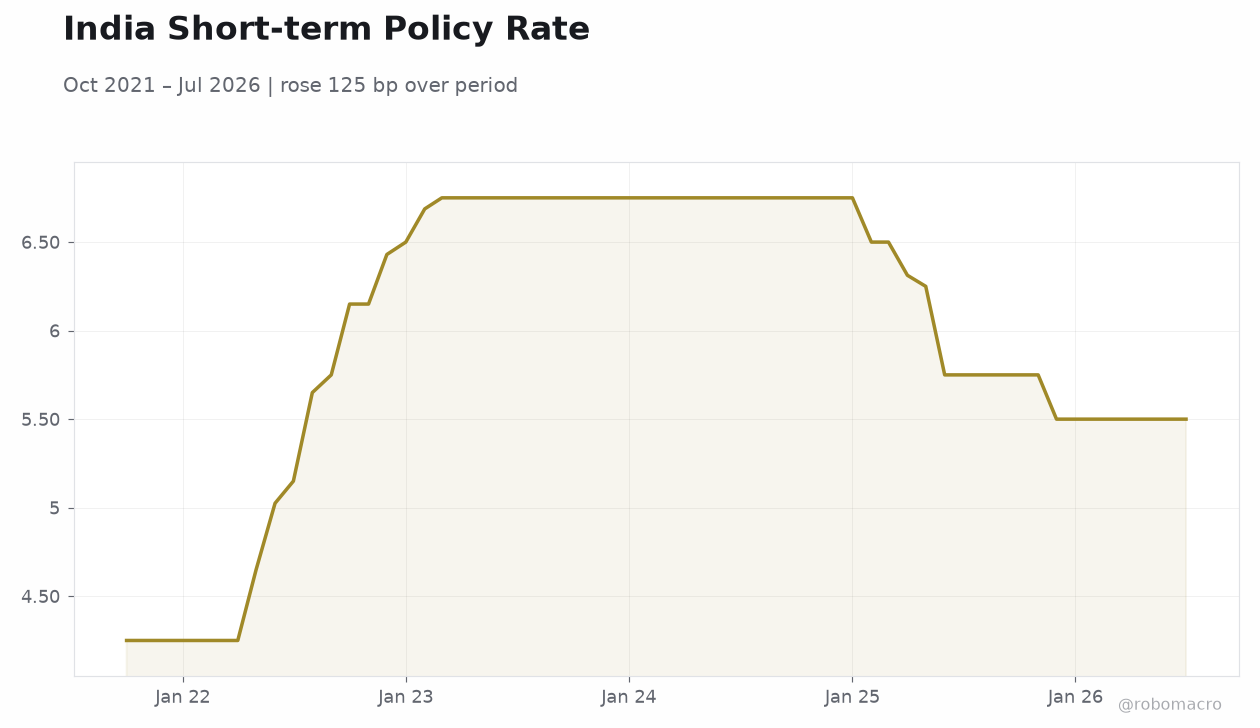 India Short-term Policy Rate | Type: macro_line | Percent: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.43,6.75,6.312,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Industrial production rose 8.0% YoY, beating consensus and signaling stronger momentum.
- Nifty 50 and Sensex posted modest gains while USD/INR edged higher to 95.97.
- RBI bulletin underscored domestic resilience amid global headwinds and corporate debt issuance plans.
Yesterday's Recap
Industrial Production YoY printed 8.0% against a 6.5% consensus and 6.7% prior reading, while Manufacturing Production YoY climbed to 9.0% from 7.3%. Both releases exceeded expectations and reinforced evidence of solid underlying activity. Nifty 50 advanced 0.34% to 23,140.50 and Sensex rose 0.43% to 73,895.74, led by gains in Reliance and HDFC Bank.
USD/INR climbed 0.19% to 95.97 as oil prices and Iran-related concerns weighed on sentiment, though RBI intervention provided a buffer. Brent Crude fell 5.27% to 98.82 and gold dropped 3.98% to 4,149.10. News flow highlighted Indian firms preparing roughly $3 billion in debt issues in anticipation of a possible RBI rate increase.
The RBI bulletin stressed that the economy continued to perform well despite global pressures, with financial and external sectors drawing strength from resilient domestic demand.
The Day Ahead
No major economic releases are scheduled for today. Markets will monitor any follow-through from yesterday’s strong industrial data and ongoing rupee pressure. Corporate debt issuance plans tied to rate-hike expectations may influence sentiment in credit markets.
Traders will also watch for signs of RBI intervention in the foreign-exchange market given the rupee’s proximity to 96. Broader global developments, including oil-price movements and Iran talks, remain key external variables. Equity investors will focus on sector rotation after yesterday’s modest gains in banking and energy names.
Other Economic Notes
Indian companies are positioning for higher borrowing costs by lining up $3 billion in debt issues ahead of potential monetary tightening. The RBI bulletin highlighted continued strength in the financial and external sectors supported by domestic resilience. Fresh anti-dumping duties of up to $445 per tonne on Bangladesh jute goods underscore India’s efforts to protect local industry amid shifting trade dynamics.
Heavy rainfall in Uttar Pradesh damaged more than 1,000 houses, adding localized pressure on rural consumption. These developments occur against a backdrop of CPI at 4.44% and the RBI repo rate at 5.25%, keeping inflation and policy calibration in focus.