India Macro Daily(Beta Mode)
IP Surge Fuels Hawkish RBI Outlook
Market Snapshot
| Asset | Level | Change |
|---|---|---|
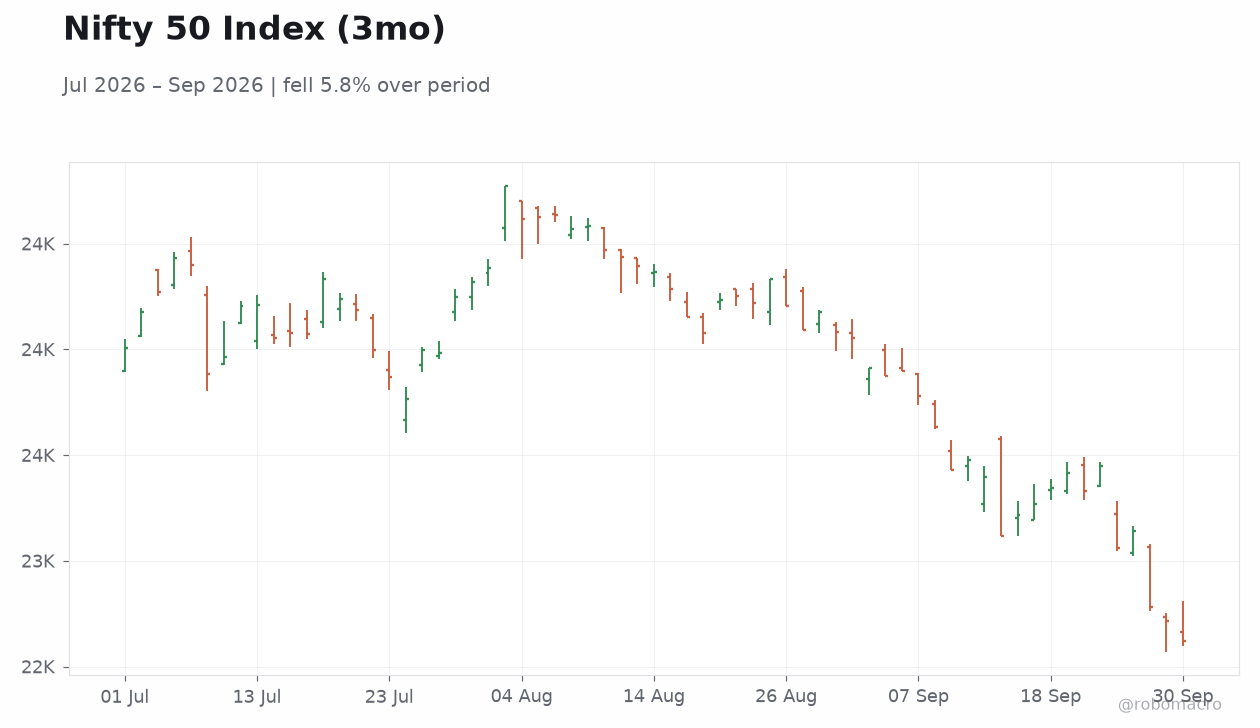
| Nifty 50 | 22,620.45 | -0.42% |
| Sensex | 72,480.29 | -0.07% |
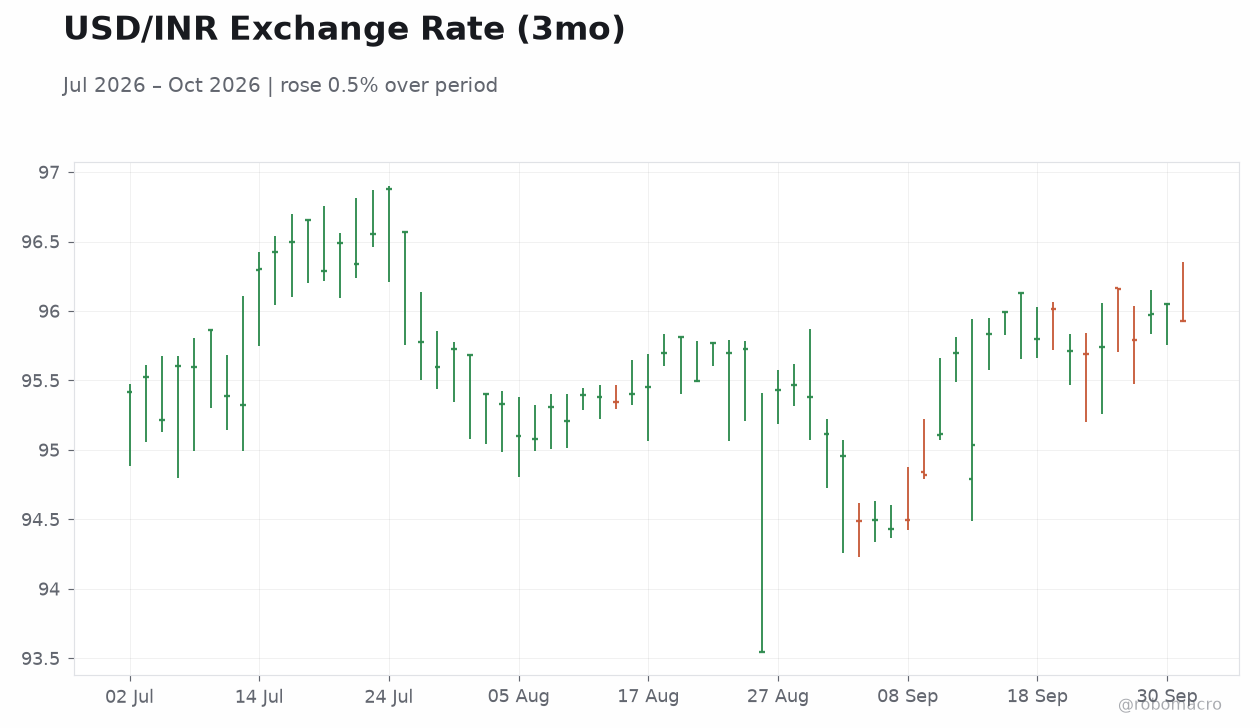
| USD/INR | 95.93 | -0.13% |
| EUR/INR | 108.64 | -0.12% |
| Reliance | 1,167.70 | -1.63% |
| HDFC Bank | 721.20 | +1.76% |
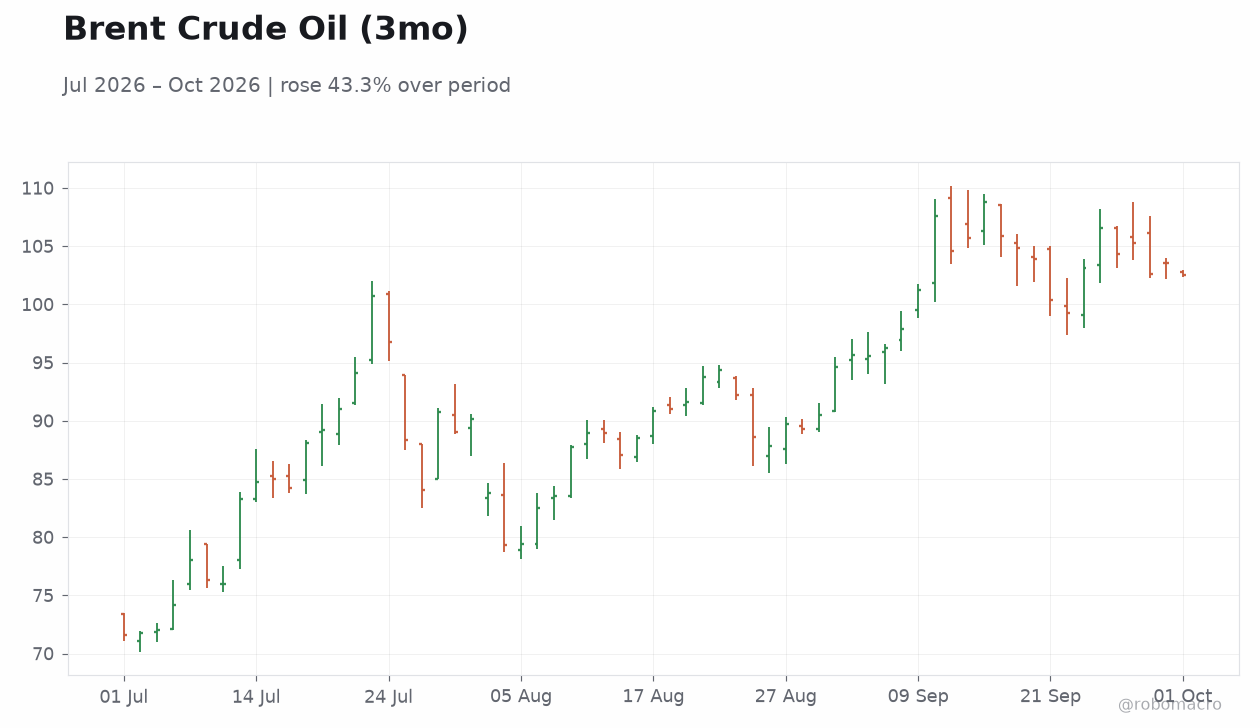
| Brent Crude | 102.63 | -0.87% |
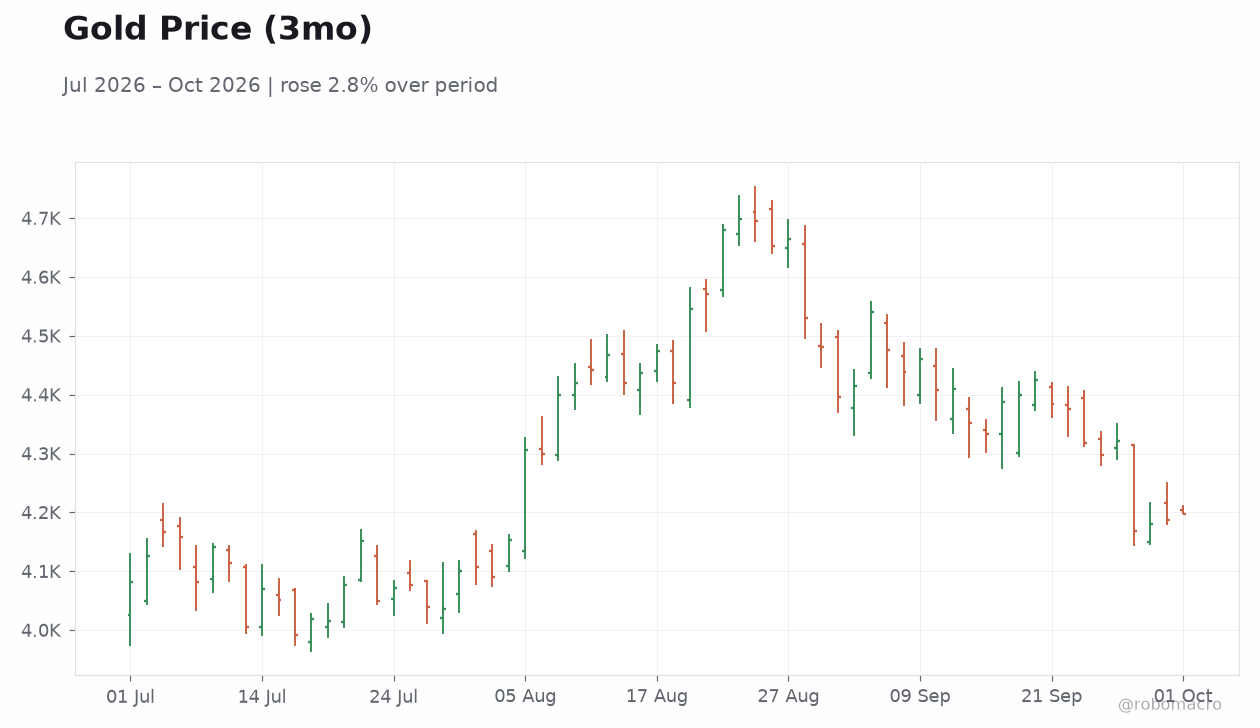
| Gold | 4,199.10 | +0.30% |
| Bitcoin | 84,761.77 | +1.45% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Year-over-Year | 6.70 | 6.50 | 8 |
| Manufacturing Production Year-over-Year | 7.30 | - | 9 |
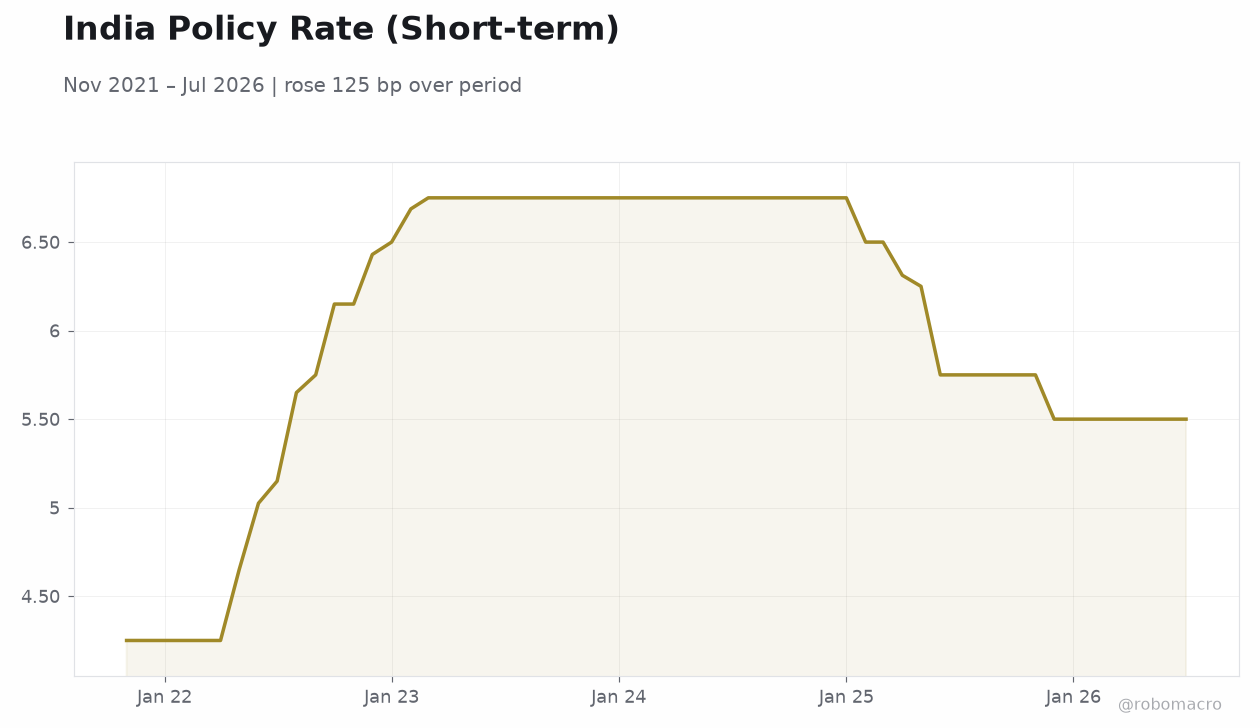 India Policy Rate (Short-term) | Type: macro_line | %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Industrial production jumped to 8% YoY, outpacing consensus and reinforcing industrial momentum.
- Rupee held near 96/USD as RBI intervention offset outflows amid narrow trading ranges.
- $133 billion liquidity surge and inflation pressures keep RBI on a hawkish policy path.
Yesterday's Recap
Indian equities closed modestly lower on 30 September. Nifty 50 fell 0.42% to 22,620.45 while Sensex declined 0.07% to 72,480.29. Reliance Industries dropped 1.63% to 1,167.70, whereas HDFC Bank gained 1.76% to 721.20.
The rupee strengthened slightly, with USD/INR closing at 95.93. Brent crude slipped 0.87% to 102.63 and gold rose 0.30% to 4,199.10. Industrial production rose 8.0% YoY against a 6.5% consensus and 6.7% prior reading.
Manufacturing production accelerated to 9.0% YoY from 7.3% previously, both releases dated 28 September and pointing to firmer factory activity. External debt reached $778.2 billion in the June quarter, underscoring financing needs amid global uncertainty.
The Day Ahead
No major economic releases are scheduled for 1 October. Markets will monitor rupee flows and any follow-through from the strong industrial data. Traders expect continued RBI intervention to cushion the currency near the 96/USD level.
Equity sentiment may draw cues from global risk appetite and US Treasury yield movements. Attention will also focus on liquidity conditions following the recent cash deluge. Private capex and credit growth trends remain in focus after Kotak flagged limited recovery.
Apple’s rollout of its payment service adds competitive pressure in digital finance, while trade-remedy actions on PET film imports highlight ongoing external-sector vigilance.
Other Economic Notes
India’s external debt climbed to $778.2 billion in the June quarter, highlighting external financing needs. Apple launched its payment service in India, intensifying competition in digital payments. The trade remedies authority recommended anti-dumping duties of up to $218 per tonne on PET film imports.
Reports noted an inflation shock alongside the $133 billion liquidity overhang that together sustain hawkish RBI expectations. Kotak highlighted subdued private investment and credit expansion, tempering optimism on the growth outlook. These developments coincide with the rupee’s narrow trading band and repeated central-bank support near 96/USD.