India Macro Daily(Beta Mode)
IP Surges to 8% as Forex Reserves Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
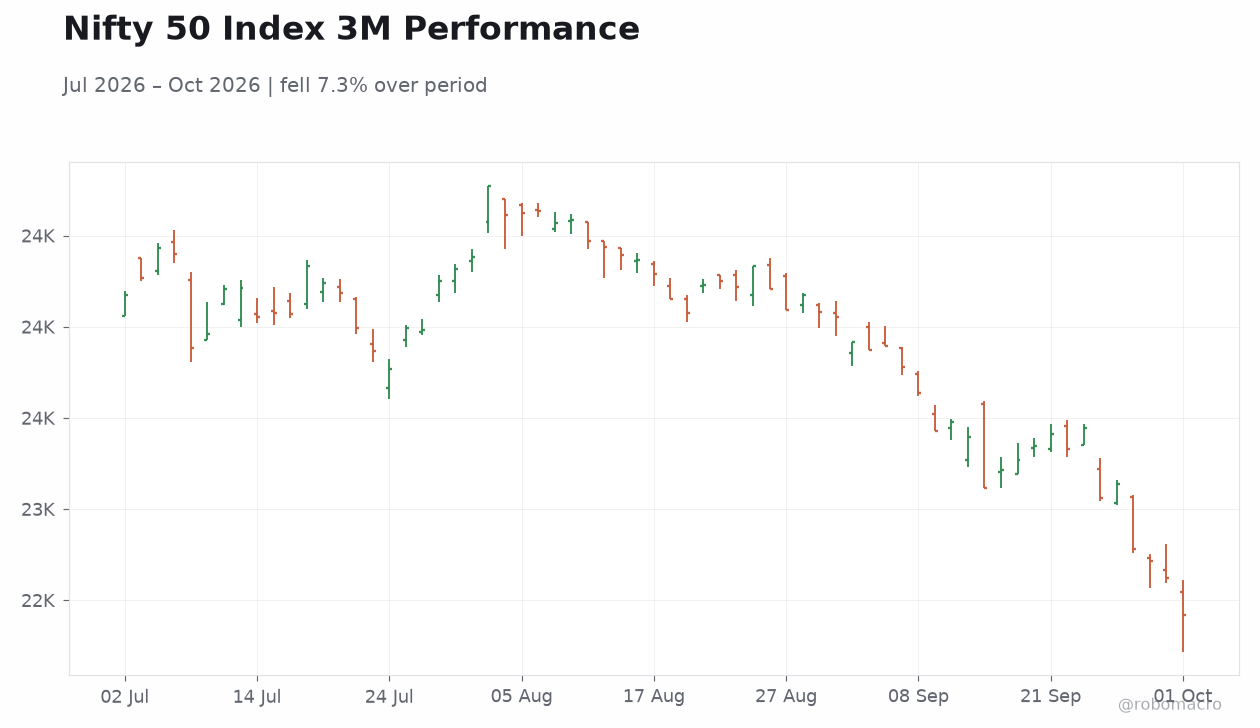
| Nifty 50 | 22,421.95 | -0.88% |
| Sensex | 71,909.70 | -0.79% |
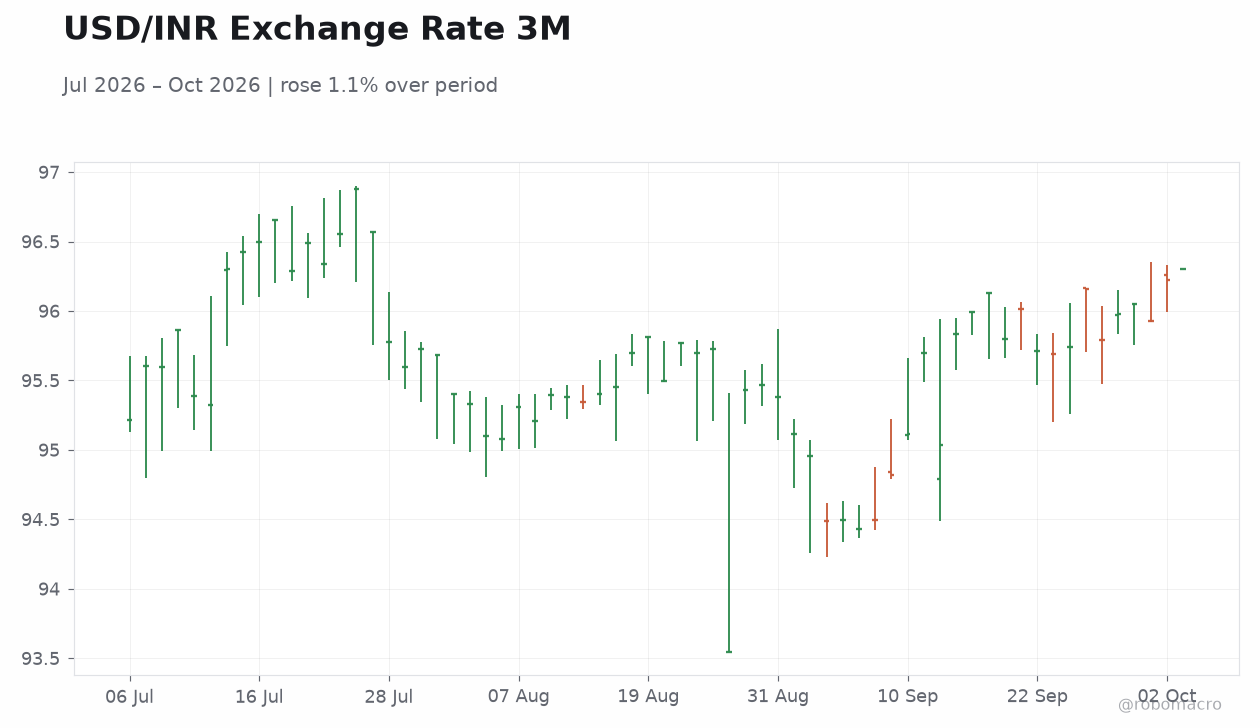
| USD/INR | 96.30 | +0.08% |
| EUR/INR | 108.40 | +0.13% |
| Reliance | 1,167.70 | -1.63% |
| HDFC Bank | 721.20 | +1.76% |
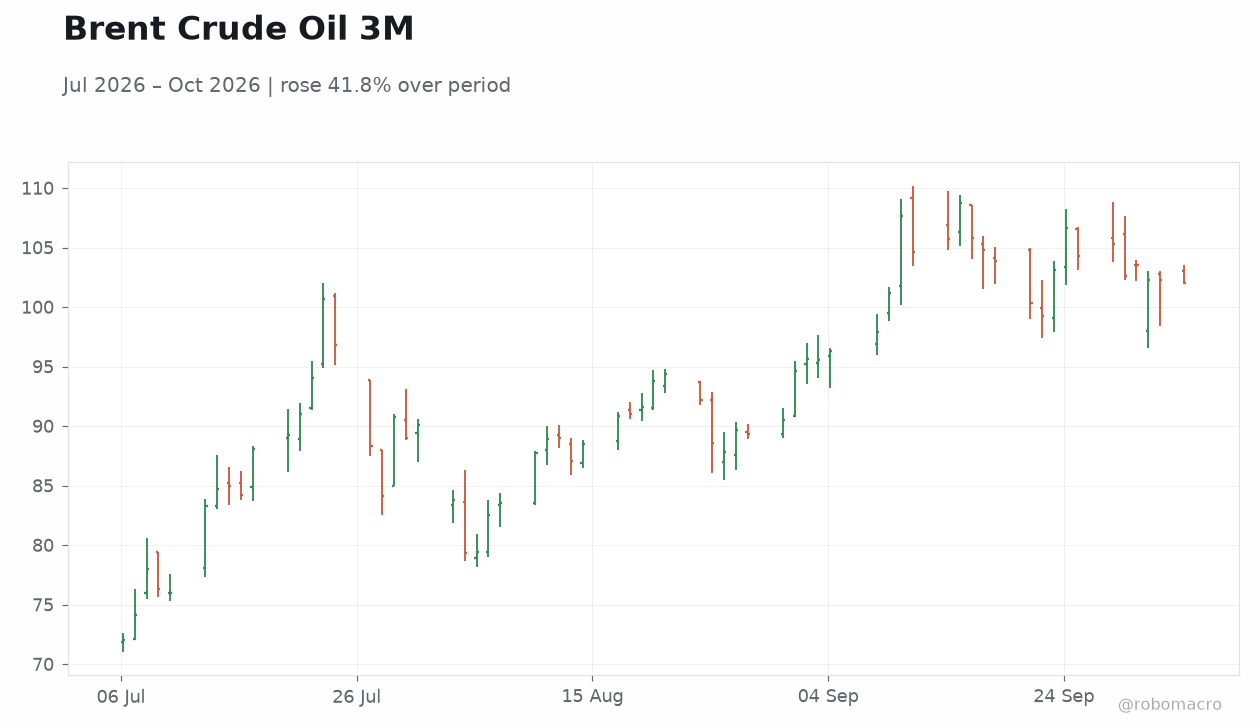
| Brent Crude | 102.14 | -0.11% |
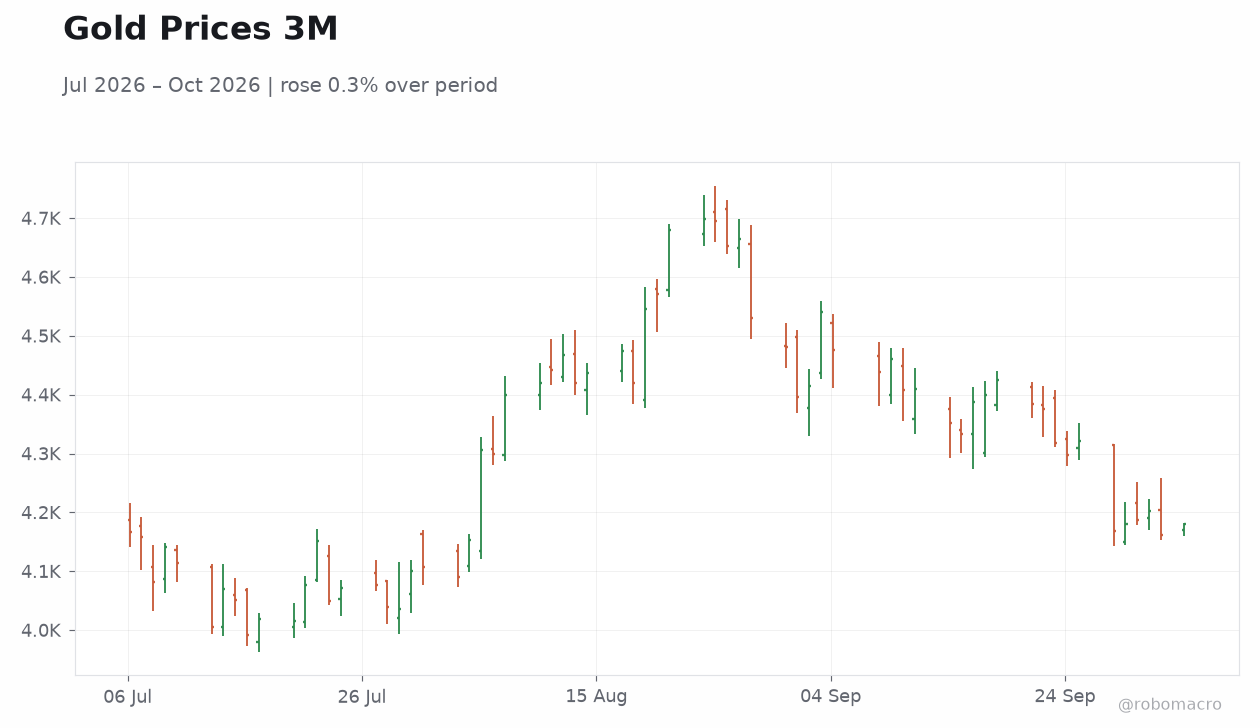
| Gold | 4,179.90 | +0.42% |
| Bitcoin | 86,261.64 | +1.77% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Year-over-Year | 6.70 | 6.50 | 8 |
| Manufacturing Production Year-over-Year | 7.30 | - | 9 |
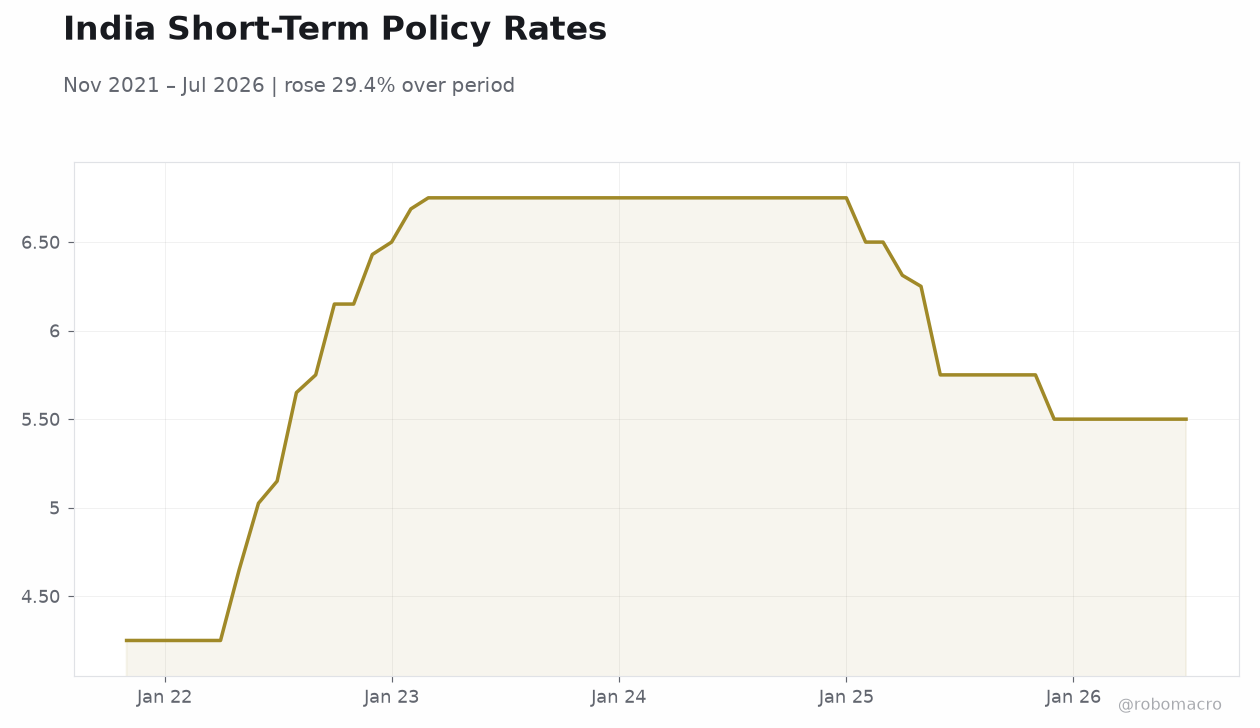 India Short-Term Policy Rates | Type: macro_line | Rate %: 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Industrial production rose 8.0% YoY, well above the 6.5% consensus.
- Nifty 50 fell 0.88% and the rupee edged 0.08% weaker to 96.30.
- Forex reserves dropped $18.34 billion to $747.56 billion after RBI intervention.
Yesterday's Recap
Industrial production printed 8.0% year-over-year in the latest release, exceeding the 6.5% consensus and prior 6.7% reading. Manufacturing output accelerated to 9.0% from 7.3% previously, confirming firmer factory momentum. Equity markets closed lower, with the Nifty 50 declining 0.88% to 22,421.95 and the Sensex slipping 0.79% to 71,909.70.
Reliance Industries fell 1.63% while HDFC Bank gained 1.76%. The rupee weakened modestly, with USD/INR rising 0.08% to 96.30 and EUR/INR advancing 0.13% to 108.40. Brent crude eased 0.11% to $102.14 and gold rose 0.42% to $4,179.90.
Forex reserves fell sharply by $18.34 billion to $747.56 billion in the week ended 25 September as the central bank stepped in to support the currency.
The Day Ahead
No major Indian data releases are scheduled for 4 October. Markets will monitor ongoing India-US trade discussions described as being in the short strokes yet without an imminent announcement. Traders will also track global oil prices and any fresh FPI flow data that could influence rupee sentiment.
RBI communications on liquidity management and the real-rate channel remain in focus ahead of the next policy meeting. Equity investors will watch IT services names for any updates on global demand. Broader attention may turn to domestic political developments that could affect policy continuity.
Other Economic Notes
Nilesh Shah highlighted that India retains capacity to sustain around 7% growth even amid global uncertainties. The sharp decline in forex reserves underscores the RBI’s active defense of the rupee amid external pressures. Indian banks recorded roughly $500 million in FX trading losses following the central bank’s imposition of position caps.
Protests over alleged voter-roll deletions continue but have not yet altered economic policy expectations. An India-US trade agreement remains possible in the near term though timing stays uncertain.