India Macro Daily(Beta Mode)
"RBI Hikes 25bp, First Since 2023"
Market Snapshot
| Asset | Level | Change |
|---|---|---|
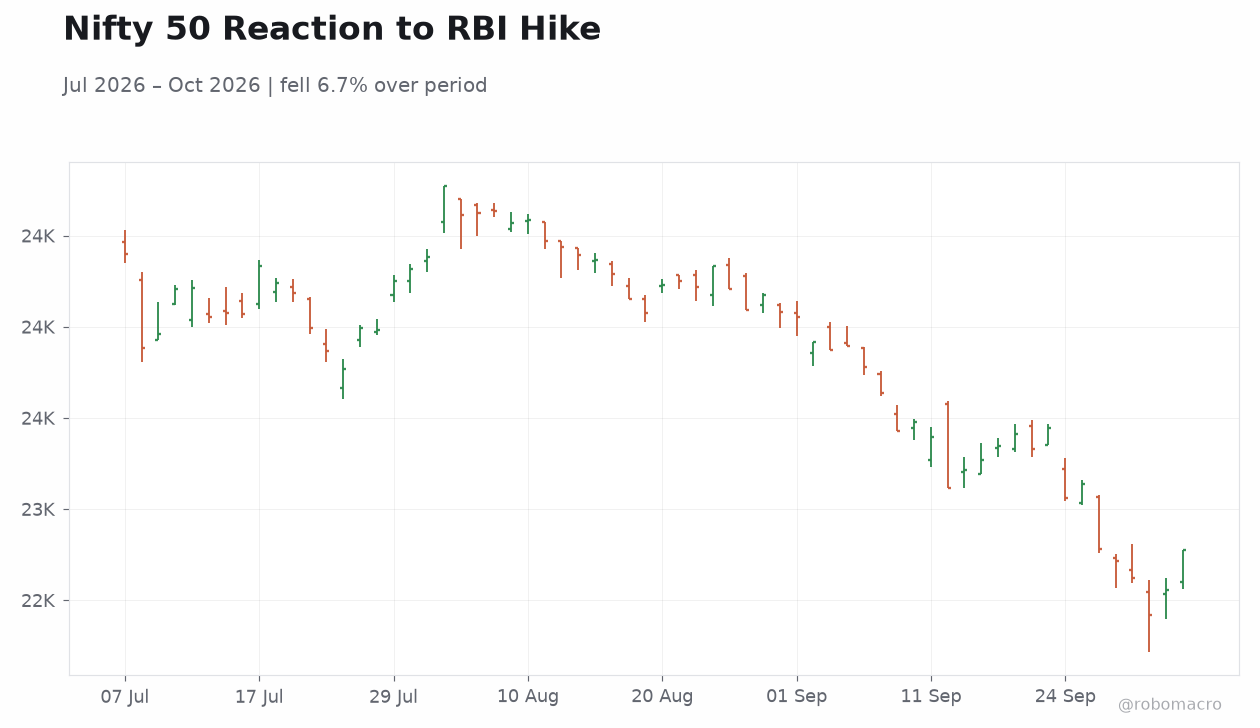
| Nifty 50 | 22,776.10 | +0.98% |
| Sensex | 73,067.81 | +0.95% |
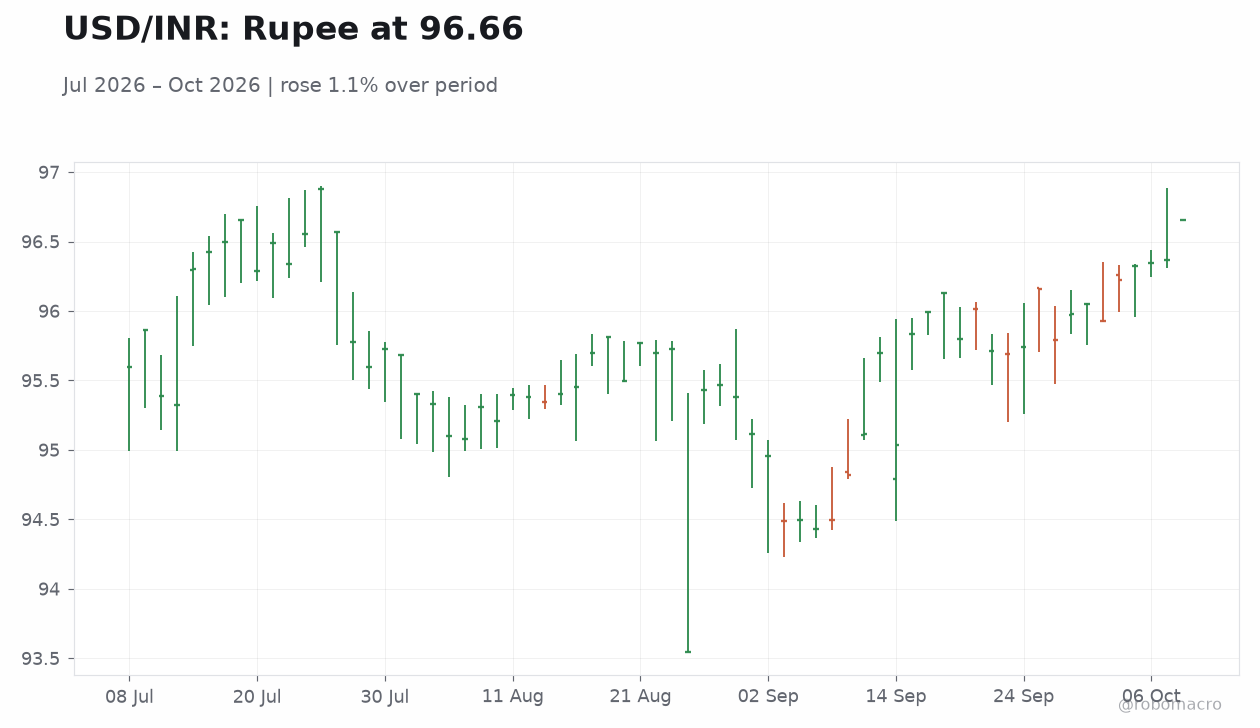
| USD/INR | 96.66 | +0.30% |
| EUR/INR | 108.27 | -0.12% |
| Reliance | 1,207.70 | -0.85% |
| HDFC Bank | 702.75 | -1.22% |
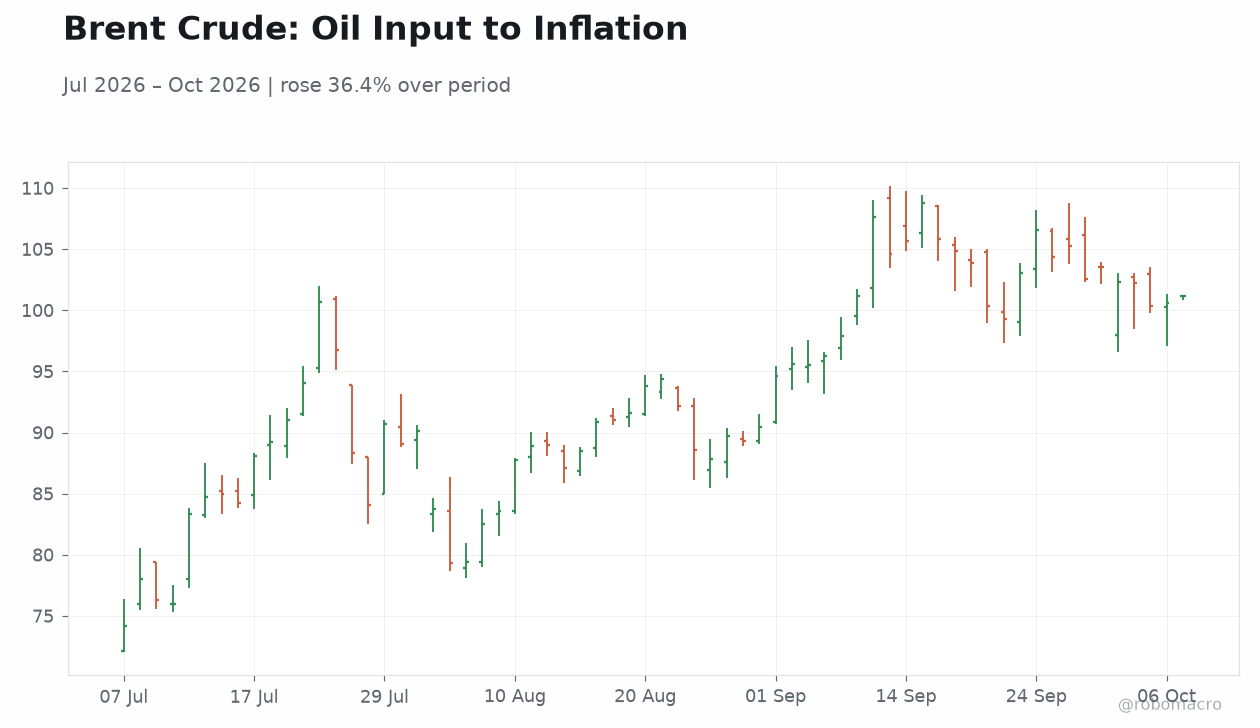
| Brent Crude | 101.16 | +0.58% |
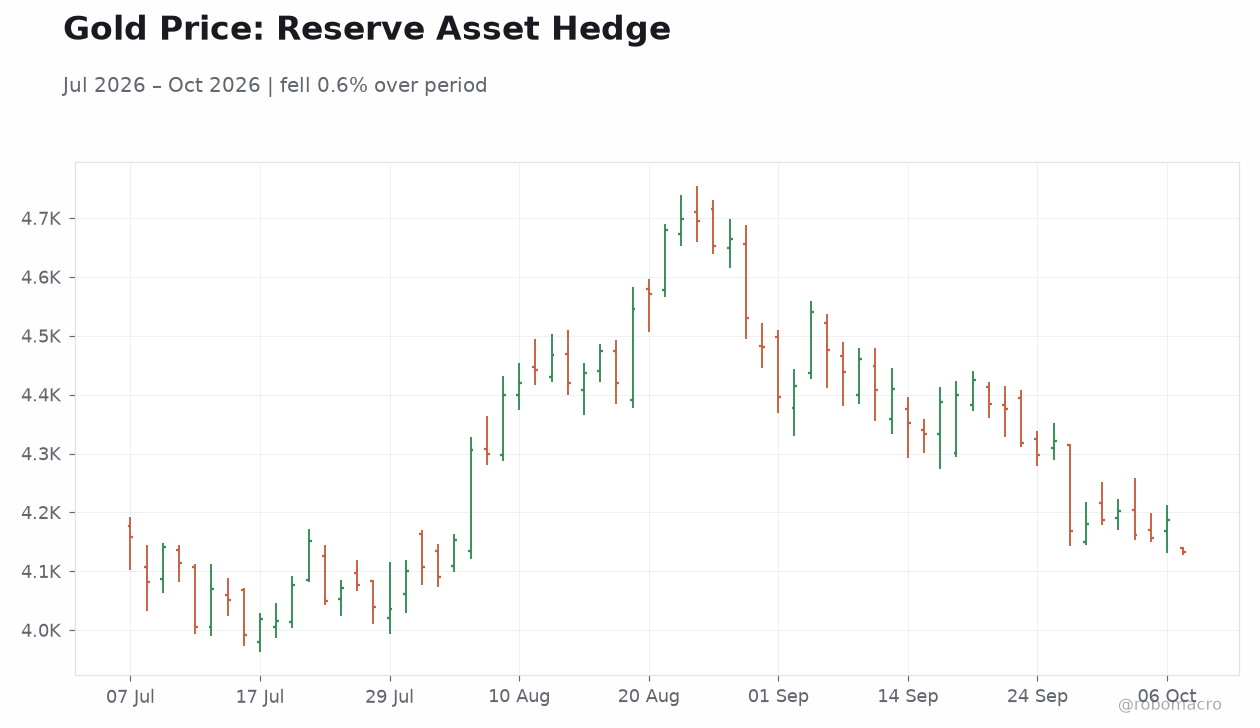
| Gold | 4,133.90 | -1.27% |
| Bitcoin | 83,215.26 | -2.74% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| RBI Interest Rate Decision | 5.25 | 5.50 | 5.50 |
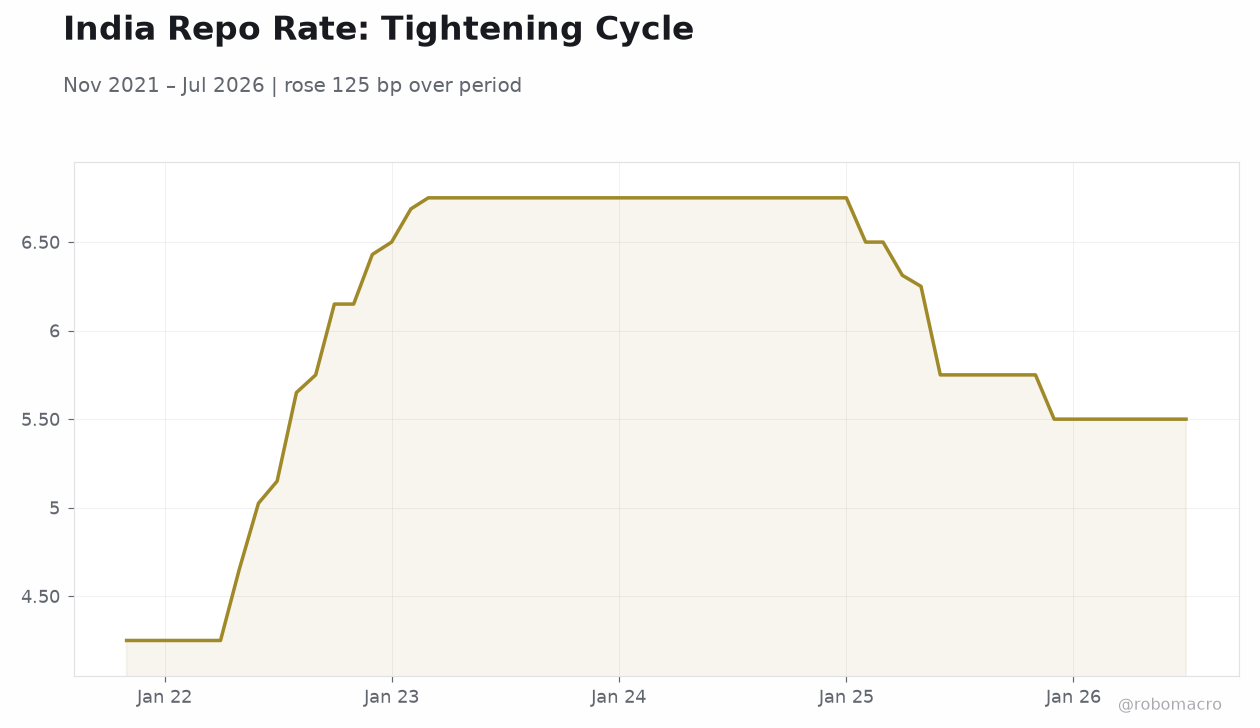 India Repo Rate: Tightening Cycle | Type: macro_line | Short-term / policy rate (%): 5.5 (2026-07-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- RBI raised the repo rate 25bp to 5.50%, its first hike since 2023, signaling a calibrated tightening cycle with more increases possible
- Nifty 50 rose 0.98% to 22,776 while the rupee slipped to 96.66 as the rate decision landed
- September services PMI at 55.2 confirmed demand resilience, giving the MPC cover to prioritize inflation control
Yesterday's Recap
The Reserve Bank of India delivered its first rate increase in over three years, lifting the repo rate 25bp to 5.50% from 5.25%, in line with consensus. The move marks a clear pivot from the easing bias of recent years, with the MPC citing persistent inflation pressures. Equities initially wobbled but recovered sharply intraday — the Sensex climbed 450 points off its low before settling near 22,600 territory, with the Nifty 50 closing at 22,776.10, up 0.98%, and the Sensex at 73,067.81, up 0.95%.
The rupee fell 22 paise to 96.57 against the dollar immediately after the announcement, and USD/INR finished at 96.66, weaker by 0.30% on the day. Bond traders had positioned for a hawkish outcome and kept yields rangebound into the decision. Banking heavyweights lagged the broader market: HDFC Bank fell 1.22% to 702.75 and Reliance slipped 0.85% to 1,207.70, reflecting rate-sensitivity and post-decision profit-taking.
Brent crude added 0.58% to $101.16, keeping imported-inflation math front of mind for the MPC.
The Day Ahead
The calendar is quiet on official data releases for October 7 and October 8, leaving the market to digest the RBI's policy statement, the Governor's press conference, and any accompanying growth-inflation projections. Expect analysts to parse the MPC's language for clues on the pace of further tightening — the phrase "calibrated tightening" will be tested against incoming CPI prints. Liquidity conditions and money-market rates will be watched as the RBI's operating framework adjusts to the higher repo corridor.
Secondary focus falls on FII flows and the rupee, which must navigate a strong-dollar backdrop alongside domestic rate normalization. Technical levels matter near-term: traders cite 23,000 as the level Nifty bulls need to reclaim, while Bank Nifty faces resistance around 55,200. Any commentary from RBI officials at post-policy forums could move rate-sensitive sectors.
Other Economic Notes
The September services PMI at 55.2 marked a three-month high, underscoring that domestic demand remains robust even as policy tightens — a combination that supports the RBI's ability to hike without crushing growth. ↓ p.2