RoboMacro ResearchAlso todaySee the FX Daily

India Macro Daily(Beta Mode)

October 18, 2026 robomacro.com

Rupee Stabilises as RBI Steps Up; CPI at 5.54%

5.54 Inflation Rate
Nifty 5023,146.15+0.65%
Sensex74,729.27+0.56%
USD/INR94.95+0.45%
EUR/INR106.58+0.06%

Market Snapshot

AssetLevelChange
Nifty 5023,146.15+0.65%
Sensex74,729.27+0.56%
USD/INR94.95+0.45%
EUR/INR106.58+0.06%
Reliance1,211.20-0.31%
HDFC Bank728.85+0.28%
Brent Crude107.94-1.75%
Gold4,200.30+0.46%
Bitcoin82,039.83+0.81%
India 2Y Govt Yield--
India 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
Inflation Rate Year-over-Year4.825.405.54
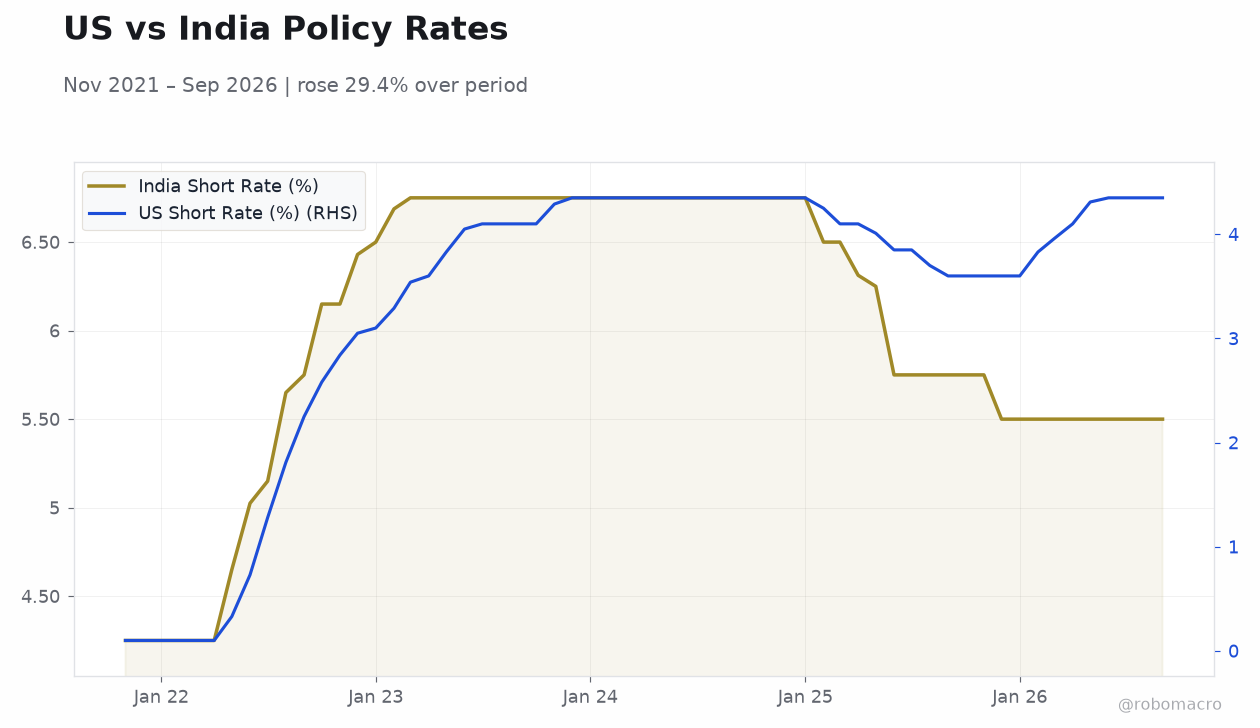
US vs India Policy RatesUS vs India Policy Rates | Type: macro_line | India Short Rate (%): 5.5 (2026-09-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5 | US Short Rate (%): 4.35 (2026-09-01) | Range: 0.1–4.35 | Trend(5pt): 0.1,3.1,4.35,4.01,4.35

Today's Economic Events

Data Prior Cons Time
No events available
  • India's September CPI inflation printed at 5.54%, above the 5.4% consensus and up from 4.82% prior, keeping the RBI's inflation-targeting framework under scrutiny.
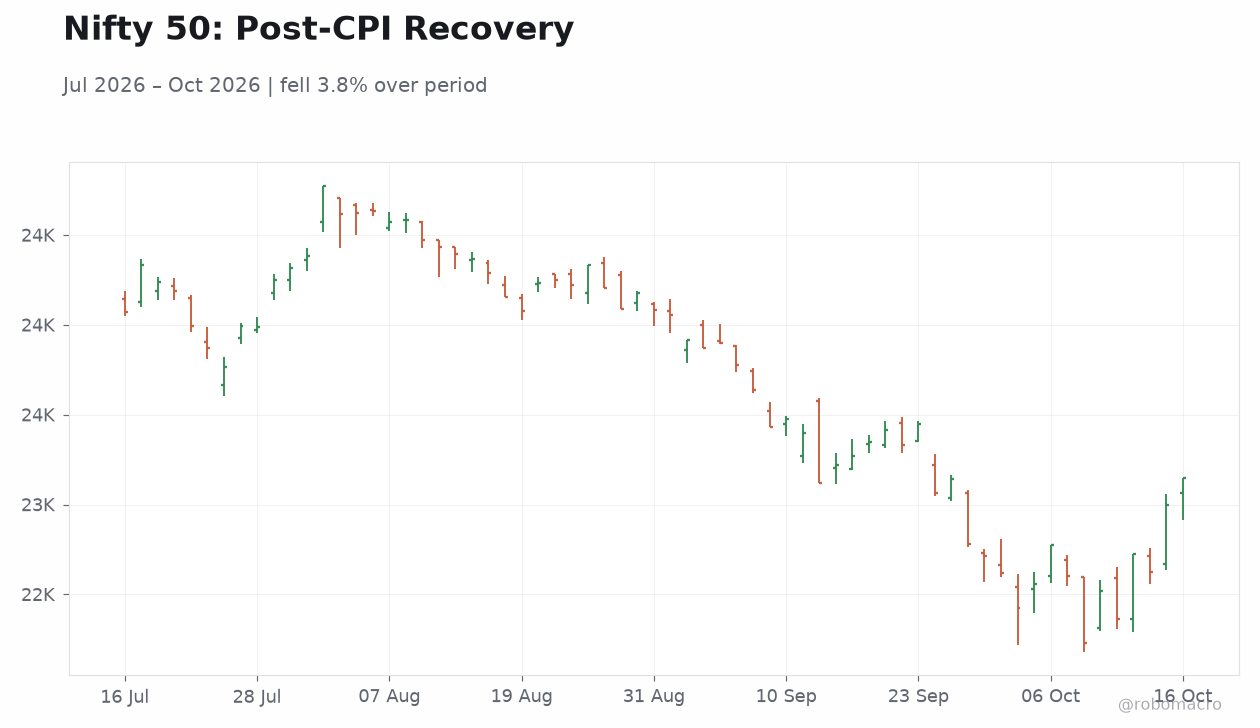
  • The Nifty 50 rose 0.65% to 23,146 and the Sensex gained 0.56% to 74,729, recovering from lows after the RBI's intervention to arrest the rupee's slide.
  • USD/INR firmed 0.45% to 94.95, while Brent crude fell 1.75% to $107.94, offering a modest terms-of-trade cushion for Asia's third-largest economy.

Yesterday's Recap

India's headline inflation rate for the year through the reference period was reported at 5.54%, exceeding both the 5.4% consensus and the prior 4.82% reading — a print that complicates the RBI's disinflation narrative just as the rupee demands attention. Equity markets responded constructively to the currency stabilisation: the Nifty 50 closed at 23,146.15, up 0.65%, and the Sensex finished at 74,729.27, higher by 0.56%, with the Sensex settling roughly 700 points above its intraday low. The recovery was attributed by domestic desks to the RBI's visible support for the rupee, which has been sliding toward the psychologically important 100-per-dollar level.

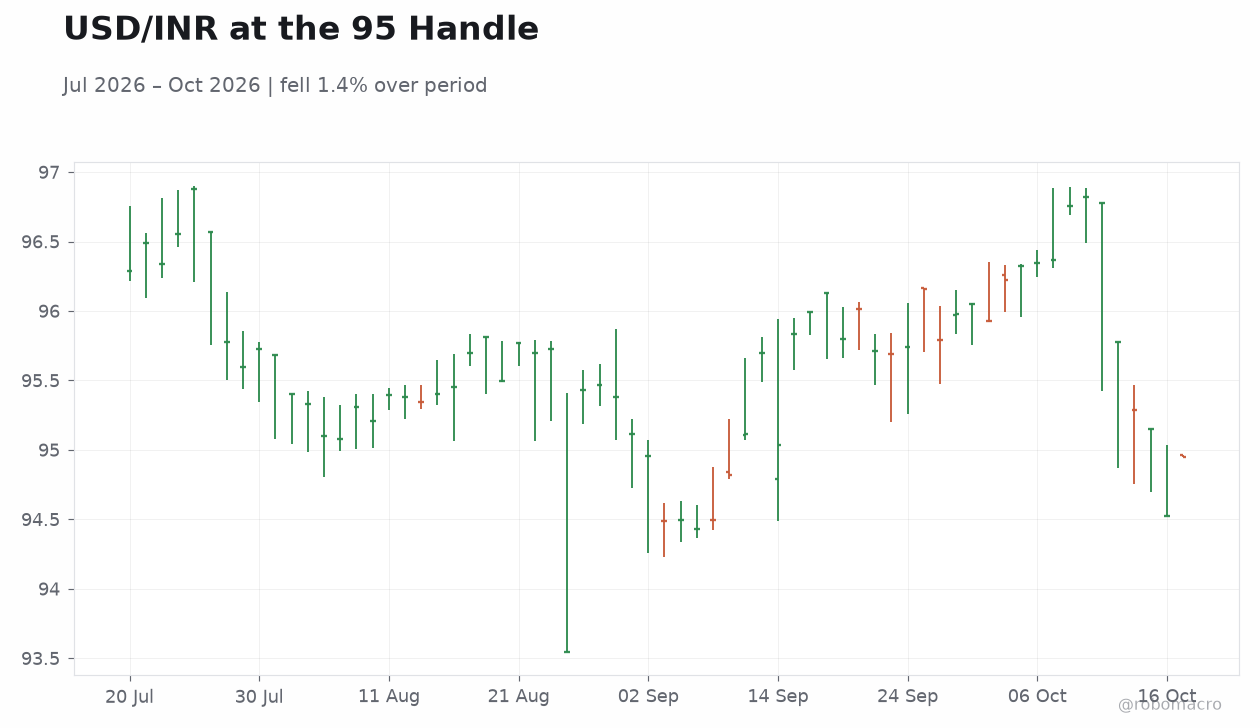
The currency itself closed at 94.95, weaker by 0.45% on the day, as importers continued hedging despite elevated costs following the central bank's liquidity measures. Government bond yields were not available in Friday's data, but press reports noted India bonds logged a ninth consecutive weekly loss despite aggressive RBI measures — a sign that OMO-style support has yet to fully anchor the long end. Brent crude declined 1.75% to $107.94, a tailwind for India's import bill, while gold held at $4,200.30, up 0.46%.

In policy news, the RBI approved the merger of Emirates NBD's India branches with RBL Bank effective December 1, and New Delhi rolled over a ₹3,000-crore currency swap facility for the Maldives.

The Day Ahead

The calendar is quiet on the data front, with no scheduled Indian releases for Sunday or Monday, leaving markets to digest the inflation surprise and currency dynamics into the new week. Attention shifts to how the rupee behaves at the 95 handle after the RBI's intervention, and whether the central bank extends its support toolkit — a question Finance Minister Sitharaman addressed by confirming the RBI will intervene to curb volatility rather than target a level. Equity desks will watch whether Friday's recovery in the Nifty near 23,150 extends, or whether the ninth straight weekly loss in bonds signals deeper positioning stress.

The US-India trade negotiation track also remains in focus, with Secretary of State Marco Rubio's planned visit seen as a potential catalyst for progress on the long-stalled deal. ↓ p.2
Page 1

India Macro Daily(Beta Mode)

October 18, 2026 robomacro.com
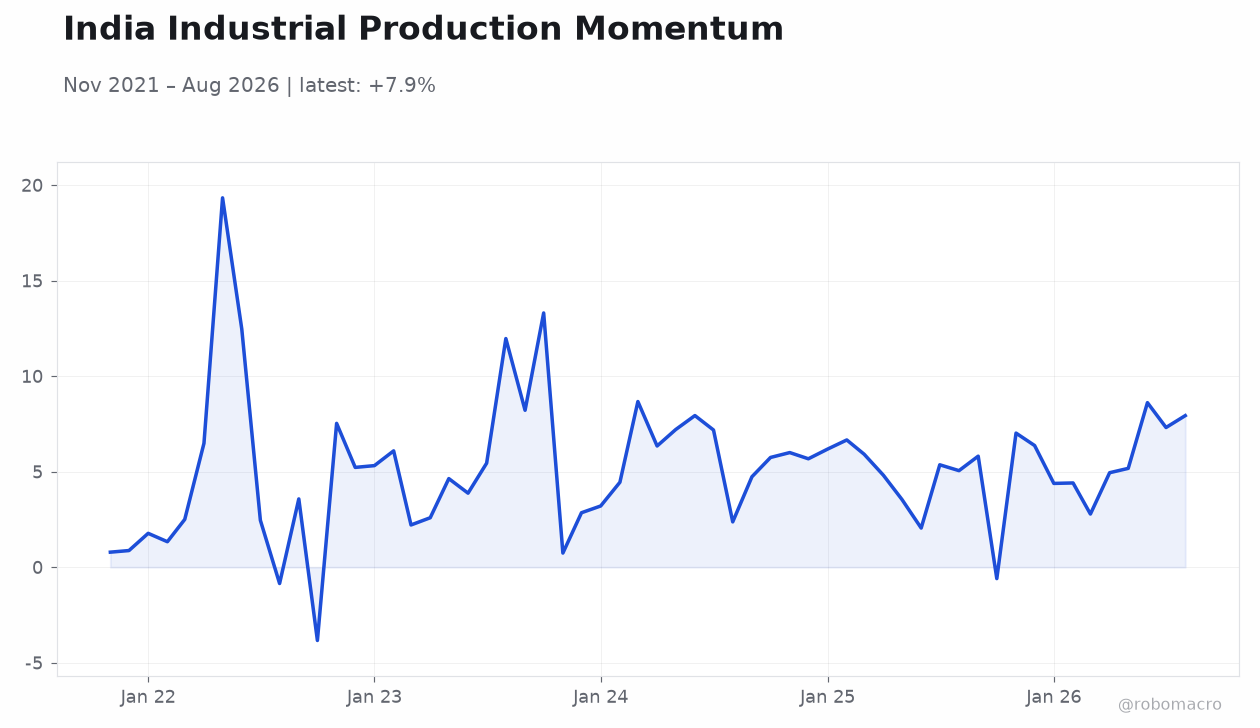
India Industrial Production Momentum India Industrial Production Momentum | Type: macro_line | Industrial Production Index: 7.935 (2026-08-01) | Range: -3.835–19.33 | Trend(6pt): 0.7882,5.318,8.671,3.545,7.313,7.935
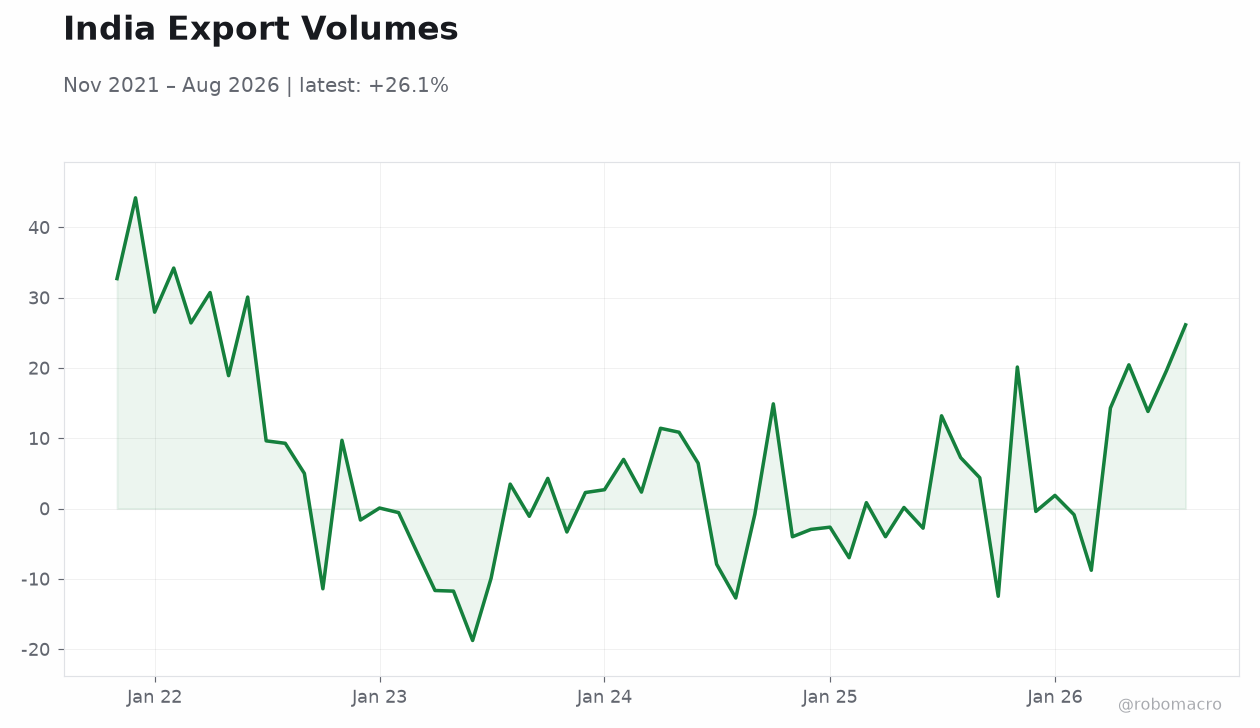
India Export Volumes India Export Volumes | Type: macro_line | Exports (Value): 26.13 (2026-08-01) | Range: -18.76–44.2 | Trend(6pt): 32.71,0.07788,2.343,0.1547,19.62,26.13
USD/INR at the 95 Handle USD/INR at the 95 Handle | Type: market_hloc | USD/INR: 94.95 (2026-10-19) | Range: 93.55–96.88 | Trend(6pt): 96.28,95.4,94.96,95.74,94.52,94.95
Nifty 50: Post-CPI Recovery Nifty 50: Post-CPI Recovery | Type: market_hloc | Nifty 50: 2.315e+04 (2026-10-16) | Range: 2.223e+04–2.477e+04 | Trend(5pt): 2.407e+04,2.457e+04,2.408e+04,2.345e+04,2.315e+04

The Day Ahead (continued)

Any follow-through commentary from RBI officials on liquidity management will be parsed closely given the bond market's tepid response to date.

Other Economic Notes

The inflation print at 5.54% arrives at an awkward moment for the growth-inflation trade-off: headline momentum has re-accelerated from 4.82% even as the rupee's depreciation feeds directly into imported goods costs, creating a second-round risk the MPC will need to model carefully. The weak currency has a mechanical consequence for headline GDP in dollar terms — IMF data now suggests India's $5-trillion economy milestone slips toward 2029 despite faster real growth, a reminder that nominal dollar comparisons are hostage to the exchange rate. Structural comparisons with China also resurfaced, with TRUST MF's CIO noting India compounded GDP at 7.3% over four decades versus China's 11.3% breakout pace, underscoring the reform agenda still needed to lift potential growth.

Meanwhile, the services trade surplus — India's key external cushion — faces a new test as global demand conditions soften.

Global Macro News

Global risk sentiment was mixed into the weekend, with Bitcoin up 0.81% to $82,039 and gold firming 0.46% to $4,200.30, consistent with continued demand for hard assets amid currency volatility across emerging markets. Indonesia's equity market suffered its biggest one-day fall in nearly 30 years, a reminder that EM idiosyncratic shocks can spill into regional risk appetite and complicate the funding environment for the broader EM complex, India included. ↓ p.3

Sponsored by Arbitrage Search
Page 2

India Macro Daily(Beta Mode)

October 18, 2026 robomacro.com

Continuation

Global Macro News (continued)

Brent crude's 1.75% decline to $107.94 is unambiguously positive for India's current account, given the country imports over 80% of its oil, and provides the RBI room to defend the rupee without an immediate terms-of-trade deterioration. The EUR/INR cross at 106.58, up marginally, reflects broad dollar strength rather than euro-specific dynamics. The stalled US-India trade deal remains the key bilateral overhang, with both tariff and market-access questions unresolved ahead of Rubio's visit.

For global funds, India's relative growth resilience continues to anchor allocations, but the currency's slide toward 100 per dollar is testing the patience of foreign portfolio investors already weighing higher hedging costs.

RBI Watch

The central bank's recent posture has been distinctly defensive on the currency: press coverage confirms the RBI has "arrested the rupee's slide" through aggressive measures, though bond markets have handed back the benefit with a ninth straight weekly loss, suggesting liquidity support has been calibrated to defend the currency rather than the long end. Sitharaman's public reassurance that the RBI will intervene only to curb volatility — not defend a level — is consistent with the bank's long-standing two-way risk philosophy and signals tolerance for gradual depreciation toward, but not a disorderly break of, the 100-per-dollar threshold. The September CPI at 5.54%, above consensus, tightens the constraint on any near-term easing bias; with headline momentum re-accelerating from 4.82%, the MPC's inflation-targeting credibility is back in focus, and the recent repo hike to 5.50% looks well-judged in hindsight.

Importers continuing to hedge despite higher costs suggests the market expects the central bank's support to be temporary rather than a new regime. The approval of the Emirates NBD–RBL Bank merger from December 1 reflects the RBI's ongoing consolidation agenda in the banking sector. Watch for the next set of MPC minutes and liquidity-operation announcements for confirmation of whether the bank prioritises currency stability or yield-curve calm as the rupee tests key levels.

Sponsored by Arbitrage Search
Page 3