India Macro Daily(Beta Mode)
Oil Surge Weighs on Rupee and Equities
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 22,888.95 | -1.11% |
| Sensex | 73,852.90 | -1.17% |
| USD/INR | 94.81 | +0.53% |
| EUR/INR | 106.45 | +0.38% |
| Reliance | 1,184.50 | -2.03% |
| HDFC Bank | 694.05 | -1.82% |
| Brent Crude | 113.01 | +3.85% |
| Gold | 4,036.00 | -2.75% |
| Bitcoin | 81,121.63 | -3.44% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
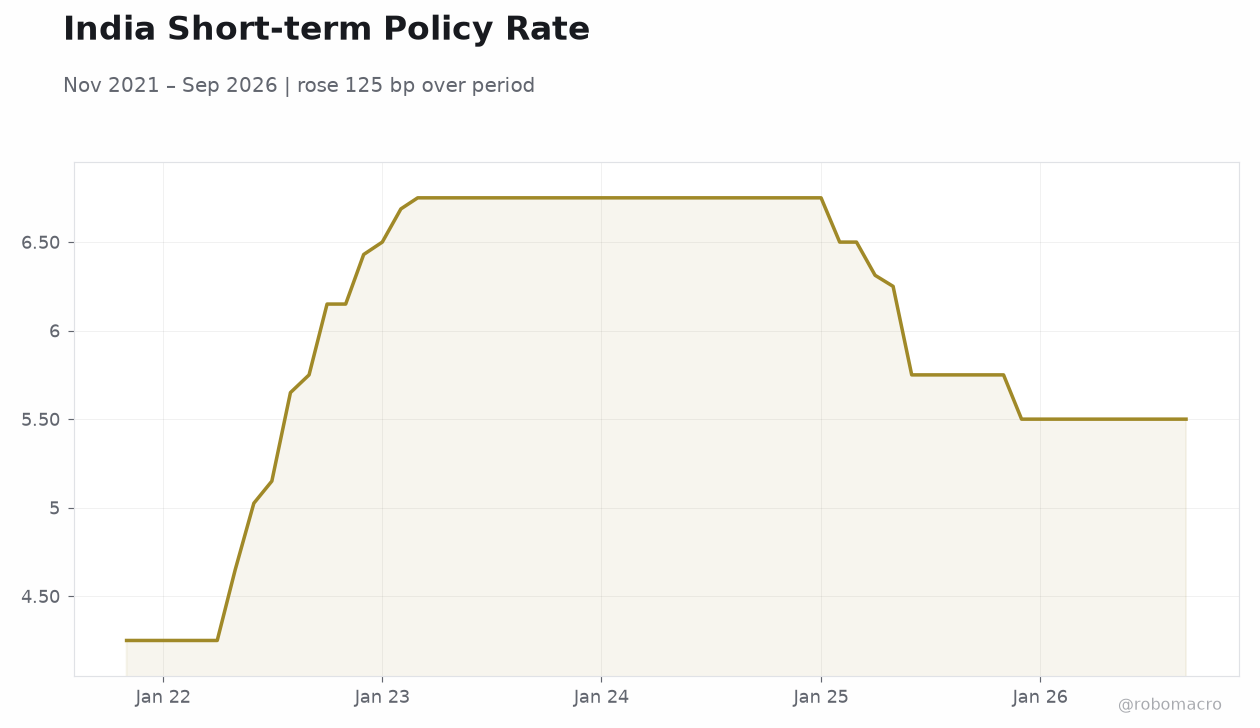 India Short-term Policy Rate | Type: macro_line | Policy Rate %: 5.5 (2026-09-01) | Range: 4.25–6.75 | Trend(5pt): 4.25,6.5,6.75,6.25,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
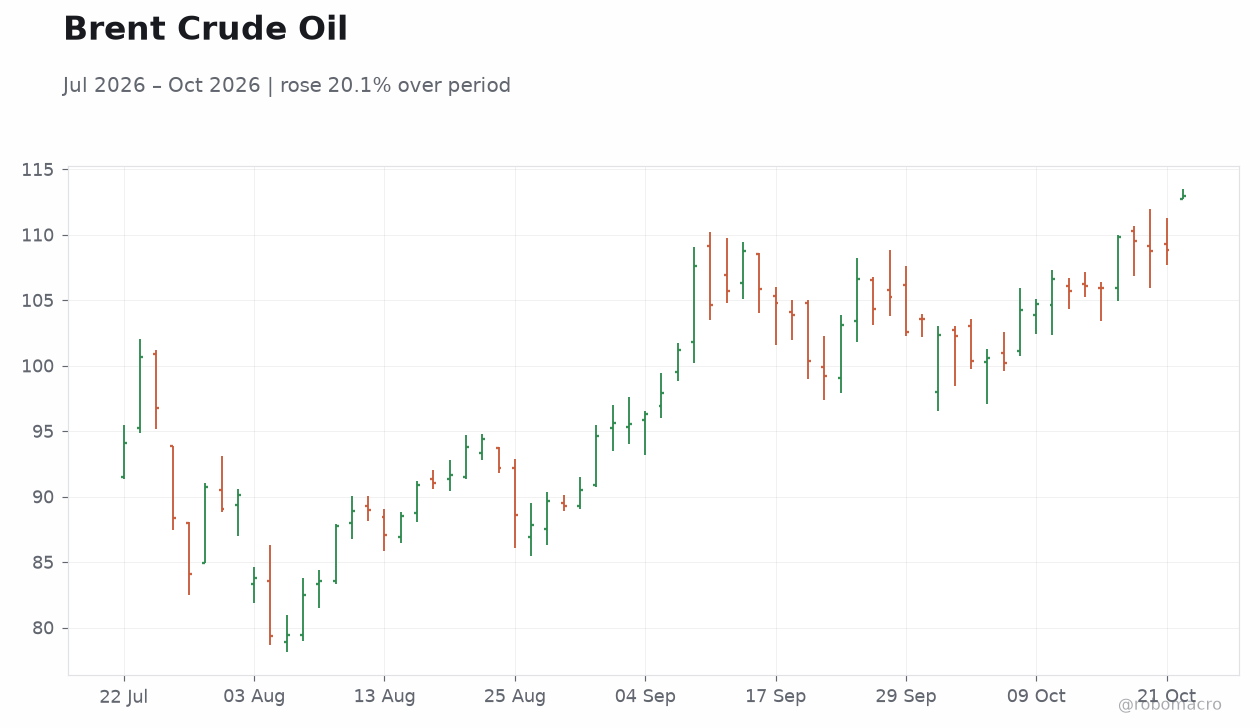
- Equities fell over 1% as Brent crude jumped 3.85% to $113.01, stoking inflation concerns.
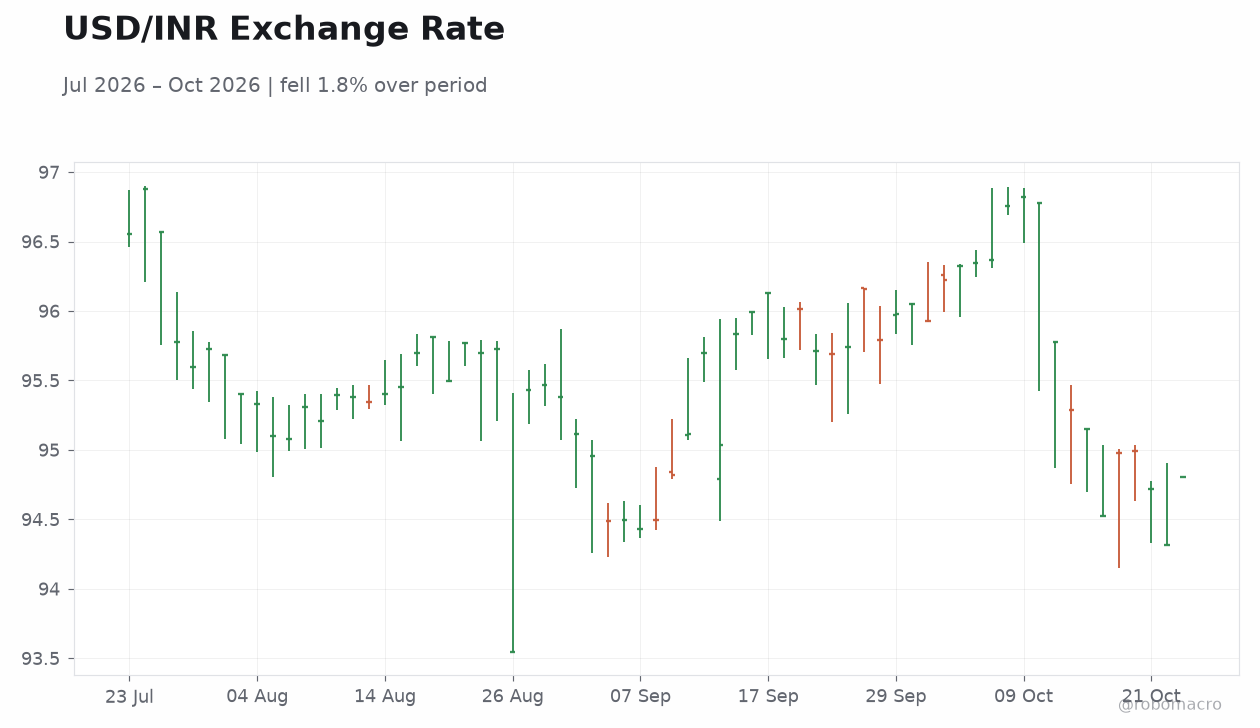
- Rupee weakened 0.53% to 94.81 despite RBI interventions amid persistent dollar demand.
- Hawkish RBI signals and Jio IPO inflows shape near-term currency and rate expectations.
Yesterday's Recap
Indian equities closed lower with Nifty 50 dropping 1.11% to 22,888.95 and Sensex declining 1.17% to 73,852.90, led by losses in Reliance and HDFC Bank. Brent crude’s sharp advance to 113.01 amplified selling in rate-sensitive sectors and triggered bond yield spikes. The rupee ended at 94.81 against the dollar after RBI stepped in to curb volatility, though interventions proved insufficient to offset oil-driven outflows.
Gold fell 2.75% to 4,036 while Bitcoin slid 3.44%, reflecting broader risk-off sentiment. No major data prints emerged, leaving market focus on RBI’s ongoing rupee defense and September macro trends. Jio Platforms’ IPO attracted rapid subscription, raising prospects of fresh foreign inflows in coming sessions.
Overall, Thursday’s moves reversed the rupee’s recent winning streak and highlighted external price pressures on domestic assets.
The Day Ahead
Markets will monitor Jio IPO settlement flows and any fresh RBI liquidity operations for rupee support. Traders await updates on oil import costs and their pass-through to domestic inflation readings. Sentiment hinges on global dollar direction and trade-related optimism that could ease import pressures.
Analysts expect continued RBI vigilance on USD/INR near 94.80–95.00 levels. Equity flows may stabilize if crude prices consolidate below recent highs. Focus remains on forward guidance from recent MPC communications rather than new data releases.
Other Economic Notes
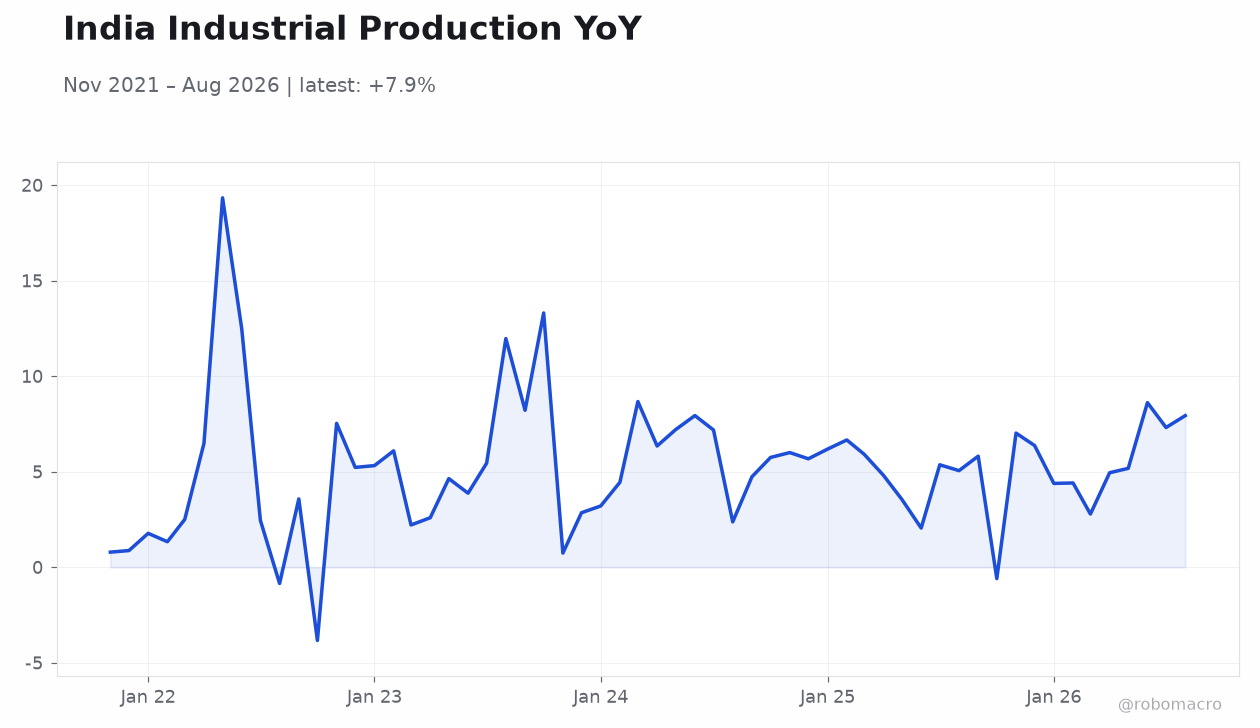
September macro indicators showed resilient industrial output and services activity despite external headwinds. Import demand for silver remained subdued even after authorities approved 6,500 tonnes of additional shipments. Former RBI officials cautioned against using the exchange rate as a primary stabilizer, warning of potential damage to real-economy competitiveness.
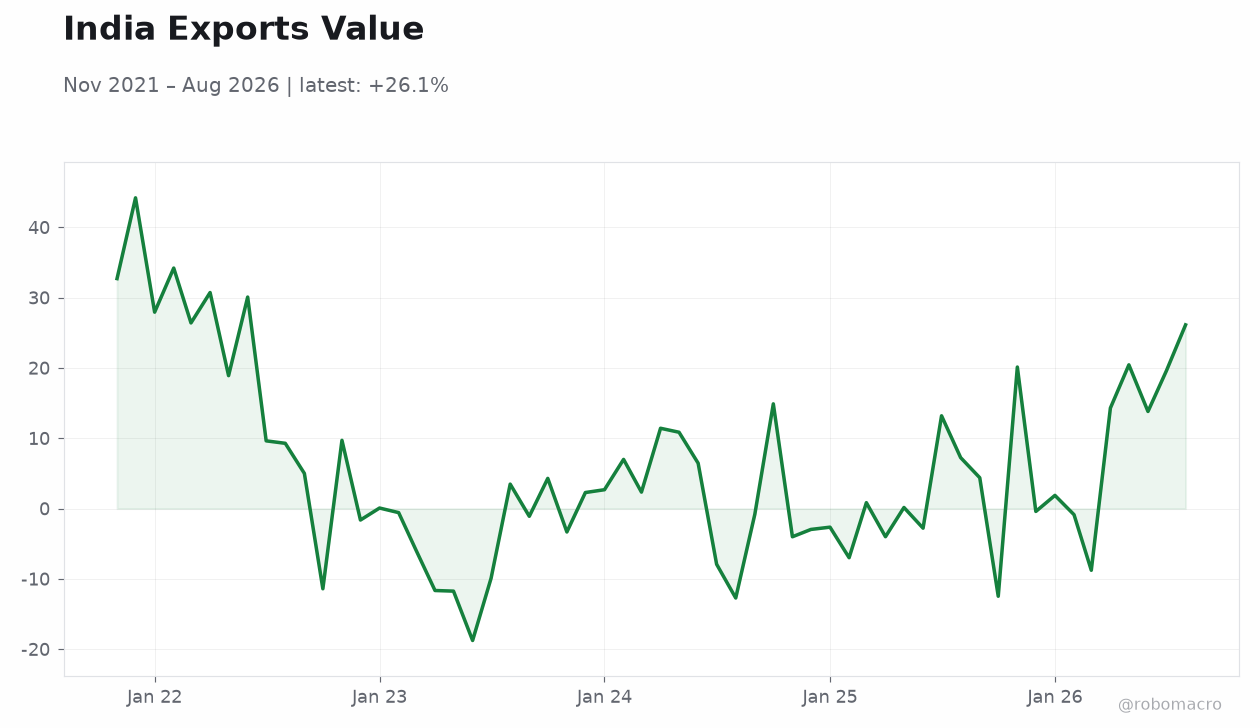
Interest-rate differentials versus G7 economies stay in focus as policymakers balance growth and price stability. Trade optimism from bilateral deals offers a partial offset to commodity-driven current-account risks.