India Macro Daily(Beta Mode)
Rupee Steadies as RBI Signals Hands-Off Approach
Market Snapshot
| Asset | Level | Change |
|---|---|---|
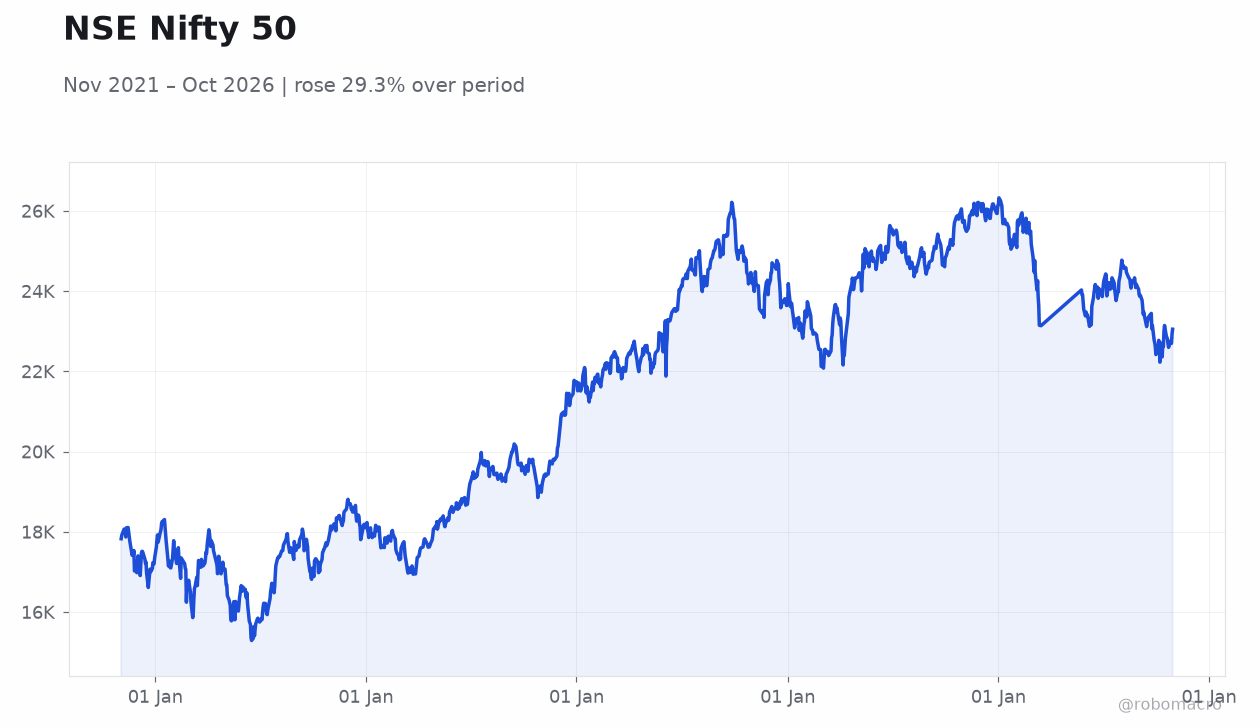
| Nifty 50 | 23,053.10 | +0.51% |
| Sensex | 74,459.53 | +0.42% |
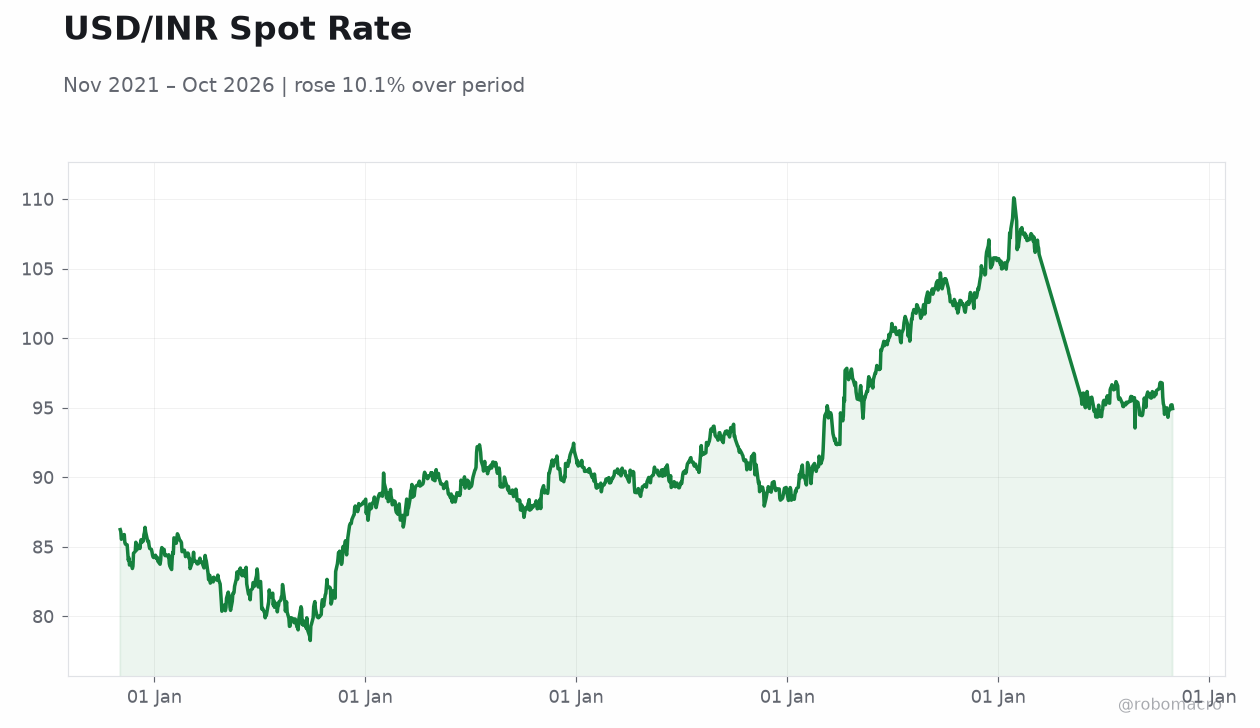
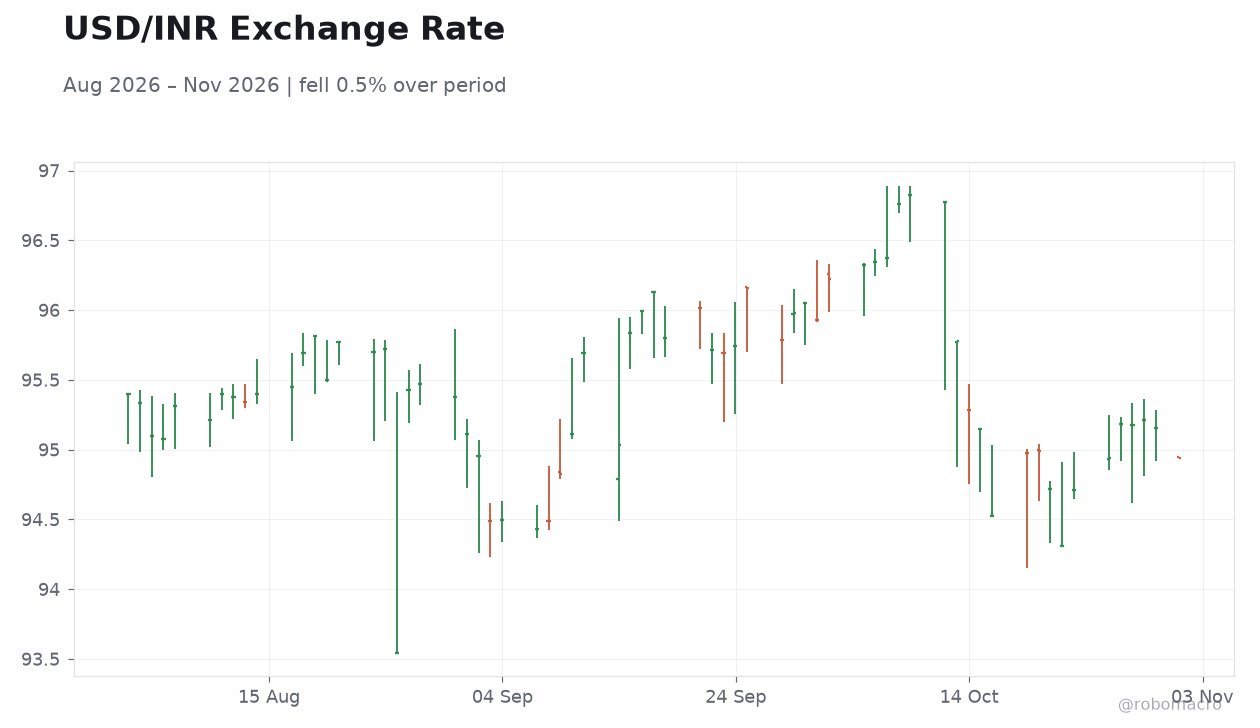
| USD/INR | 94.94 | -0.22% |
| EUR/INR | 105.95 | -0.42% |
| Reliance | 1,164.90 | -0.21% |
| HDFC Bank | 692.80 | +1.39% |
| Brent Crude | 111.79 | -4.97% |
| Gold | 3,906.70 | +0.20% |
| Bitcoin | 78,053.21 | +0.80% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Year-over-Year | 8 | 7.20 | 6.70 |
| Manufacturing Production Year-over-Year | 9 | - | 7.60 |
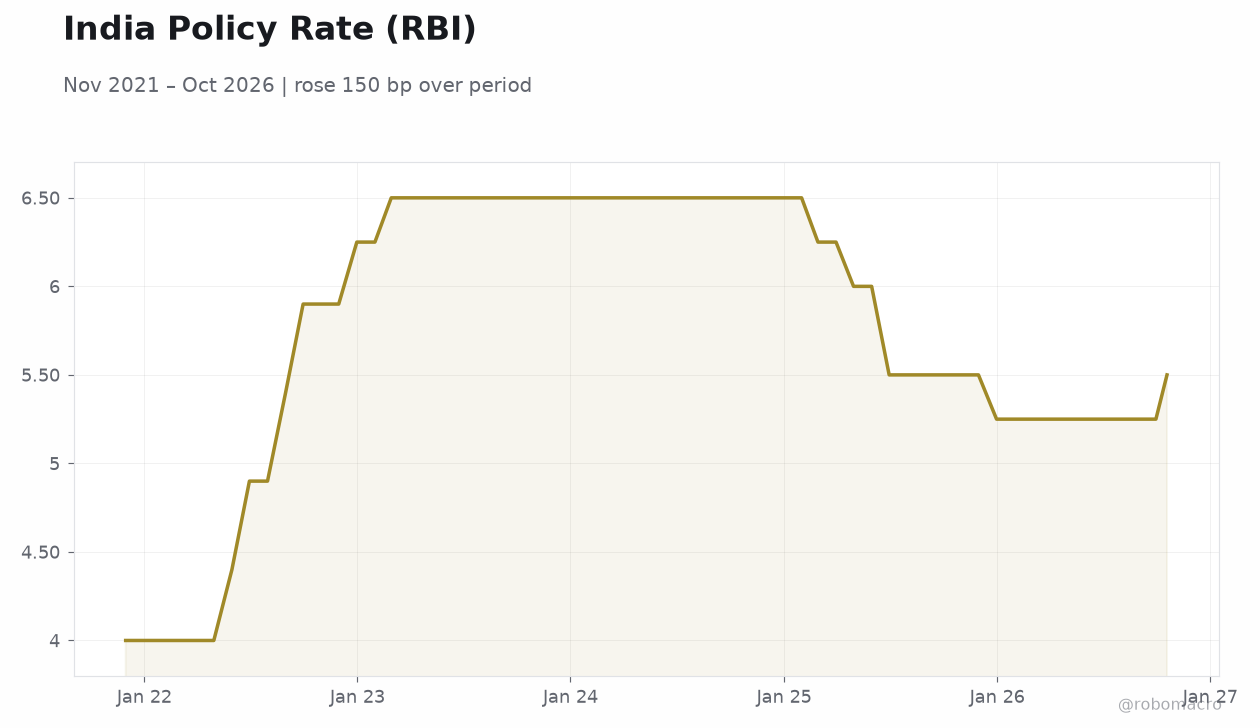 India Policy Rate (RBI) | Type: macro_line | Policy rate %: 5.5 (2026-10-19) | Range: 4–6.5 | Trend(4pt): 4,6.5,6.5,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Rupee stabilizes near 94.94/USD after approaching the 95 mark, with traders noting reduced RBI intervention intensity
- Industrial production growth decelerates to 6.7% YoY, missing consensus of 7.2%
- Forex reserves decline for seventh consecutive week to $719.75 billion, down $1.27 billion
Yesterday's Recap
India's industrial production growth slowed to 6.7% year-over-year, below consensus expectations of 7.2% and marking a deceleration from the previous 8% pace. Manufacturing output expanded 7.6% annually, down from 9% in the prior period. Equity markets posted solid gains with the Nifty 50 advancing 0.51% to 23,053.10 and the Sensex rising 0.42% to 74,459.53, capping the benchmark's best month since July as Indian stocks emerged as a haven from global technology volatility.
The rupee strengthened 0.22% to 94.94 against the dollar, recovering from near-95 levels, though traders flagged that RBI interventions have "mellowed" in recent sessions. HDFC Bank shares gained 1.39% while Reliance dipped 0.21%. Brent crude plunged 4.97% to $111.79 per barrel, providing relief for India's import bill.
The Day Ahead
The economic calendar is light with no major scheduled data releases for November 1. Market participants will focus on secondary market dynamics and positioning ahead of next week's flow. Traders will monitor rupee levels closely following the currency's best monthly performance in eight months, driven by RBI measures to curb dollar demand.
Attention remains on global crude price movements after yesterday's sharp decline, which could influence import cost expectations. With no domestic catalysts, sentiment will likely track regional equity trends and any fresh RBI communications on liquidity management.
Other Economic Notes
India's forex reserves fell $1.27 billion to $719.75 billion in the week ended October 23, marking the seventh straight weekly decline as the RBI manages currency stability amid persistent external pressures. The central bank's proposed preferential trade agreement with Mexico could enhance price competitiveness for Indian exporters through negotiated tariff concessions. Fresh bank lending rates declined to 8.51% in September while deposit rates eased, reflecting transmission of earlier policy rate adjustments.
The RBI Central Board convened to review India's economic outlook, discussing potential risks and challenges facing the growth trajectory. The IMF flagged El Niño as a downside risk for India while advocating that the RBI allow the rupee to move more freely.