India Macro Daily(Beta Mode)
Rupee Rallies as Oil Relief Lifts Markets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
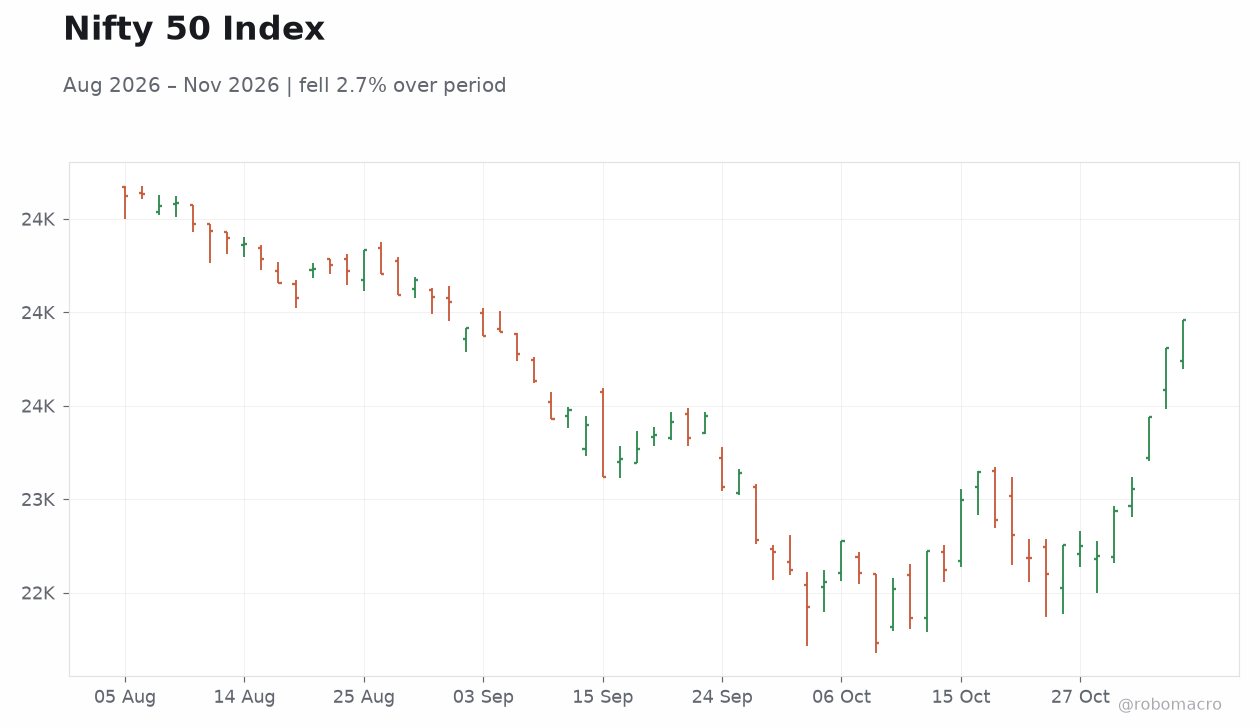
| Nifty 50 | 23,960.60 | +0.63% |
| Sensex | 77,301.40 | +0.50% |
| USD/INR | 94.52 | -0.25% |
| EUR/INR | 106.16 | +0.06% |
| Reliance | 1,313.40 | +0.18% |
| HDFC Bank | 760.00 | +3.16% |
| Brent Crude | 98.95 | +4.58% |
| Gold | 4,111.40 | +0.94% |
| Bitcoin | 76,049.45 | -5.42% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
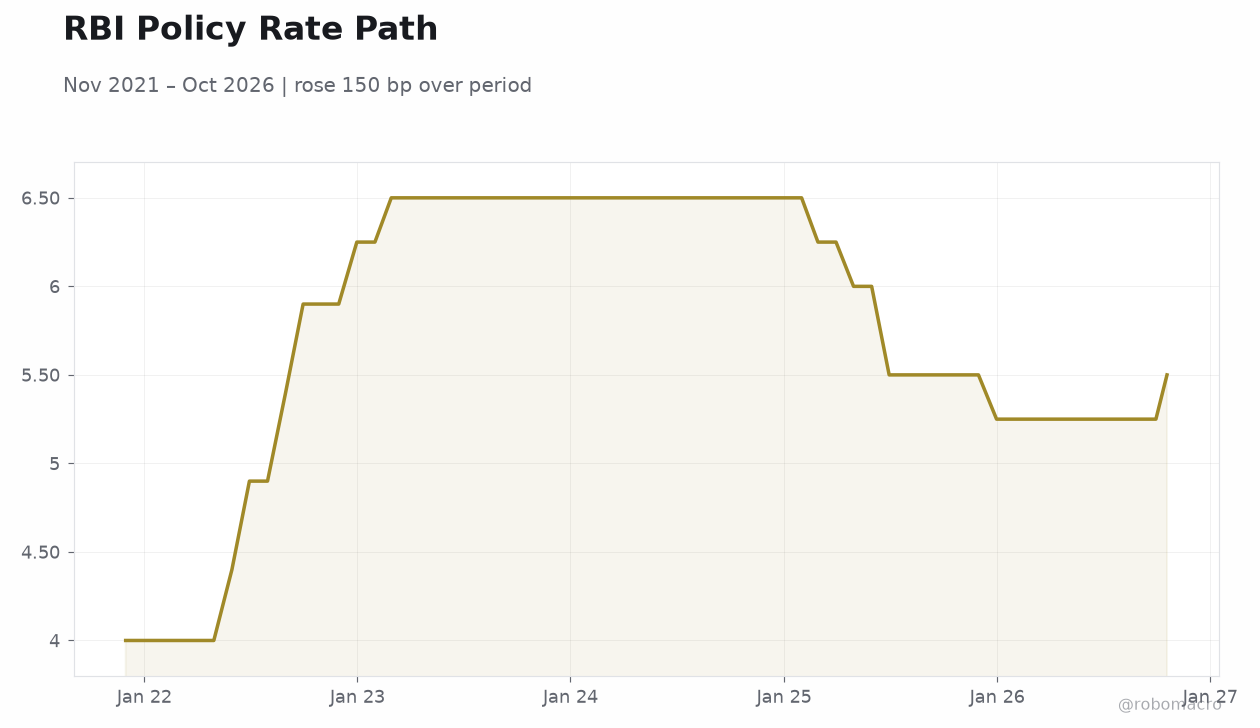 RBI Policy Rate Path | Type: macro_line | Policy rate (%): 5.5 (2026-10-19) | Range: 4–6.5 | Trend(4pt): 4,6.5,6.5,5.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Rupee extends gains on weaker dollar and US midterm election fallout, with USD/INR at 94.52 (-0.25%)
- Nifty 50 reclaims 23,960 (+0.63%) as foreign flows and earnings drive India to top Asia performer
- Services PMI hits four-month peak at 55.8; RBI dismisses banknote shortage rumors ahead of festive season
Yesterday's Recap
Indian equities posted solid gains with the Nifty 50 advancing 0.63% to 23,960.60 and the Sensex rising 0.50% to 77,301.40, with HDFC Bank notably outperforming at +3.16%. The rupee strengthened 0.25% against the dollar to 94.52, extending its rally as US midterm election results weighed on the greenback. Brent crude, however, jumped 4.58% to $98.95, complicating the oil-import narrative even as broader commodity relief supported sentiment.
The HSBC India Services PMI rose to 55.8 in October, a four-month peak driven by strong domestic demand, with cost pressures easing to a six-year low. Gold gained 0.94% to $4,111.40 while Bitcoin slumped 5.42% to $76,049.45, reflecting risk-off positioning in crypto even as equities rallied. Foreign institutional flows and strong earnings helped India's benchmark become the top gainer in Asia this quarter, up nearly 6%.
India 2Y and 10Y G-Sec yields were not reported in the snapshot.
The Day Ahead
No major scheduled India data releases are on the calendar for today, leaving markets to digest yesterday's services PMI strength and the rupee's continued appreciation. Traders will focus on the RBI's household inflation expectations, consumer confidence, and jobs surveys launched this week, which could offer early signals on demand conditions ahead of the December MPC. Bond markets will watch for any RBI liquidity operations and the trajectory of the 10-year yield amid the oil price spike.
Equity flows remain the key swing factor, with foreign buying supporting the recent rally and earnings season providing sector-specific catalysts. The rupee's break below 95 will be closely monitored for import-cost pass-through implications.
Other Economic Notes
The weak monsoon is emerging as a structural risk to India's ethanol blending programme, with rising food prices potentially forcing policymakers to prioritize food security over fuel blending targets. Ten years after demonetization, India's cash habit has survived the UPI boom, underscoring the persistence of currency in circulation even as digital payments scale. Sebi has tightened rupee derivative norms to align with the RBI's $5 million threshold, harmonizing regulatory treatment across cash and derivative segments.
↓ p.2