India Macro Daily(Beta Mode)
Rupee Firms as RBI Defends; Rate-Hike Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
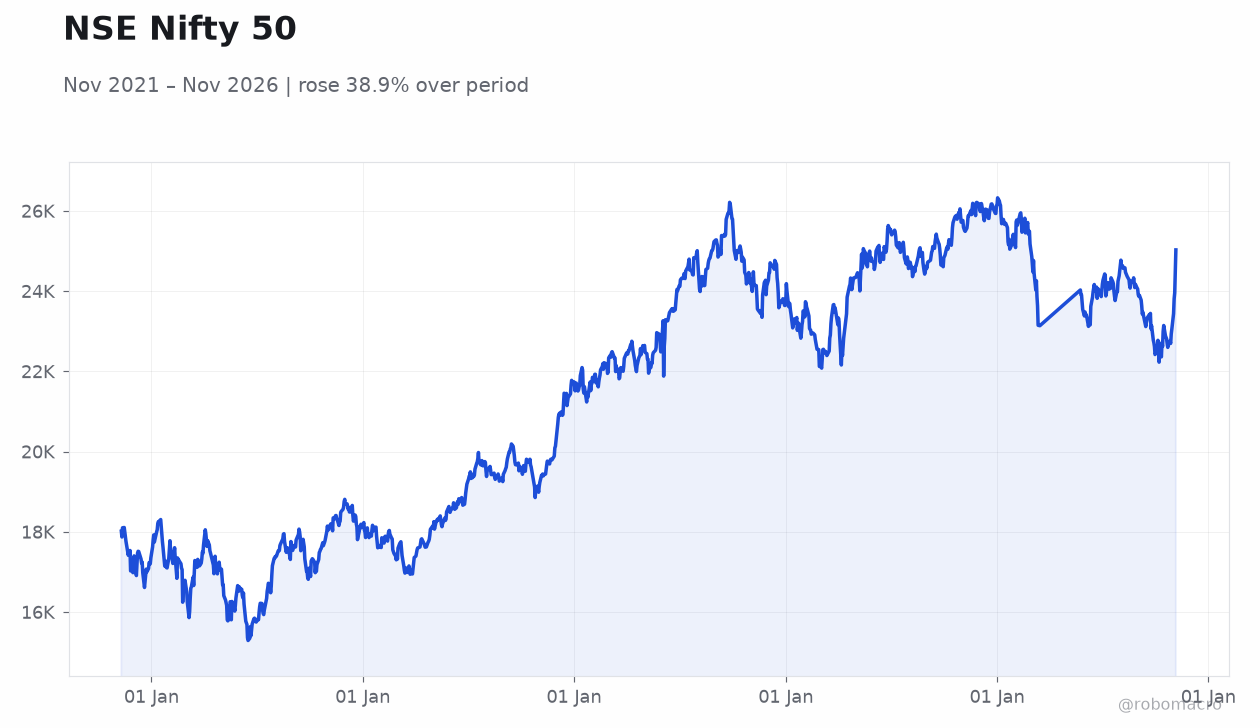
| Nifty 50 | 24,986.40 | -0.18% |
| Sensex | 80,999.40 | -0.04% |
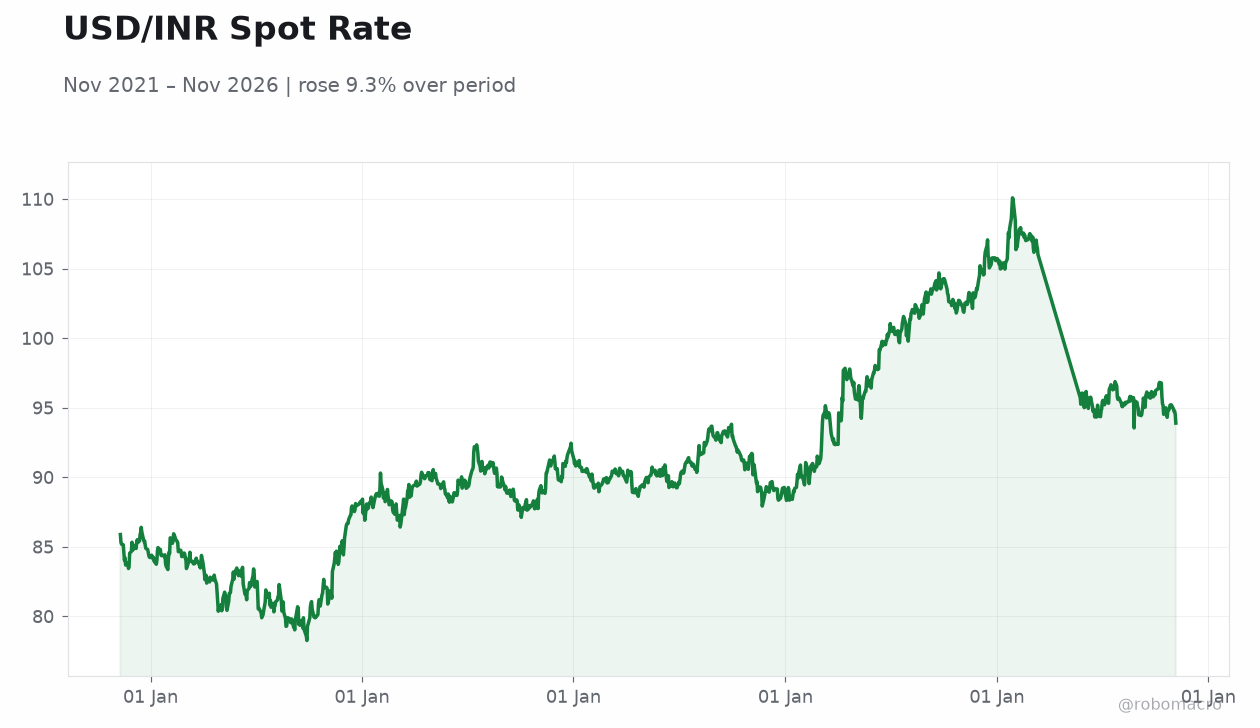
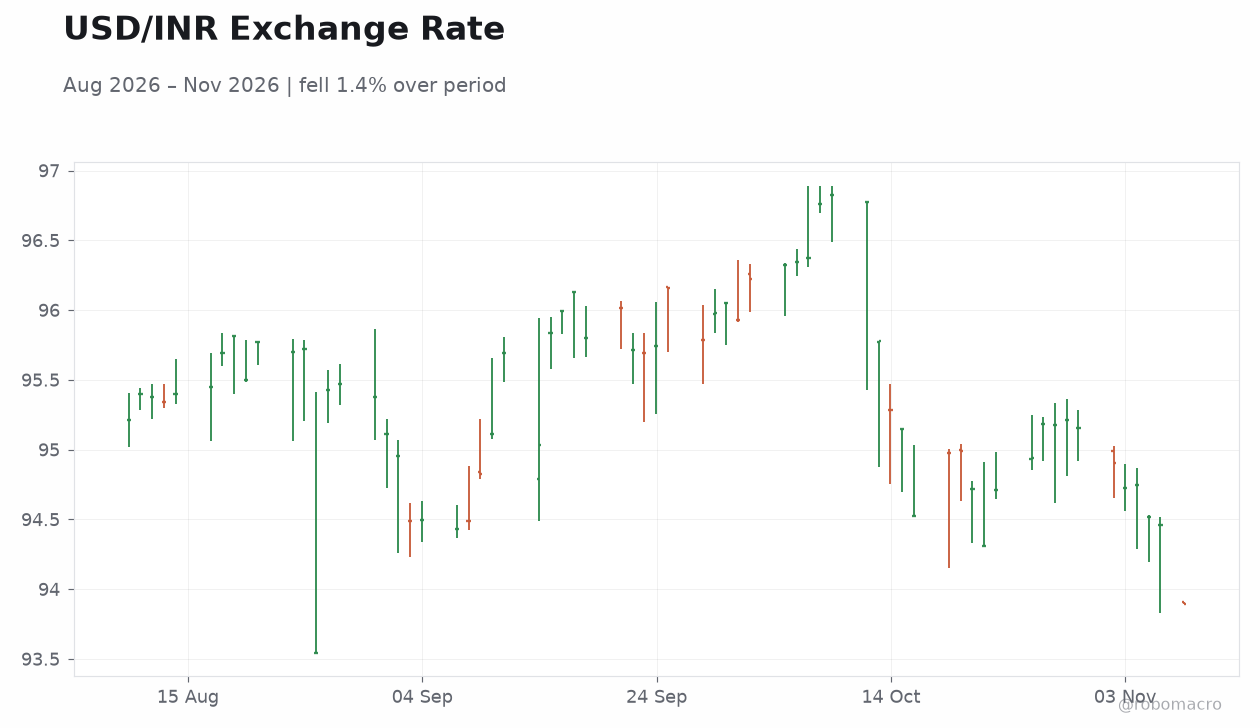
| USD/INR | 93.89 | -0.60% |
| EUR/INR | 104.72 | -1.20% |
| Reliance | 1,320.00 | +0.50% |
| HDFC Bank | 788.25 | +3.72% |
| Brent Crude | 97.48 | -0.85% |
| Gold | 4,076.00 | +0.03% |
| Bitcoin | 74,962.85 | -1.04% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
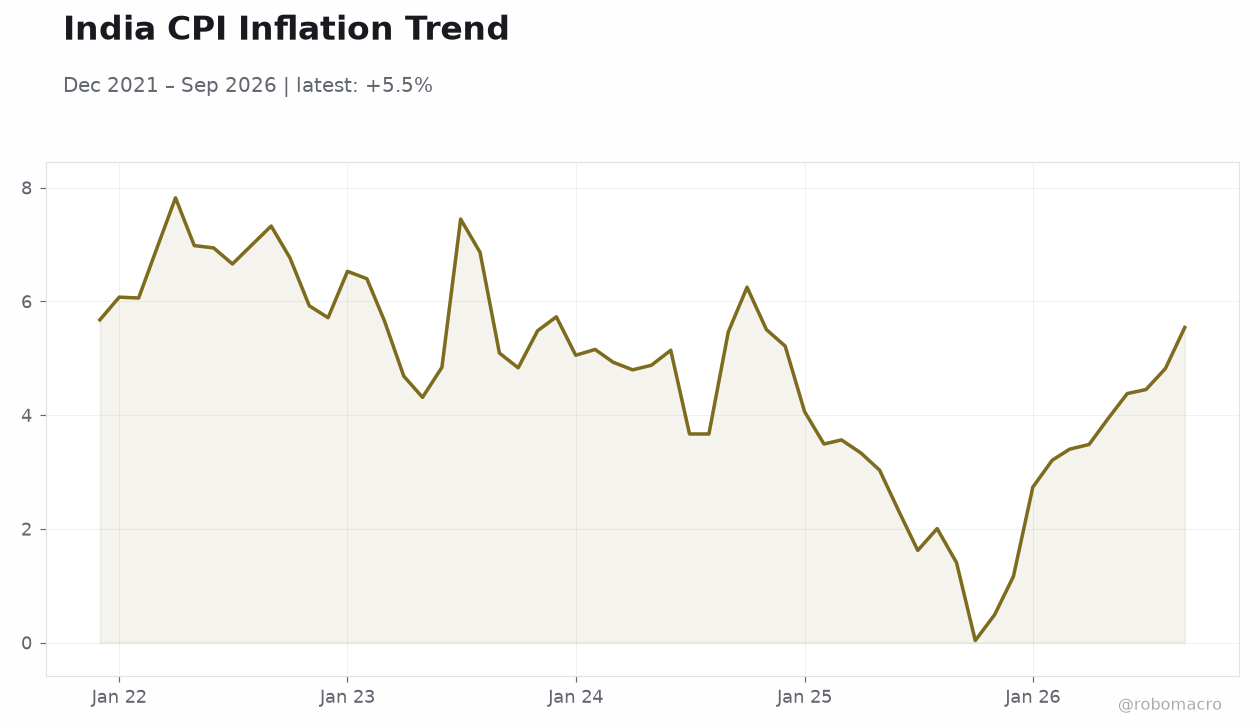
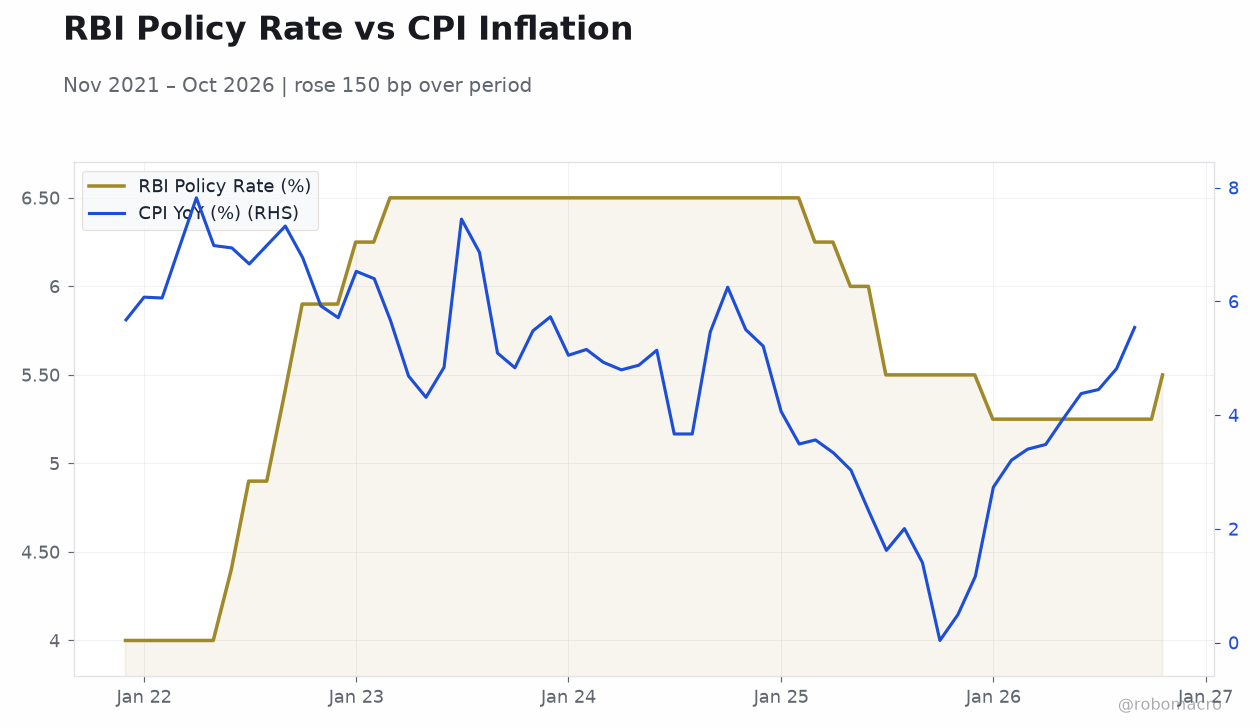 RBI Policy Rate vs CPI Inflation | Type: macro_line | RBI Policy Rate (%): 5.5 (2026-10-19) | Range: 4–6.5 | Trend(4pt): 4,6.5,6.5,5.5 | CPI YoY (%): 5.543 (2026-09-01) | Range: 0.03857–7.822 | Trend(6pt): 5.676,6.4,4.797,2.305,4.82,5.543
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Rupee strengthens to a six-month high near 94.08 as RBI dollar sales cap depreciation; forex reserves fall $2.69bn to $717.06bn.
- HDFC Bank jumps 3.72% even as Nifty slips 0.18% to 24,986.40; Sensex flat at 80,999.40.
- DBS flags higher inflation supporting rate-hike bets; India Inc overseas investment up 40.8% in FY26.
Yesterday's Recap
Indian equities ended mixed, with the Nifty 50 easing 0.18% to 24,986.40 and the Sensex essentially flat at 80,999.40, down 0.04%. The standout was HDFC Bank, which surged 3.72% to 788.25, while Reliance added 0.50% to 1,320.00. The rupee strengthened sharply, with USD/INR falling 0.60% to 93.89 and EUR/INR dropping 1.20% to 104.72, as reported RBI intervention supported the currency near six-month highs.
Forex reserves fell $2.69 billion to $717.06 billion, reflecting dollar sales used to defend the rupee. Brent crude slipped 0.85% to 97.48, offering marginal relief on the import bill, while gold was flat at 4,076.00. India 2-year and 10-year G-Sec yields were not populated in the supplied data and are omitted.
The Day Ahead
The calendar is empty for both today and tomorrow, leaving markets to trade on positioning and external cues. With no domestic data scheduled, attention shifts to the inflation print expected later this week, which DBS cites as the key driver of rate-hike expectations. Traders will watch whether the rupee can hold its gains near 94 and whether RBI continues absorbing dollar demand.
Equity flows remain sensitive to the prior session's rally narrative, with Nifty support near 25,000 in focus. Global risk appetite, particularly the Nasdaq's sharp drawdown, will shape the opening bias.
Other Economic Notes
India's overseas investment pipeline remains robust, with outbound flows up 40.8% in FY26 and the FDI-ODI ratio narrowing to 4.2, per RBI data. The government has doubled its rice sale target under the open market scheme to 5 million tonnes for 2026-27, a move aimed at tempering food price pressures. Fiscal arithmetic remains tight, with commentary highlighting thin budget margins as subsidy and capex demands compete.
The rupee's resilience is being tested against a strong dollar and elevated crude, keeping imported inflation risk alive. These crosscurrents argue for caution on the inflation trajectory into year-end.