India Macro Daily(Beta Mode)
Rupee Rally Tests RBI's Resolve
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 25,044.65 | +0.06% |
| Sensex | 81,028.02 | +2.17% |
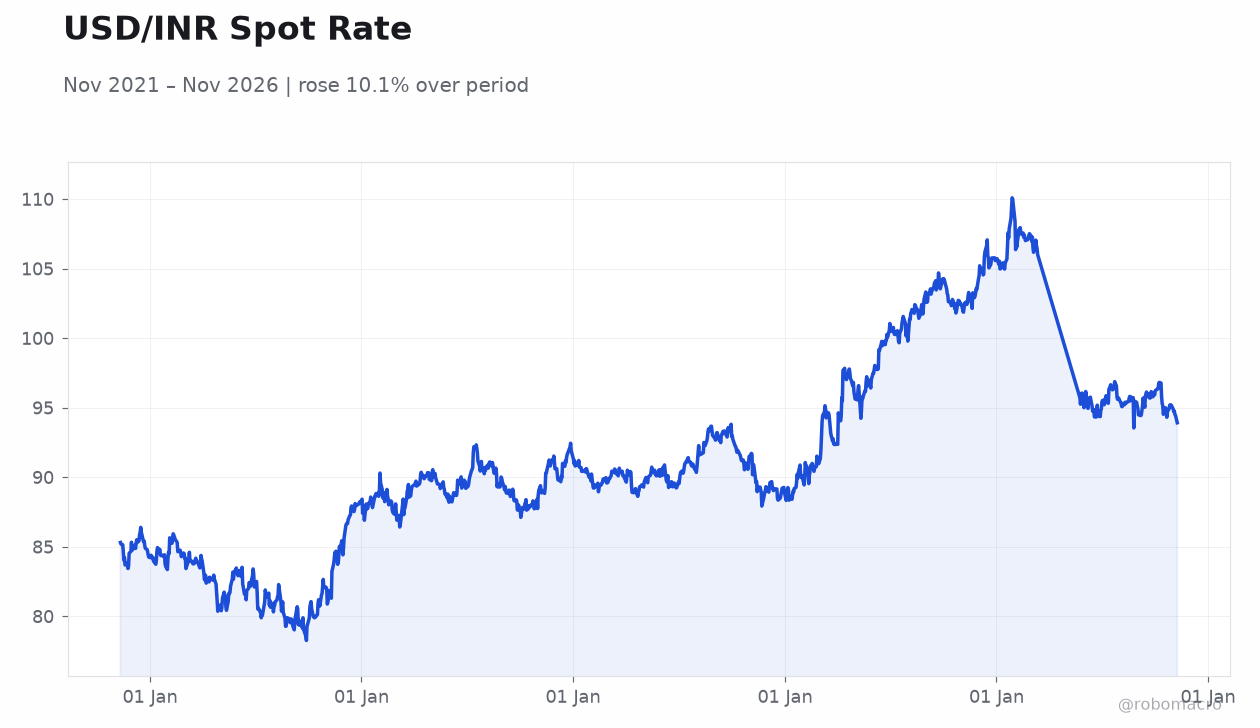
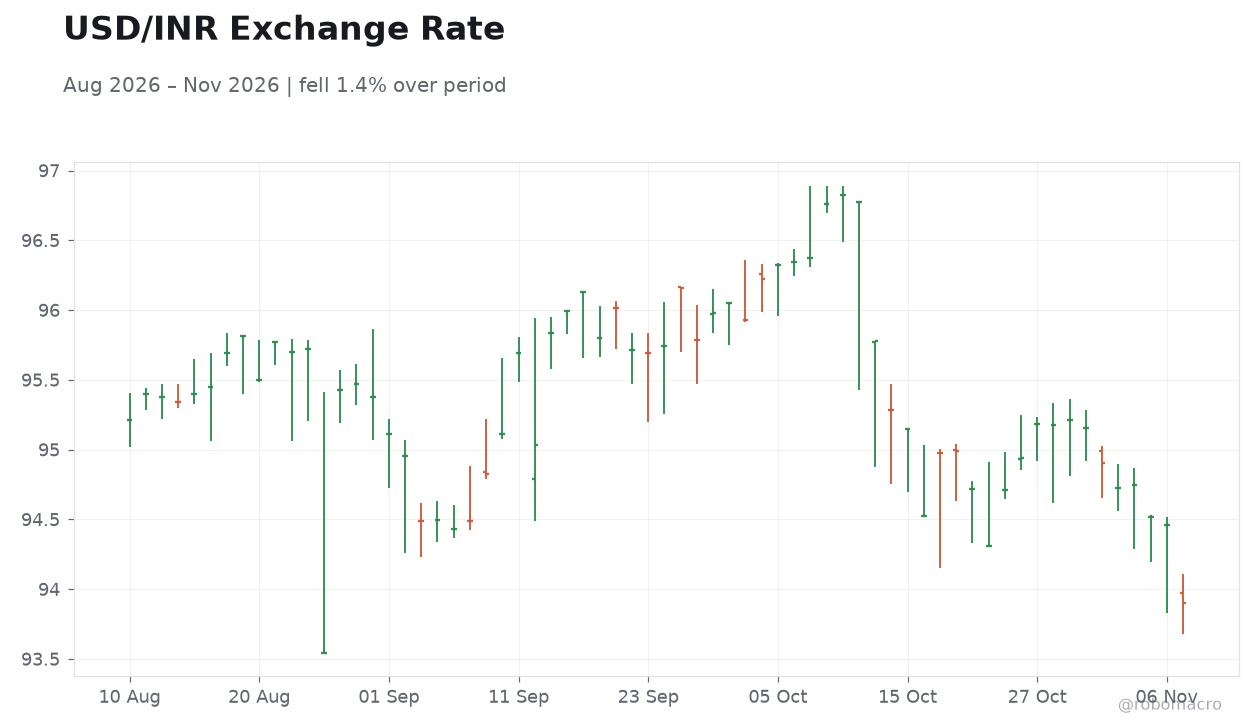
| USD/INR | 93.90 | -0.59% |
| EUR/INR | 104.54 | -1.38% |
| Reliance | 1,320.00 | +0.50% |
| HDFC Bank | 788.25 | +3.72% |
| Brent Crude | 92.41 | -6.01% |
| Gold | 4,137.50 | +1.54% |
| Bitcoin | 74,961.93 | +0.51% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
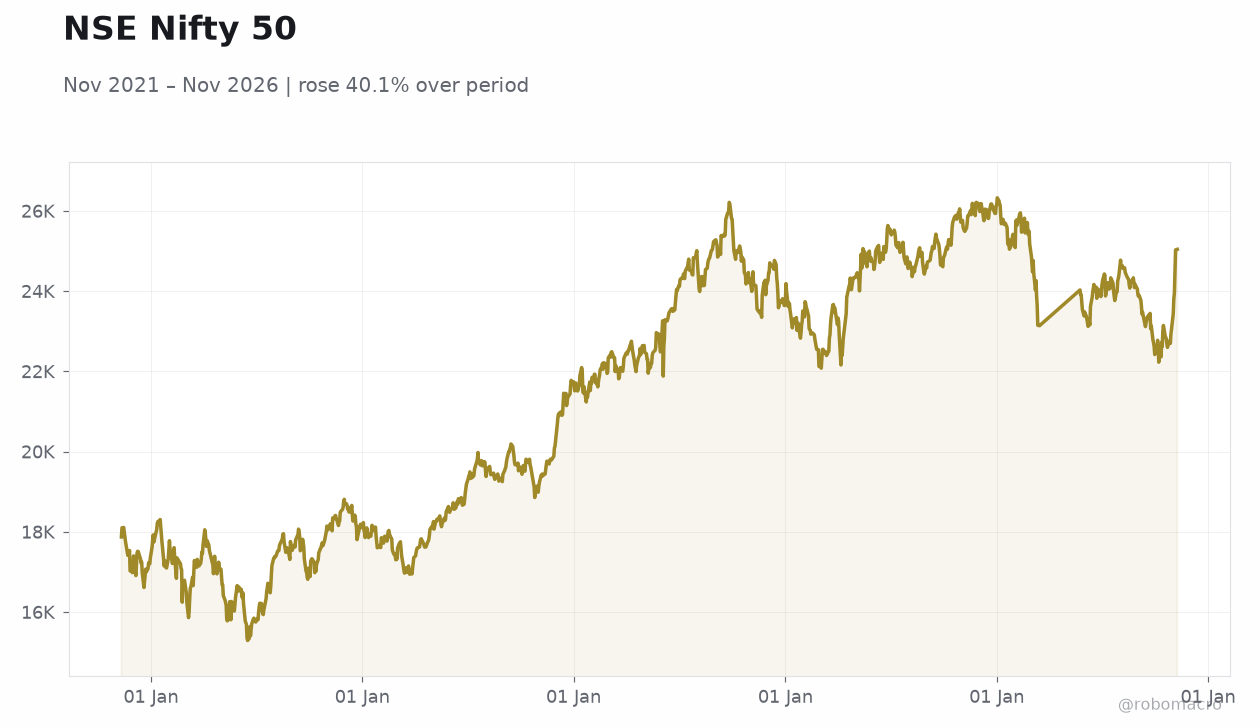 NSE Nifty 50 | Type: macro_line | NSE Nifty 50: 2.504e+04 (2026-11-09) | Range: 1.529e+04–2.633e+04 | Trend(6pt): 1.787e+04,1.811e+04,2.267e+04,2.511e+04,2.503e+04,2.504e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-12) | |||
| Inflation Rate Year-over-Year | 5.54 | 5.93 | 05:30 |
- Rupee extends rally to a seven-month high, putting RBI's dollar-buying threshold in focus as FX reserves fall $2.69bn to $717.06bn
- Sensex surges 2.17% and Nifty reclaims 25,000 as Brent crude collapses 6.01% to $92.41, easing imported inflation pressure
- October CPI due Thursday with consensus at 5.93% y/y versus 5.54% prior, a key input ahead of the December 4 MPC decision
Yesterday's Recap
Indian equities staged a sharp rally, with the Sensex surging 2.17% to 81,028.02 while the Nifty 50 edged up 0.06% to 25,044.65, reclaiming the 25,000 mark on a closing basis. The move was led by financials, with HDFC Bank jumping 3.72% to 788.25, while Reliance added 0.50% to 1,320.00. The rupee extended its rally, with USD/INR falling 0.59% to 93.90 and EUR/INR dropping 1.38% to 104.54, touching a seven-month high near 93.75 intraday amid strong foreign inflows.
Brent crude collapsed 6.01% to $92.41, a significant tailwind for India's import bill and inflation outlook. Gold rose 1.54% to $4,137.50, while Bitcoin edged up 0.51% to 74,961.93. FX reserves fell $2.69bn to $717.06bn, reflecting RBI dollar sales to manage the rupee's appreciation.
No scheduled Indian data releases printed yesterday.
The Day Ahead
The calendar is light today, with no scheduled Indian data releases. Attention turns to Thursday's October CPI print at 05:30 ET, where consensus stands at 5.93% y/y versus 5.54% prior — a notable acceleration that would keep the RBI cautious. Markets will watch whether the rupee's strength persists and whether the RBI adjusts its dollar-buying threshold, given its large forward book.
G-Sec yields were not populated in the supplied data, so bond direction will be inferred from price action and flows. Equity momentum from the Sensex rally and crude's slide will be tested against global risk sentiment.
Other Economic Notes
India Inc's overseas investments surged 41% to Rs 16.71 lakh crore, with the RBI reporting ODI growth of 40.8% in FY26 and the FDI-ODI ratio narrowing to 4.2 — a sign of growing Indian corporate global ambition. The budget is walking a tightrope on thin margins, constraining fiscal space even as growth momentum holds. The government has doubled its rice sale target to 5 million metric tonnes for FY2026-27 under the open market scheme, aimed at cooling food prices.
Forex reserves at $717.06bn remain comfortable, but the $2.69bn drawdown signals active FX management. These cross-currents — strong outbound investment, fiscal caution, and food-price management — frame the policy backdrop.