India Macro Daily(Beta Mode)
Rupee Rally Tests RBI's Resolve
Market Snapshot
| Asset | Level | Change |
|---|---|---|
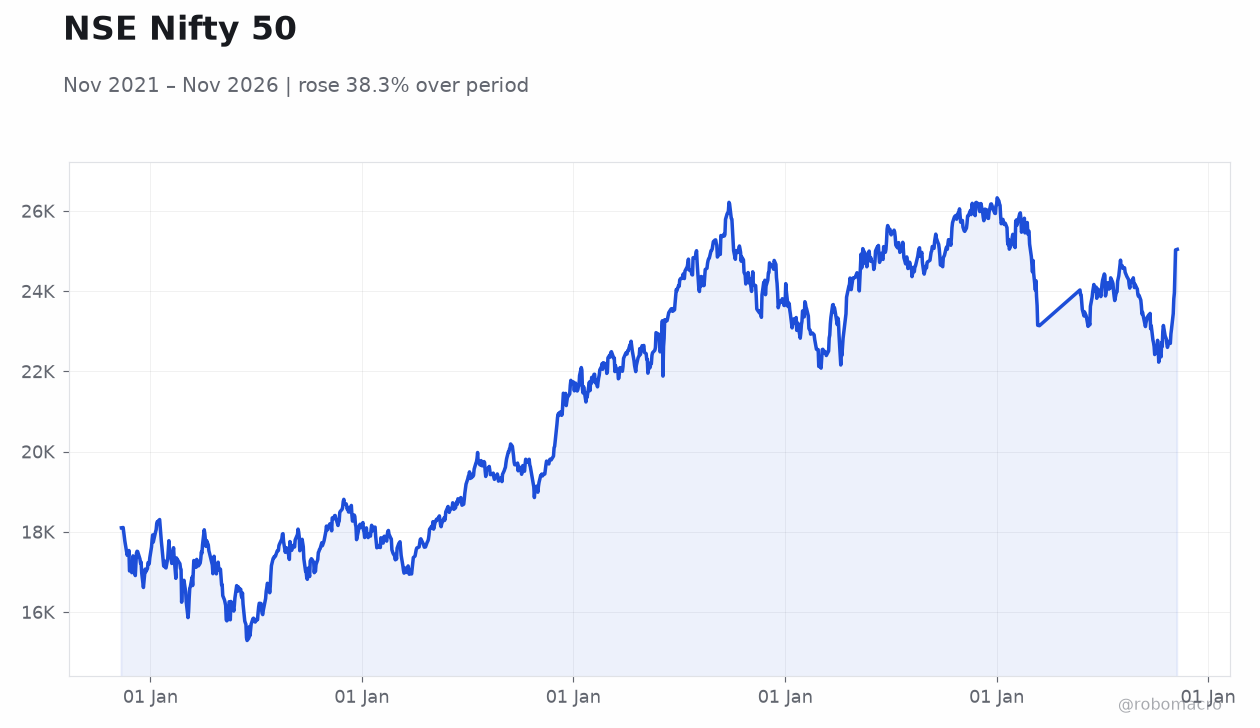
| Nifty 50 | 25,044.65 | +0.06% |
| Sensex | 81,106.65 | +0.10% |
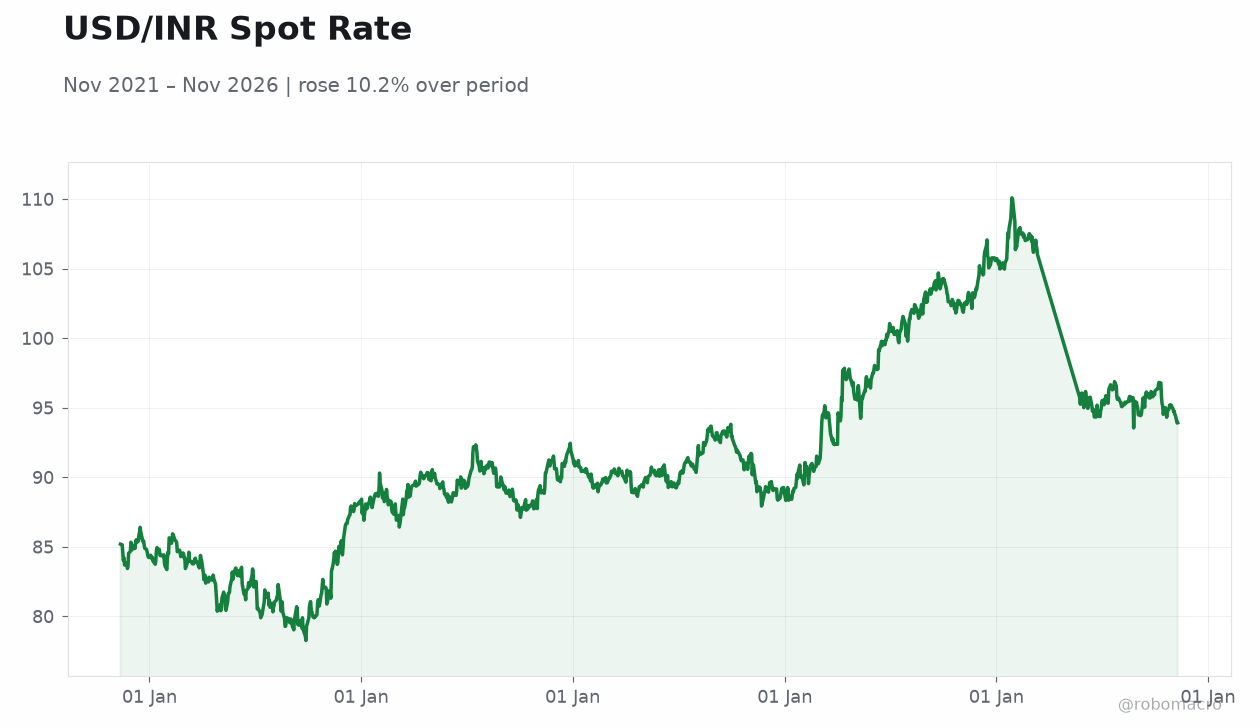
| USD/INR | 93.95 | +0.05% |
| EUR/INR | 105.33 | +0.76% |
| Reliance | 1,324.40 | +0.33% |
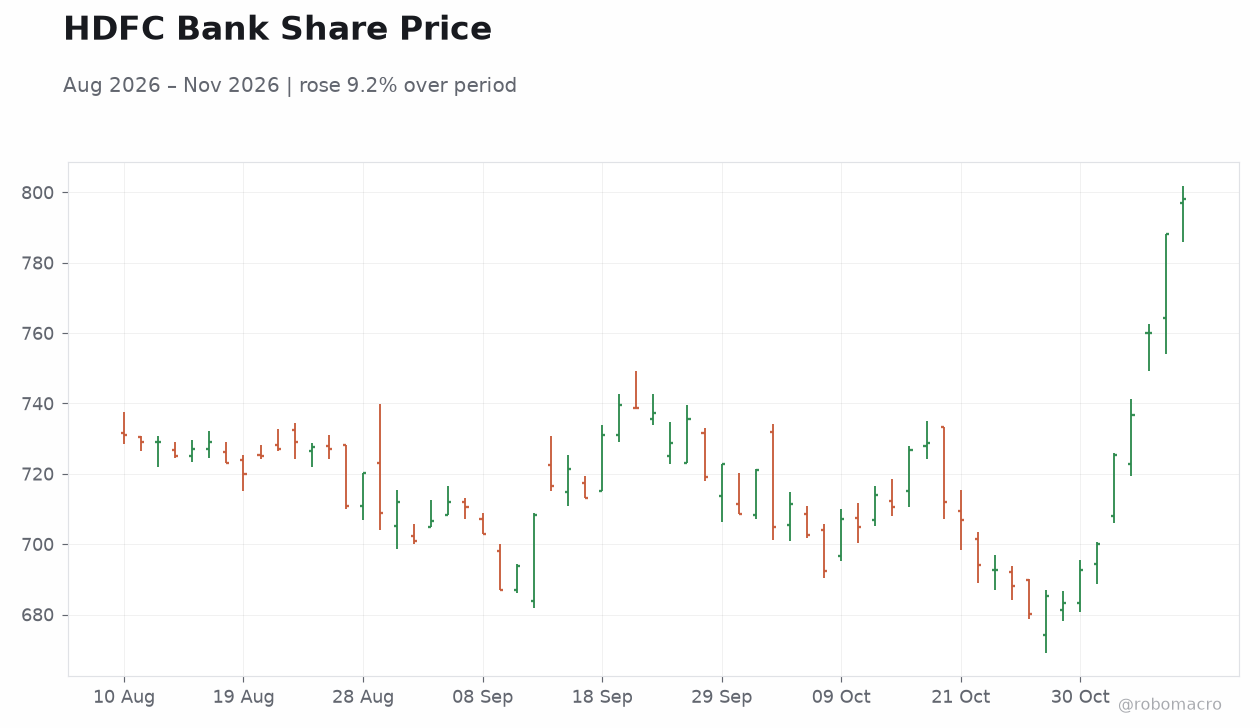
| HDFC Bank | 798.15 | +1.26% |
| Brent Crude | 91.80 | -0.83% |
| Gold | 4,048.50 | -1.60% |
| Bitcoin | 73,541.93 | -2.23% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
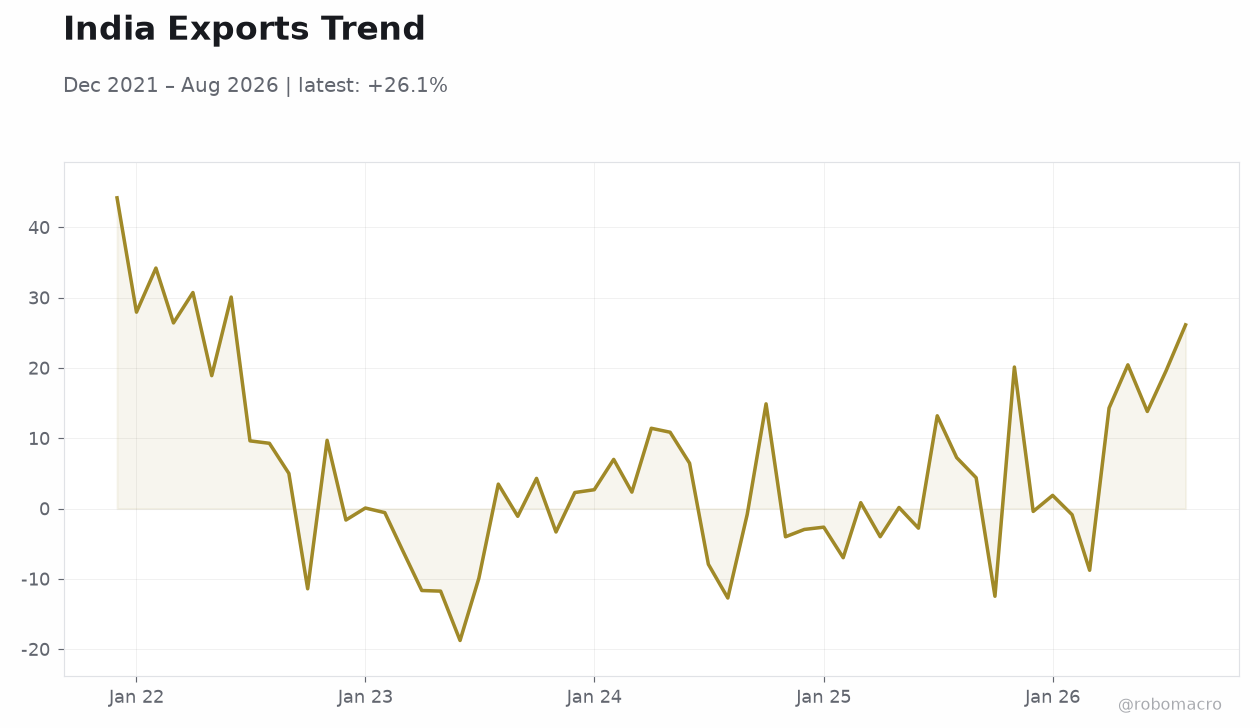 India Exports Trend | Type: macro_line | Exports (USD): 26.13 (2026-08-01) | Range: -18.76–44.2 | Trend(5pt): 44.2,-0.5764,11.42,-2.785,26.13
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-12) | |||
| Inflation Rate Year-over-Year | 5.54 | 5.93 | 05:30 |
- Rupee extends rally to seven-month high, putting RBI's dollar-buying threshold in focus
- October CPI due Thursday; consensus 5.93% vs prior 5.54%
- RBI's $239bn forward short position seen capping further rupee gains despite FPI inflows
Yesterday's Recap
Indian equities edged higher Monday, with the Nifty 50 adding 0.06% to 25,044.65 and the Sensex up 0.10% at 81,106.65, a muted session that nonetheless extended the market's sharpest rally in more than four years. HDFC Bank outperformed, gaining 1.26% to 798.15, while Reliance rose 0.33% to 1,324.40. The rupee was the session's focal point, extending its rally toward a seven-month high near 93.75/USD before state banks' dollar bids trimmed the advance, leaving USD/INR at 93.95 (+0.05%).
EUR/INR jumped 0.76% to 105.33, reflecting broad dollar softness. Brent crude slipped 0.83% to $91.80, a constructive backdrop for India's import bill, while gold fell 1.60% to $4,048.50 and Bitcoin dropped 2.23% to 73,541.93. G-Sec yields were not populated in the feed.
The Day Ahead
The calendar is light Tuesday, with no scheduled India data releases. Attention pivots to Thursday's October CPI print at 05:30 ET, where consensus of 5.93% year-over-year implies a reacceleration from the prior 5.54% reading — a print at or above consensus would complicate the RBI's recent hawkish tilt. Traders will also watch whether the rupee's rally persists and whether the RBI leans against further appreciation via dollar purchases.
With no domestic catalysts, G-Sec and equity direction will likely track global risk sentiment and crude. FPI flow data remains a key swing factor for both the currency and equities.
Other Economic Notes
India's export engine is drawing fresh scrutiny, with analysts arguing that signing free trade agreements alone will not lift outbound shipments — exporters across industrial hubs are gearing up to tap new FTA opportunities, but structural competitiveness gaps persist. Corporate earnings remain mixed: Whirlpool of India reported a 39% drop in Q2 net profit, a reminder that consumption-linked discretionary demand is uneven. The rupee's strength, if sustained, offers disinflationary relief on imported inputs but pressures IT services margins and exporter realizations.
Ten years on, demonetization's promised benefits remain contested, underscoring the durability of India's cash economy.