India Macro Daily(Beta Mode)
Inflation Test Looms as Rupee Firms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
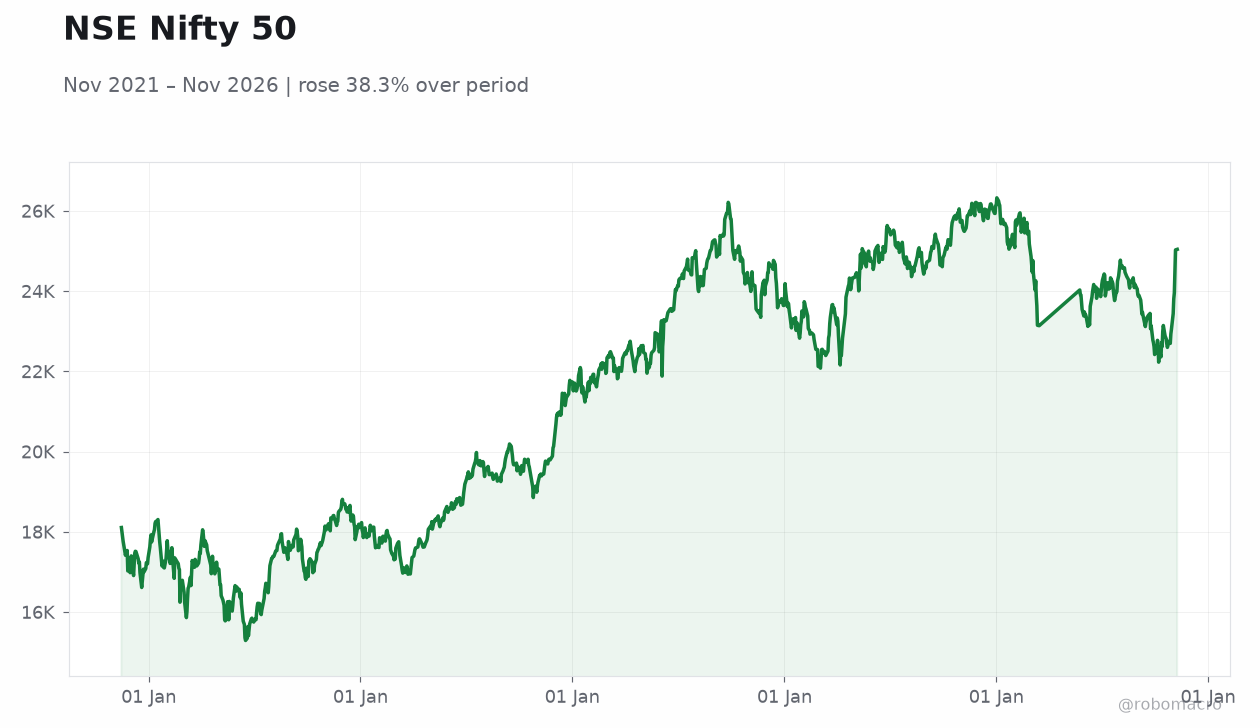
| Nifty 50 | 25,044.65 | +0.06% |
| Sensex | 81,106.65 | +0.10% |
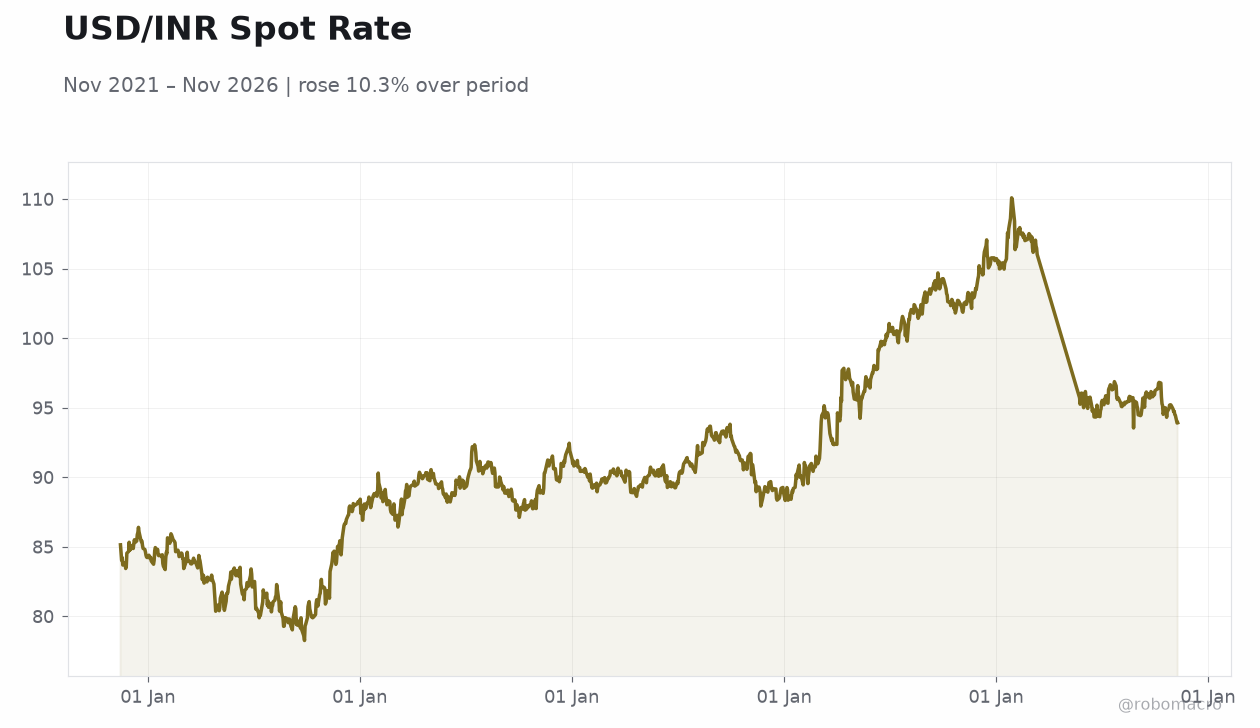
| USD/INR | 93.93 | -0.02% |
| EUR/INR | 104.82 | -0.48% |
| Reliance | 1,335.40 | +0.83% |
| HDFC Bank | 806.60 | +1.06% |
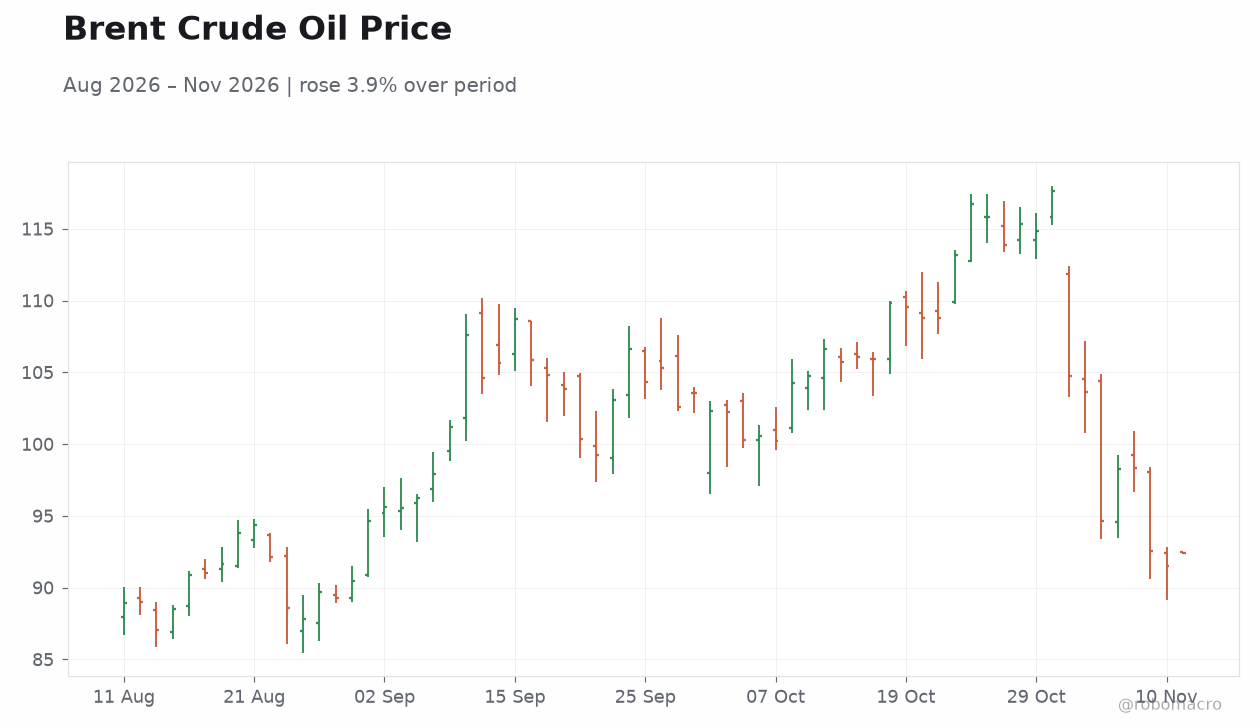
| Brent Crude | 92.40 | +0.99% |
| Gold | 3,988.40 | -1.04% |
| Bitcoin | 74,021.29 | +0.41% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
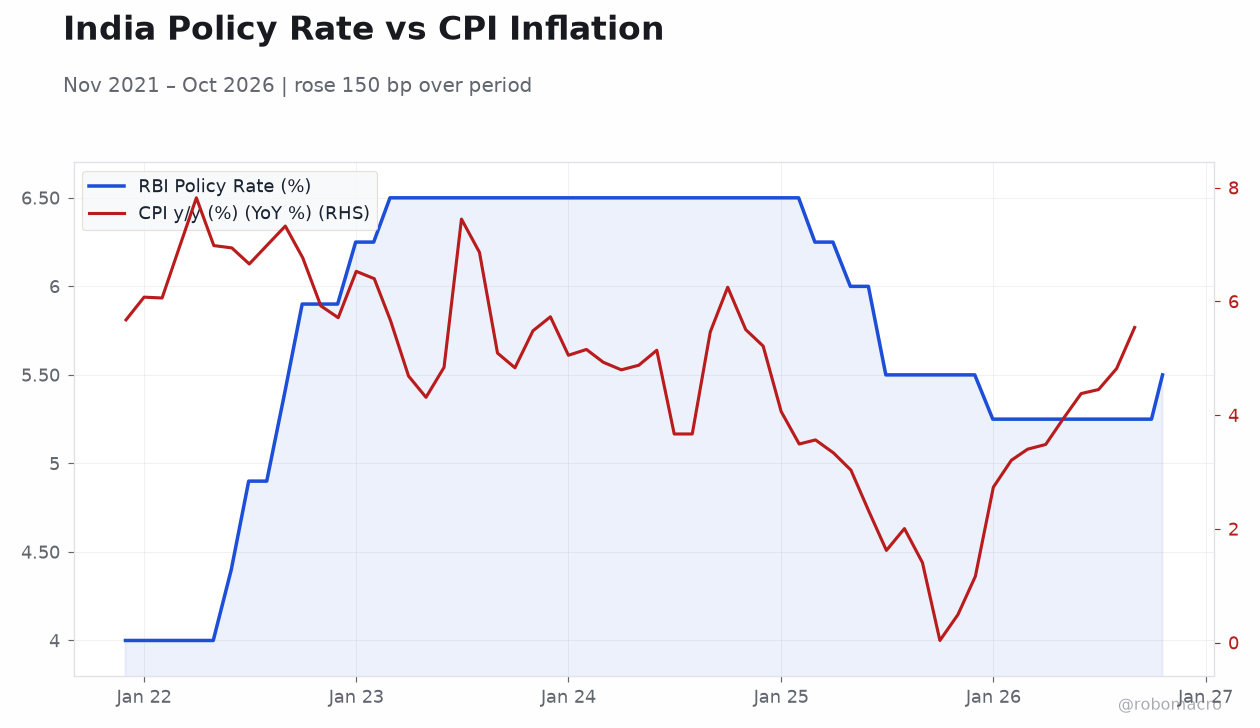
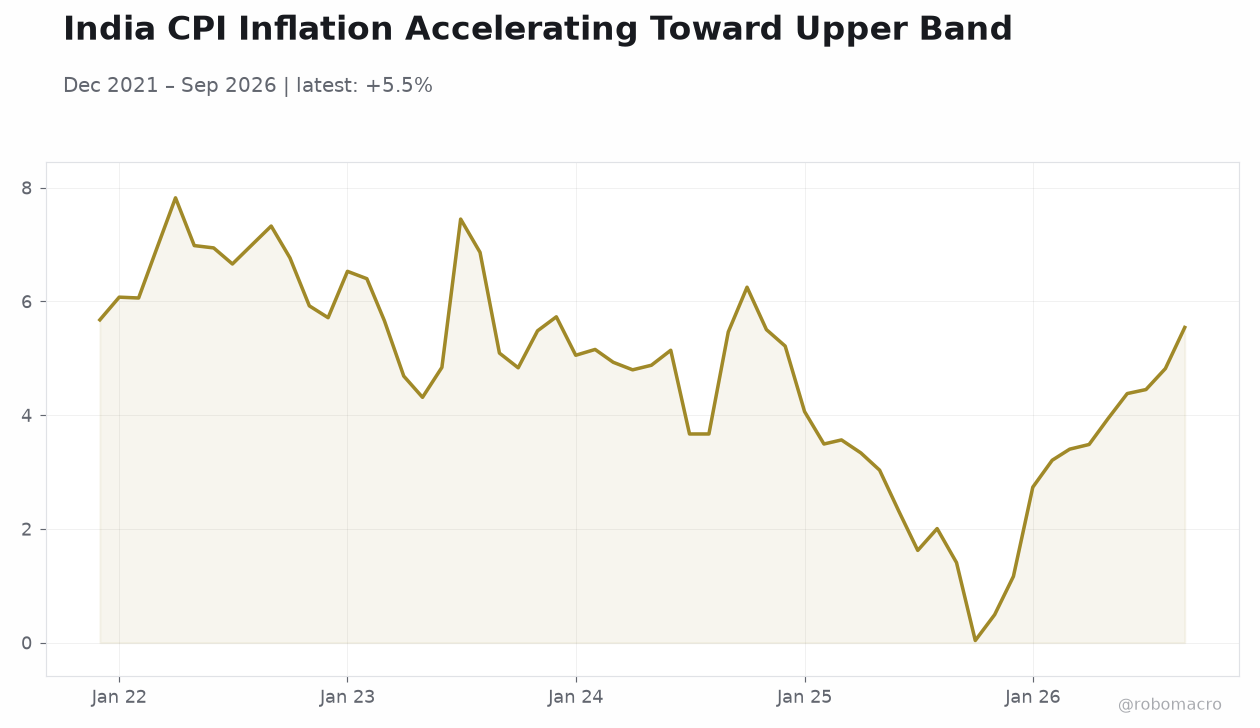 India CPI Inflation Accelerating Toward Upper Band | Type: macro_line | CPI (2015=100) YoY (%): 5.543 (2026-09-01) | Range: 0.03857–7.822 | Trend(6pt): 5.676,6.4,4.797,2.305,4.82,5.543
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-11-12) | |||
| Inflation Rate Year-over-Year | 5.54 | 5.93 | 05:30 |
- October CPI due Thursday at 05:30 ET; consensus 5.93% y/y versus 5.54% prior, a fresh acceleration toward the upper band
- Nifty and Sensex closed marginally higher; USD/INR at 93.93 with the rupee firming on FPI inflows
- RBI's $239bn forward book seen capping rupee appreciation; bond switch of INR250bn slated for next week
Yesterday's Recap
Indian equities finished near flat, with the Nifty 50 at 25,044.65 (+0.06%) and the Sensex at 81,106.65 (+0.10%), a muted session that nonetheless preserved the week's constructive tone. Bank stocks led internally — HDFC Bank rose 1.06% and Reliance 0.83% — while the broader index failed to extend gains. The rupee edged stronger, USD/INR at 93.93 (-0.02%), and EUR/INR fell 0.48% to 104.82, consistent with reports of strong FPI buying into Indian assets.
G-Sec yields were not populated in the supplied data, but news flow indicated bonds slipped as a Treasury rout abroad offset the slide in crude, implying upward pressure at the long end. Brent crude firmed 0.99% to $92.40, keeping imported inflation risk alive. Gold fell 1.04% to $3,988.40, and Bitcoin was 0.41% higher at $74,021.29.
The Day Ahead
The sole scheduled Indian release is October CPI on Thursday, 12 November, at 05:30 ET, with consensus at 5.93% y/y against a 5.54% prior print. That would mark a further climb toward the upper tolerance band and is the key input for the December 4 MPC decision. No other tier-one Indian data are scheduled for the session, so positioning will be driven by the CPI print and global rates.
Market participants will also watch for any RBI communication on liquidity and the forward book ahead of the policy meeting. Expect rupee and front-end rates to react most sharply to any surprise in the food component.
Other Economic Notes
Growth momentum remains the dominant narrative, with SBI projecting Q2 GDP growth of 7.8%, above the RBI's own estimate, and Moody's raising its FY27 forecast to 7% while expecting roughly 7% growth through 2028 on domestic demand. The Indian Express argues economic momentum has outpaced geopolitical gravity, though it cautions more remains to be done on structural reform. Kotak Neo's Anindya Banerjee frames India as in a "sweet spot" amid oil volatility and currency dynamics, with one BusinessLine view suggesting the rupee could strengthen toward 90.
Against that, VT Markets sees growth cooling to 6.7% as the RBI holds rates and winds down the FCNR(B) scheme. Ten years after demonetization, commentary remains divided on whether its promises were fulfilled.