India Macro Daily(Beta Mode)
CPI Breaches 6% as RBI Hike Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
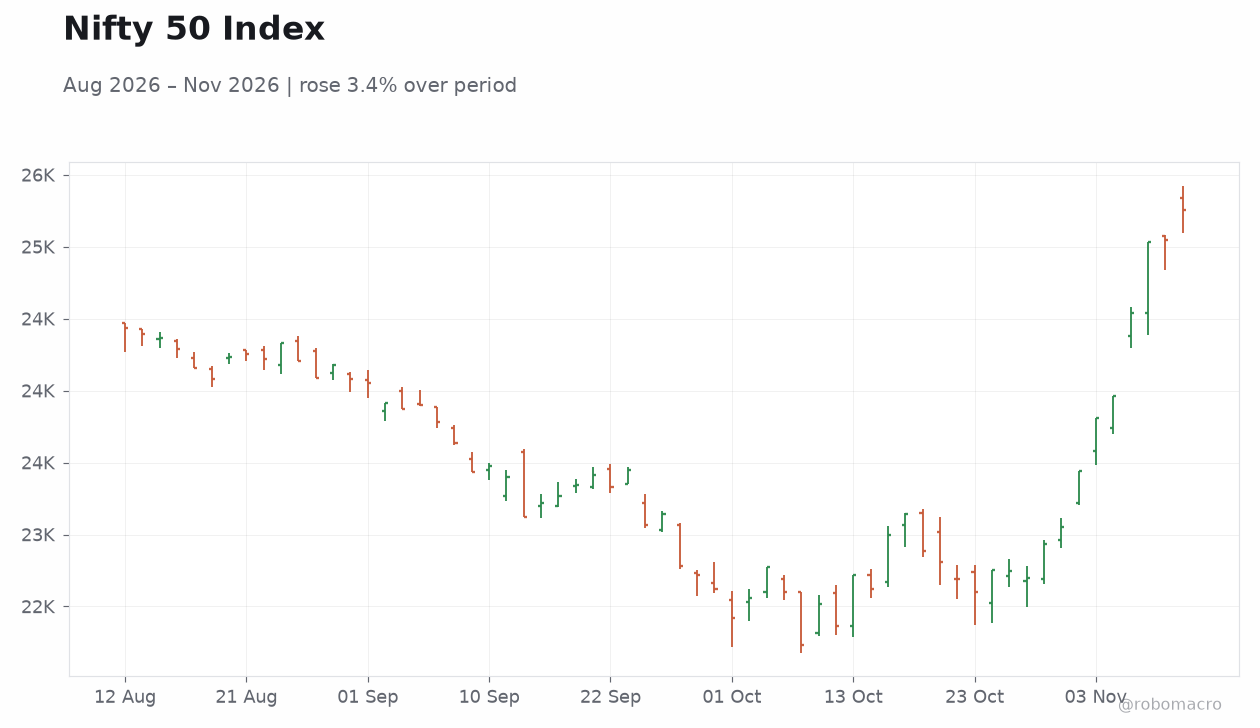
| Nifty 50 | 25,255.05 | +0.84% |
| Sensex | 81,879.40 | +0.95% |
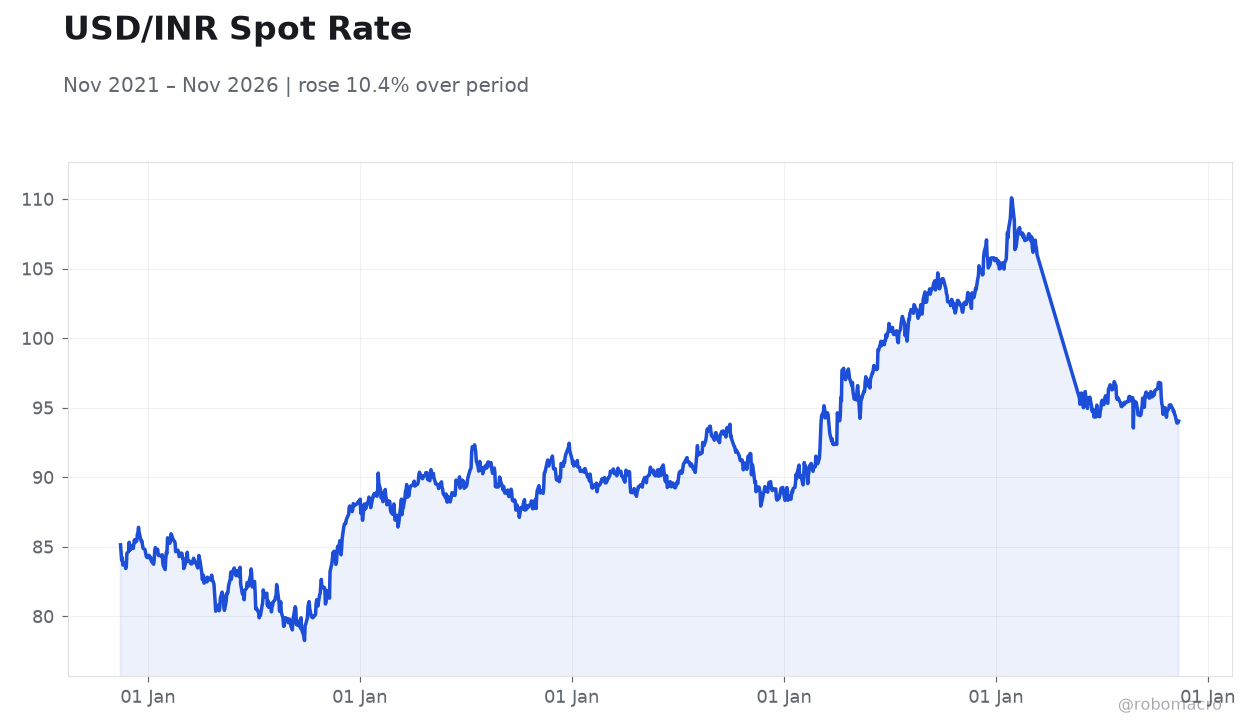
| USD/INR | 93.70 | -0.24% |
| EUR/INR | 103.88 | -0.91% |
| Reliance | 1,339.70 | +0.32% |
| HDFC Bank | 812.30 | +0.71% |
| Brent Crude | 95.88 | +3.36% |
| Gold | 3,888.90 | -2.79% |
| Bitcoin | 71,113.41 | -3.85% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 5.54 | 5.93 | 6.09 |
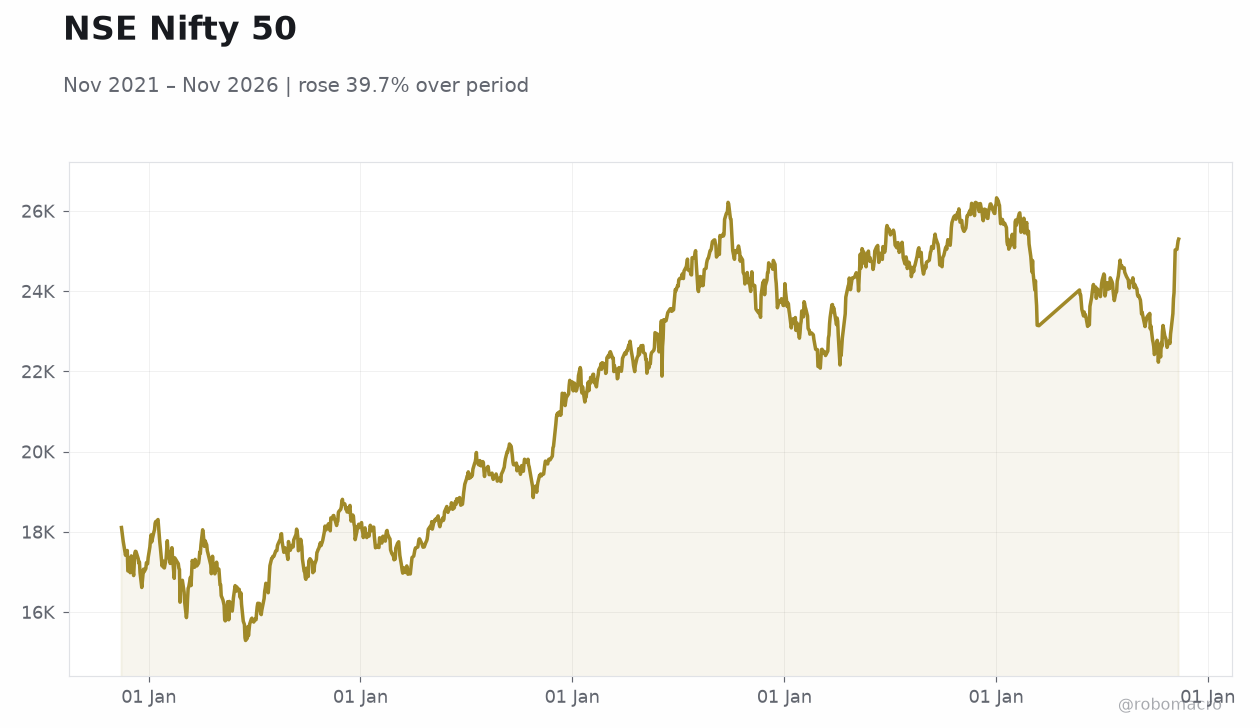 NSE Nifty 50 | Type: macro_line | NSE Nifty 50: 2.53e+04 (2026-11-12) | Range: 1.529e+04–2.633e+04 | Trend(6pt): 1.811e+04,1.812e+04,2.275e+04,2.504e+04,2.526e+04,2.53e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- October CPI inflation printed at 6.09% YoY, above the 5.93% consensus and the prior 5.54%, breaching the RBI's upper tolerance band for the first time in two years.
- Nifty 50 rose 0.84% to 25,255.05 and Sensex gained 0.95% to 81,879.40, with Bank Nifty surging 3% on strong buying and a sharp crude slide.
- USD/INR strengthened 0.24% to 93.70, but Brent crude jumped 3.36% to $95.88, complicating the disinflation outlook.
Yesterday's Recap
India's October CPI inflation printed at 6.09% YoY, overshooting both the 5.93% consensus and the prior 5.54% reading, and breaching the RBI's 6% upper tolerance limit for the first time in roughly two years. Equity markets shrugged off the upside surprise, with the Nifty 50 closing 0.84% higher at 25,255.05 and the Sensex adding 0.95% to 81,879.40, aided by reported strong FII buying and a decline in crude prices during early trade. Bank Nifty surged 3% to nearly 61,400, with BoB, PNB and Yes Bank rallying up to 6%.
The rupee firmed 0.24% to 93.70 against the dollar, while EUR/INR fell 0.91% to 103.88. G-Sec yields were not populated in the feed, but press reports indicate bonds slipped as a US Treasury rout offset the oil slide, even as short-end yields plunged ahead of the RBI review, prompting firms to rush roughly $3bn of debt issuance. Gold fell 2.79% to $3,888.90 and Bitcoin dropped 3.85% to $71,113.41.
The Day Ahead
No scheduled India data releases appear on the calendar for today or tomorrow, leaving the market to digest the October CPI overshoot and its implications for the December 4 MPC decision. Attention turns to the bond switch operation worth INR 250bn slated for next week, which will be watched for its impact on the yield curve and liquidity conditions. Corporate debt issuance momentum is likely to continue, with issuers rushing to lock in funding ahead of the RBI review as short-end yields plunge.
Traders will also monitor FII flows after the previous session's strong buying, and track crude price volatility given Brent's 3.36% jump. Rupee direction remains a key variable, with the RBI's forex curbs credited for steadying the currency and reviving investor sentiment.
Other Economic Notes
Moody's raised India's FY27 growth forecast to 7%, expecting growth of about 7% through 2028 on domestic demand and economic resilience, though economists flag building headwinds for FY28. India Inc's overseas borrowings crossed USD 7bn in September, with NaBFID raising USD 1bn, per RBI data, underscoring robust external commercial borrowing appetite. Household inflation breaking past 6% after two years has revived expectations of another RBI rate hike.
↓ p.2