India Macro Daily(Beta Mode)
RBI Tightening Path Weighs on Rupee, Equities
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 25,144.30 | -0.61% |
| Sensex | 81,592.45 | -0.39% |
| USD/INR | 94.24 | +0.22% |
| EUR/INR | 103.80 | -0.05% |
| Reliance | 1,339.70 | +0.00% |
| HDFC Bank | 804.00 | -1.02% |
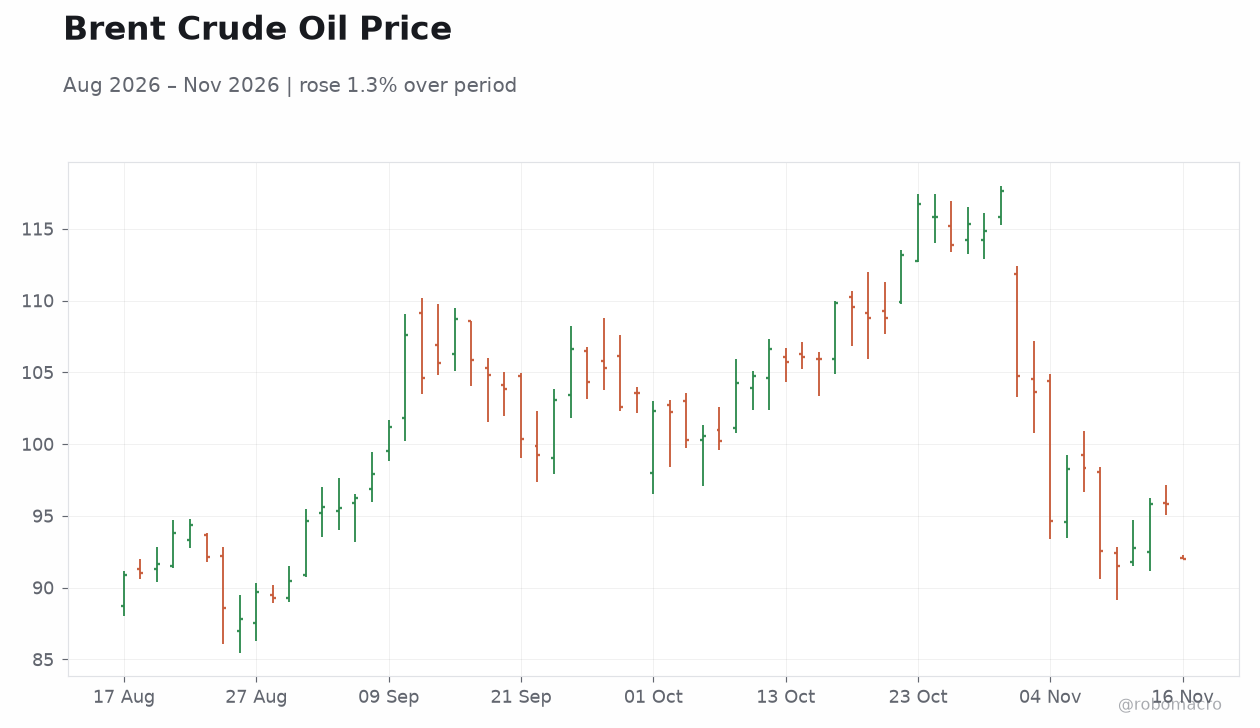
| Brent Crude | 92.01 | -4.00% |
| Gold | 3,860.70 | -0.66% |
| Bitcoin | 64,548.80 | -1.16% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
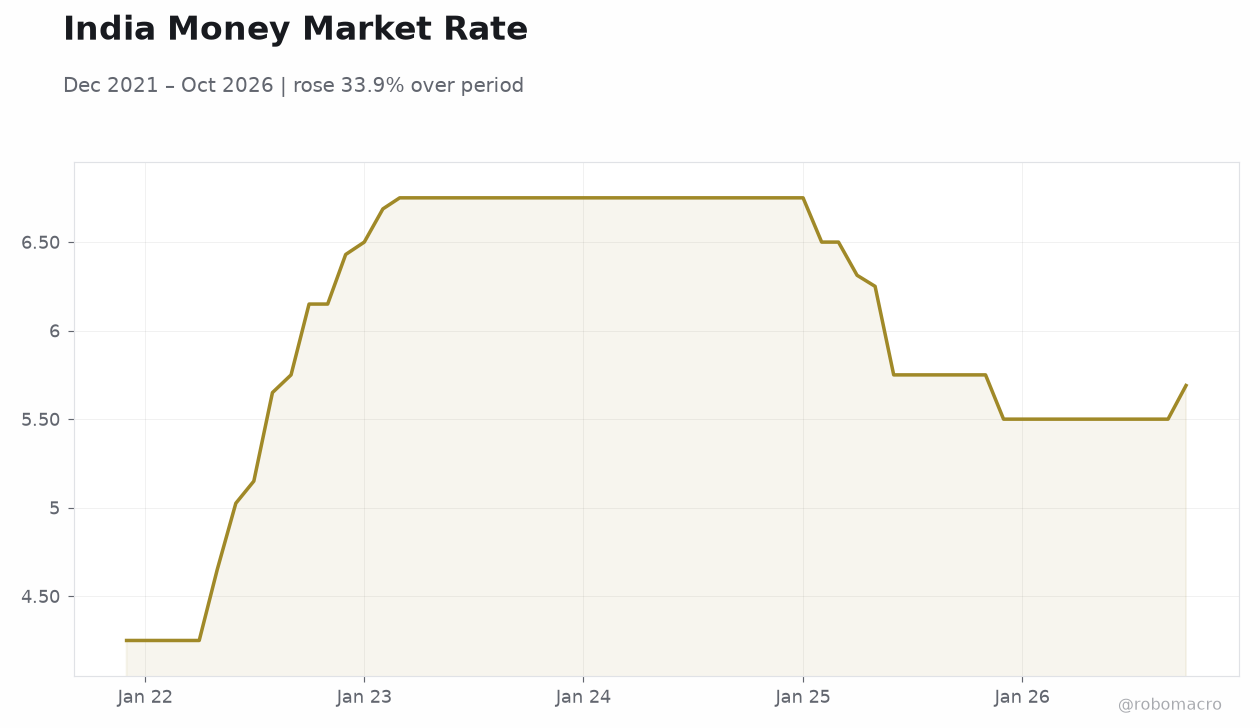 India Money Market Rate | Type: macro_line | Interbank Rate (%): 5.69 (2026-10-01) | Range: 4.25–6.75 | Trend(6pt): 4.25,6.688,6.75,5.75,5.5,5.69
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nifty 50 slips 0.61% to 25,144.30 as risk-off sentiment dominates; Sensex down 0.39% to 81,592.45
- USD/INR edges higher to 94.24 (+0.22%) amid hawkish Fed expectations and sticky domestic inflation at 6.08%
- RBI expected to maintain tightening bias through FY27 with repo at 5.50%; next MPC decision December 4
Yesterday's Recap
Indian equity markets snapped a three-day winning streak on November 15, with the Nifty 50 declining 0.61% to close at 25,144.30 and the Sensex falling 0.39% to 81,592.45. The selloff was broad-based, with HDFC Bank dropping 1.02% to 804.00, while Reliance Industries remained flat at 1,339.70. The rupee weakened modestly, with USD/INR rising 0.22% to 94.24, reflecting persistent pressure from hawkish Federal Reserve expectations and strong foreign inflows providing only partial offset.
Brent crude collapsed 4.00% to 92.01, offering some relief on the import bill, though gold slipped 0.66% to 3,860.70. Market breadth remained negative throughout the session as investors digested the implications of prolonged RBI tightening.
The Day Ahead
No major scheduled Indian data releases are on the calendar for November 16, leaving markets to trade on global cues and positioning ahead of the December 4 MPC decision. Traders will monitor rupee levels closely, with the 94.50 threshold seen as a key psychological resistance that could trigger further RBI intervention. Bond markets remain focused on liquidity conditions and the trajectory of the 10-year yield, which has been under pressure from the central bank's tightening stance.
Equity flows will be watched for signs of foreign institutional investor activity, particularly in rate-sensitive sectors like banking and real estate. The absence of domestic catalysts means global risk sentiment, particularly around U.S.-Iran tensions and Fed policy expectations, will likely drive intraday direction.
Other Economic Notes
India's growth trajectory remains a focal point, with debate intensifying over whether the economy can sustain 7-8% expansion or accelerate toward 9-10% through higher investment and regulatory certainty. CLSA has positioned India as more than just an "anti-AI" trade, suggesting structural appeal beyond defensive rotation. The country's $30 trillion dream requires patient capital and globally competitive policies, according to recent analysis.
Meanwhile, India's investments in U.S. treasuries rose $38.4 billion during June-August, reflecting continued deployment of forex reserves. The e-rupee initiative is gaining traction, with the RBI reportedly allowing wallets within banking apps to boost adoption.