India Macro Daily(Beta Mode)
Rupee Surge Tests RBI as Rate-Hike Bets Build
Market Snapshot
| Asset | Level | Change |
|---|---|---|
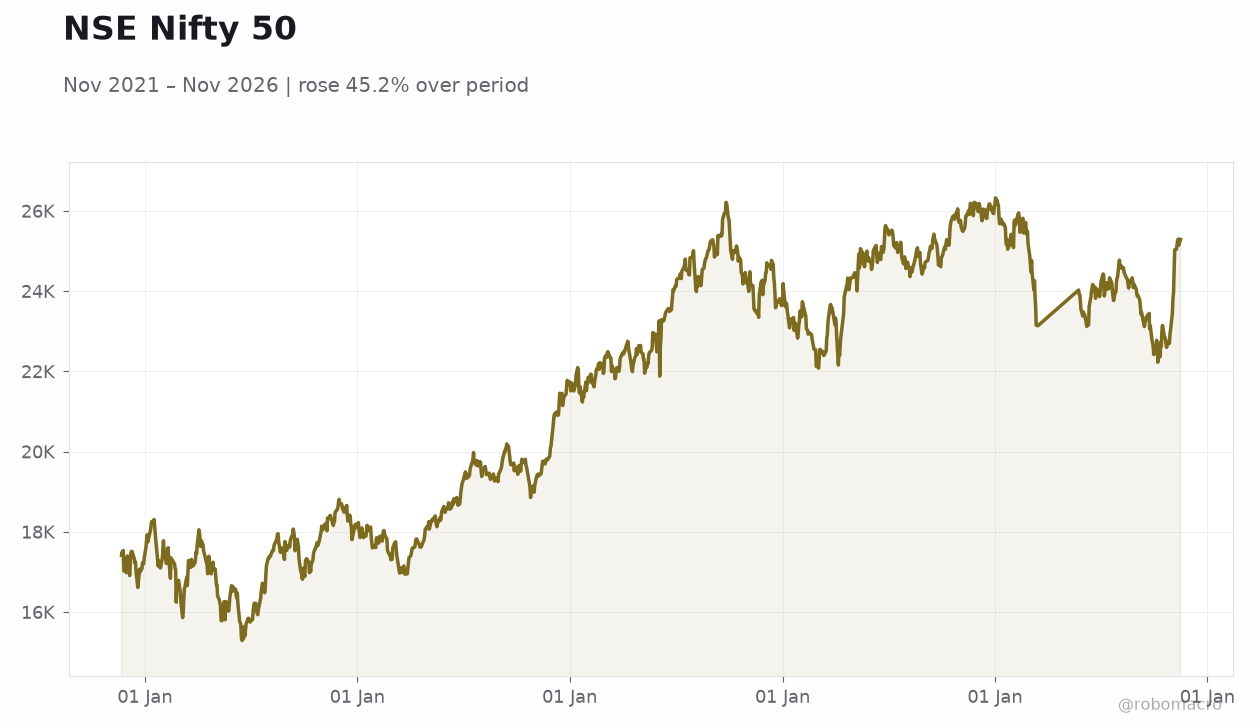
| Nifty 50 | 25,387.40 | +0.38% |
| Sensex | 82,532.19 | +0.52% |
| USD/INR | 93.47 | -0.52% |
| EUR/INR | 102.67 | -0.54% |
| Reliance | 1,363.00 | -0.29% |
| HDFC Bank | 808.15 | -0.83% |
| Brent Crude | 88.63 | -4.84% |
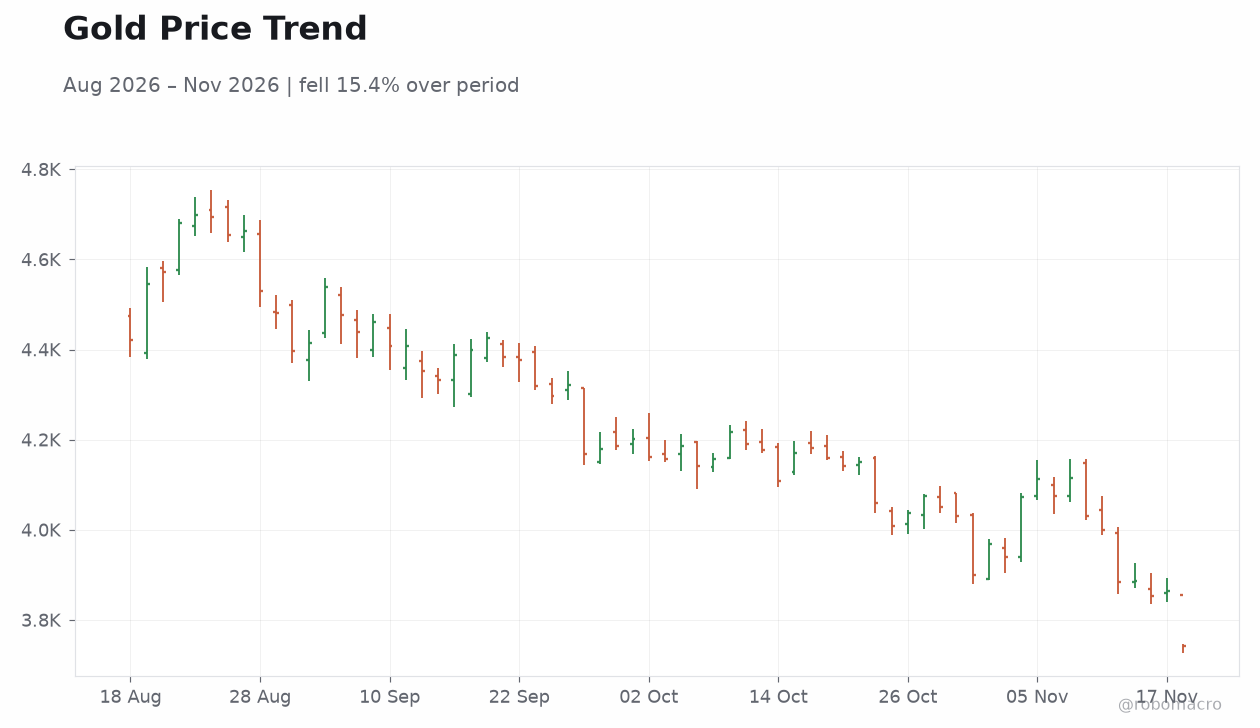
| Gold | 3,742.10 | -3.16% |
| Bitcoin | 62,771.27 | -3.27% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
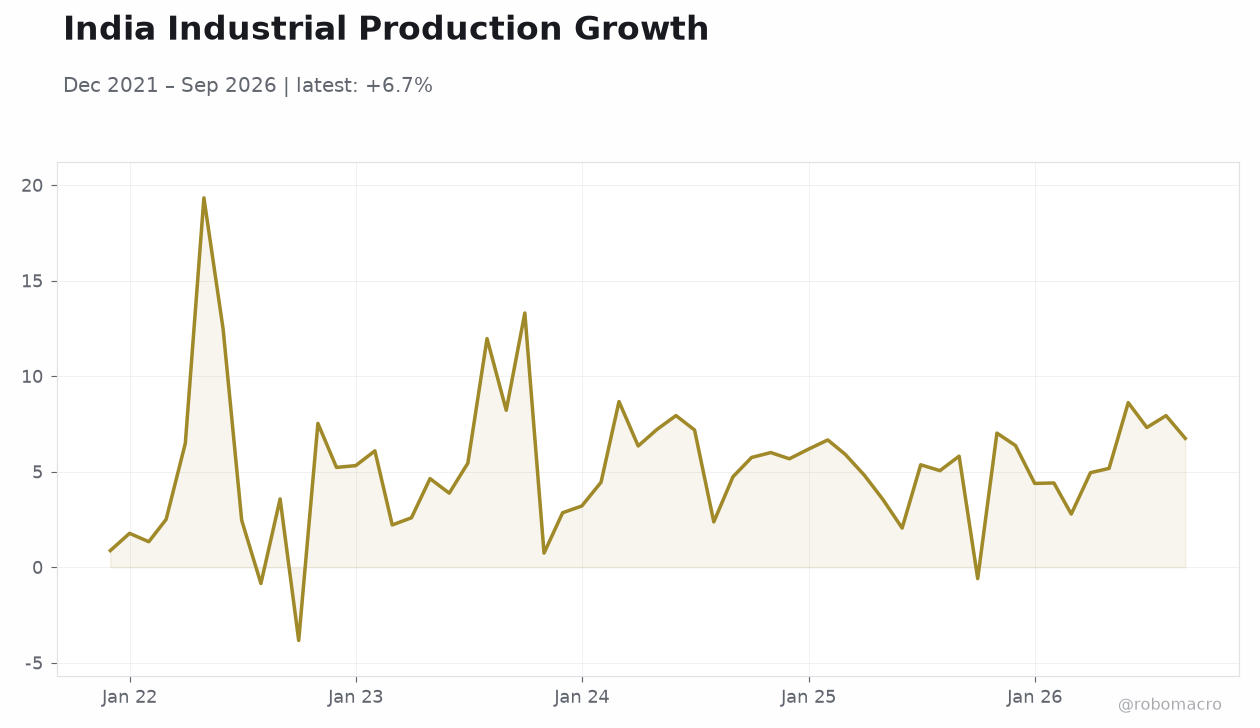 India Industrial Production Growth | Type: macro_line | Industrial production (YoY %): 6.745 (2026-09-01) | Range: -3.835–19.33 | Trend(6pt): 0.8722,6.091,6.346,2.051,7.935,6.745
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Rupee extends rally to seven-month high as AI-trade unwinding and foreign equity inflows underpin India theme; USD/INR at 93.47 (-0.52%).
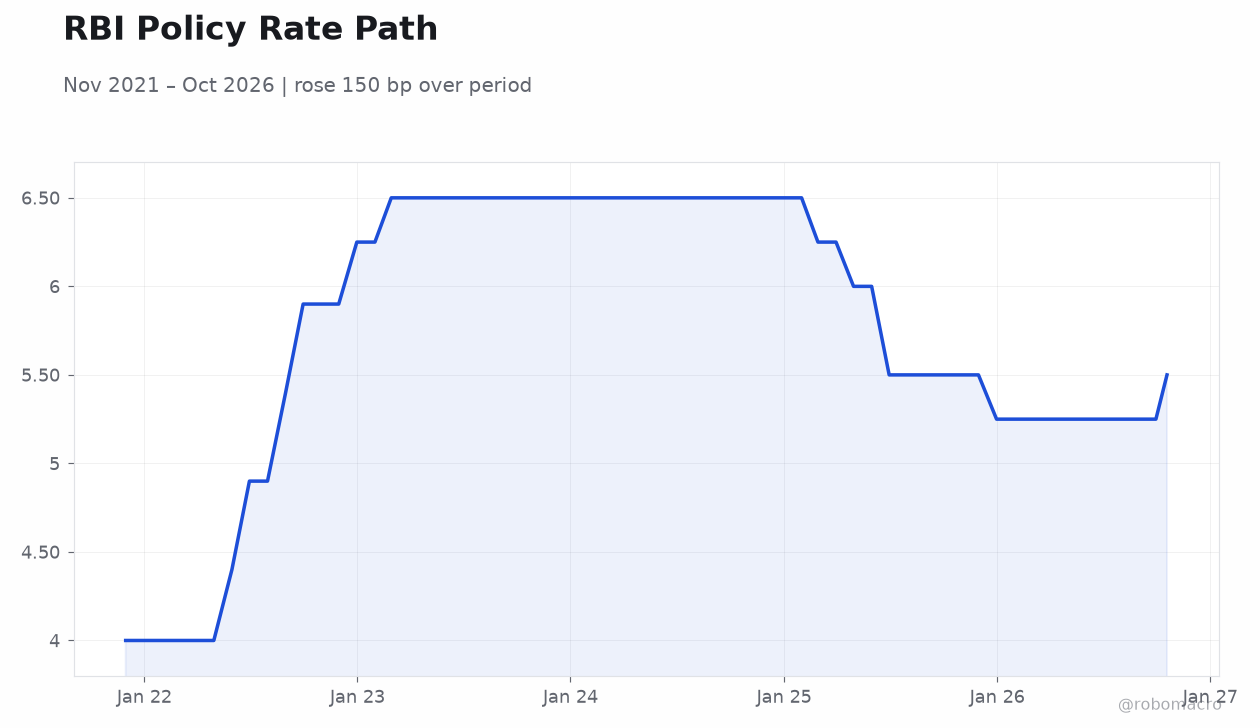
- Goldman Sachs forecasts 75bp of RBI hikes by Q2 CY27 and GDP moderating to 7.2% in CY27.
- Nifty +0.38% to 25,387, Sensex +0.52% to 82,532 as Brent collapses 4.84% to $88.63; gold -3.16%.
Yesterday's Recap
Indian equities extended gains with the Nifty 50 adding 0.38% to 25,387.40 and the Sensex rising 0.52% to 82,532.19, helped by a sharp 4.84% drop in Brent crude to $88.63 that improves India's import bill and inflation outlook. The rupee strengthened further, with USD/INR falling 0.52% to 93.47 and EUR/INR down 0.54% to 102.67, as sustained foreign inflows into Indian equities and the unwinding of crowded AI trades kept the India theme underpinned. The CEA publicly flagged rupee strength — rather than weakness — as next year's challenge, a notable shift in official framing.
Bank stocks lagged the index, with HDFC Bank down 0.83% to 808.15 and Reliance off 0.29% to 1,363.00. Gold slumped 3.16% to $3,742.10 and Bitcoin fell 3.27% to 62,771.27, signaling a broad risk-on rotation out of defensive and speculative assets. No scheduled Indian data releases printed yesterday.
The Day Ahead
The calendar is empty for November 18, leaving markets to trade off flow dynamics and global risk sentiment rather than domestic prints. With no scheduled releases, rupee direction and foreign institutional flow data will be the primary intraday drivers, alongside crude's continued slide. Traders will watch whether the Nifty can hold above 25,400 after the recent rally, with Moneycontrol flagging the question of whether Nifty and Bank Nifty need a breather.
Attention increasingly rotates toward the RBI's December 4 policy meeting, the next scheduled event risk for rates. Global cues — particularly US yields and AI-linked equity positioning — will transmit directly into Indian risk assets given the thin domestic calendar.
Other Economic Notes
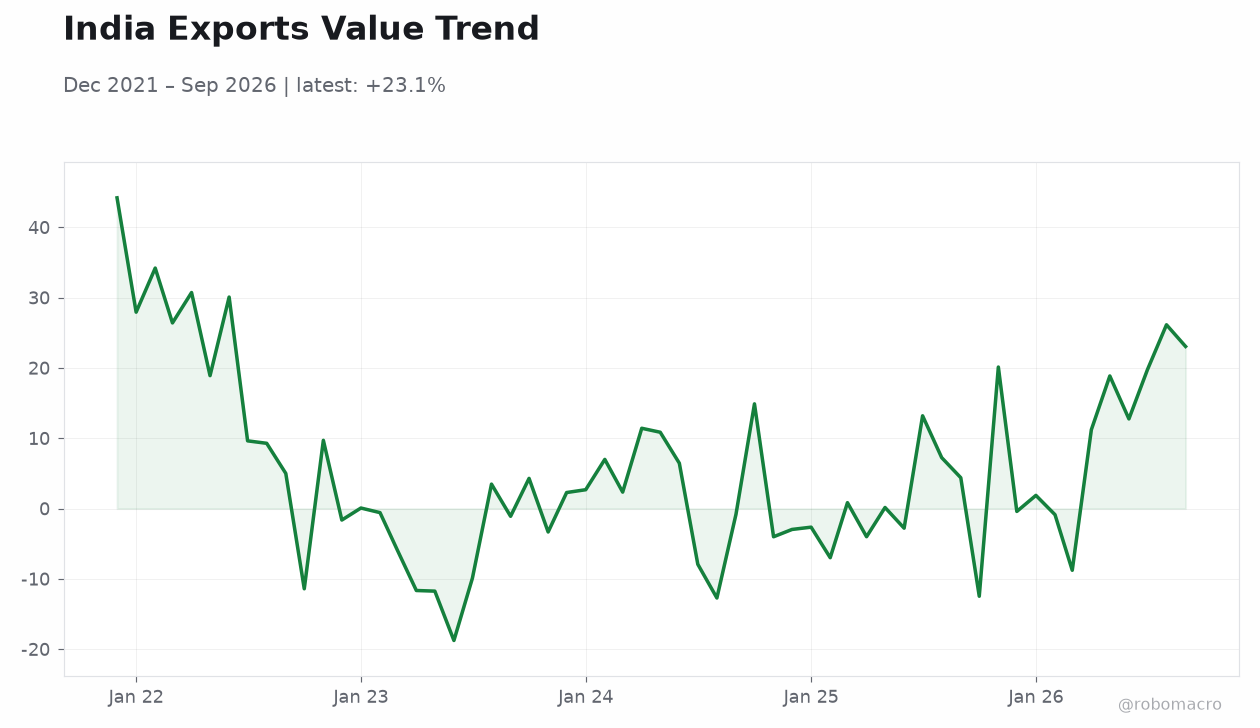
India's edible oil import mix is shifting, with soybean oil at 5.83 million tonnes of a total 16.92 million tonnes in 2025-26, a composition change worth monitoring for food inflation pass-through. CPI at 6.08% (October 2026) remains above the RBI's tolerance band, keeping the inflation-targeting framework under strain and complicating the rate outlook. The rupee's strength, while flattering for import costs, raises competitiveness concerns for exporters — the CEA's warning signals official unease with one-way appreciation.
↓ p.2