India Macro Daily(Beta Mode)
Rupee Surges, RBI Seen Turning Hawkish
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nifty 50 | 25,227.95 | -0.63% |
| Sensex | 82,031.81 | -0.61% |
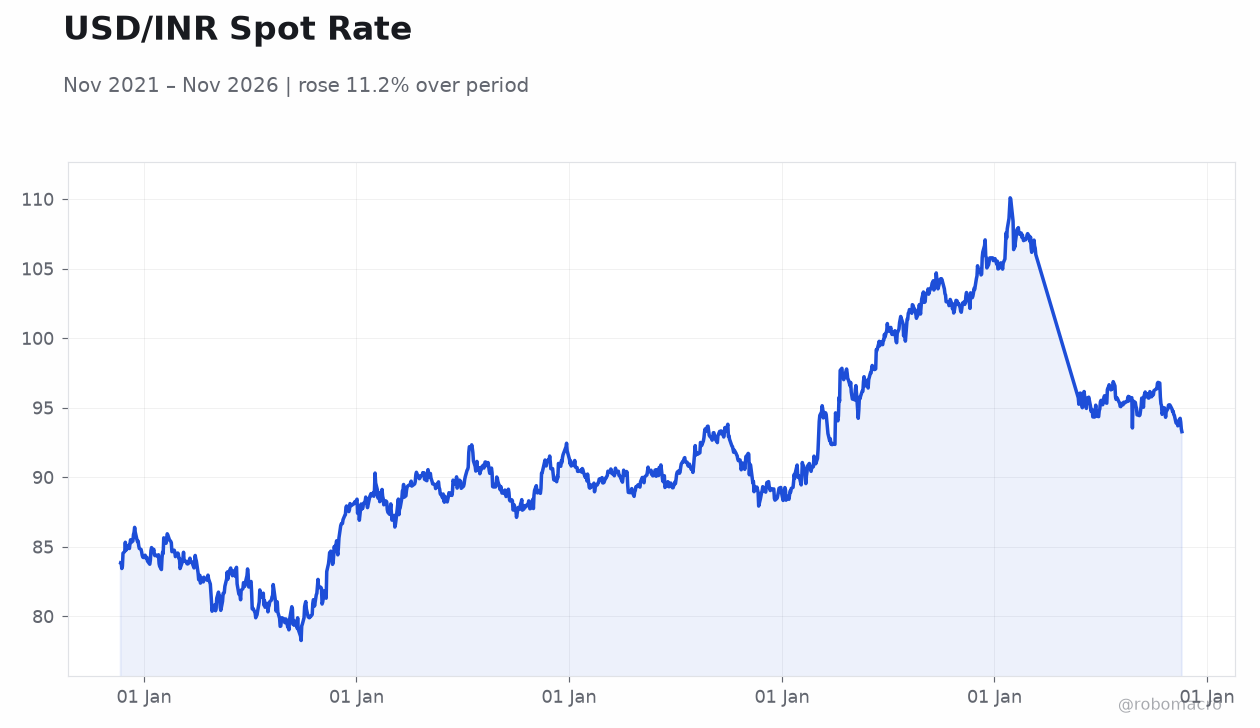
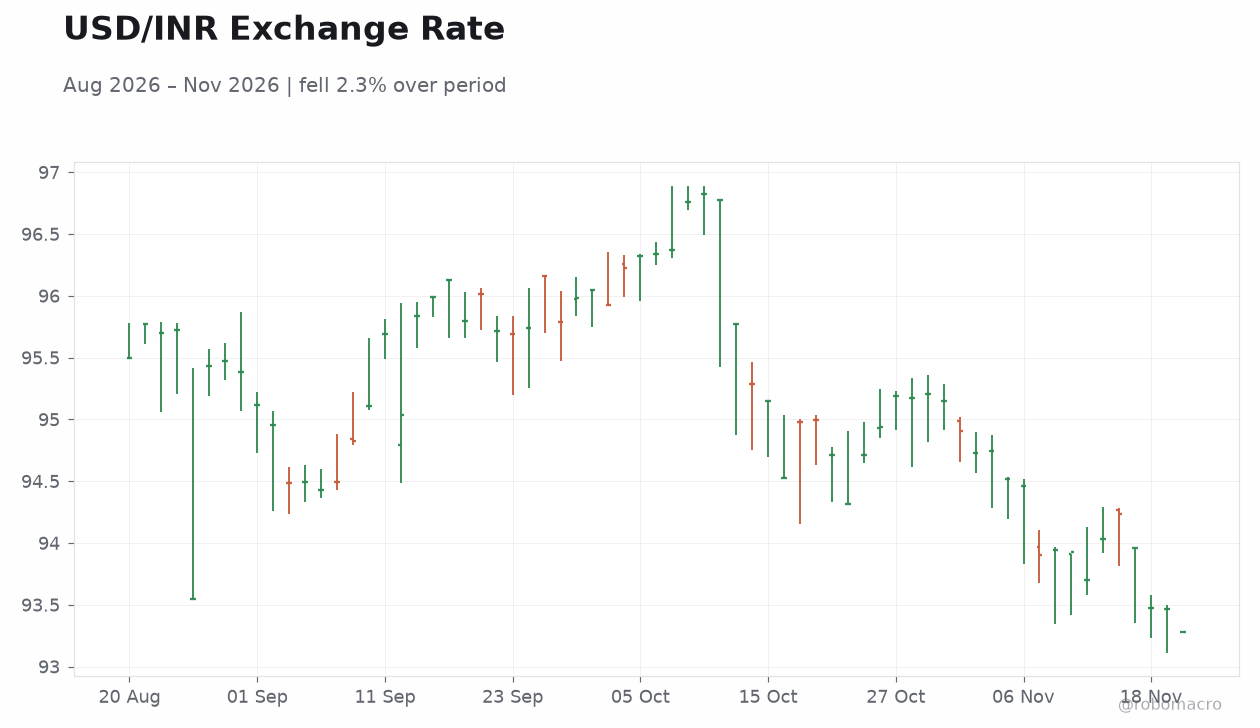
| USD/INR | 93.28 | -0.20% |
| EUR/INR | 102.39 | -0.08% |
| Reliance | 1,375.60 | +0.92% |
| HDFC Bank | 821.80 | +1.69% |
| Brent Crude | 89.89 | -2.24% |
| Gold | 3,624.80 | -3.13% |
| Bitcoin | 61,979.21 | -1.60% |
| India 2Y Govt Yield | - | - |
| India 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
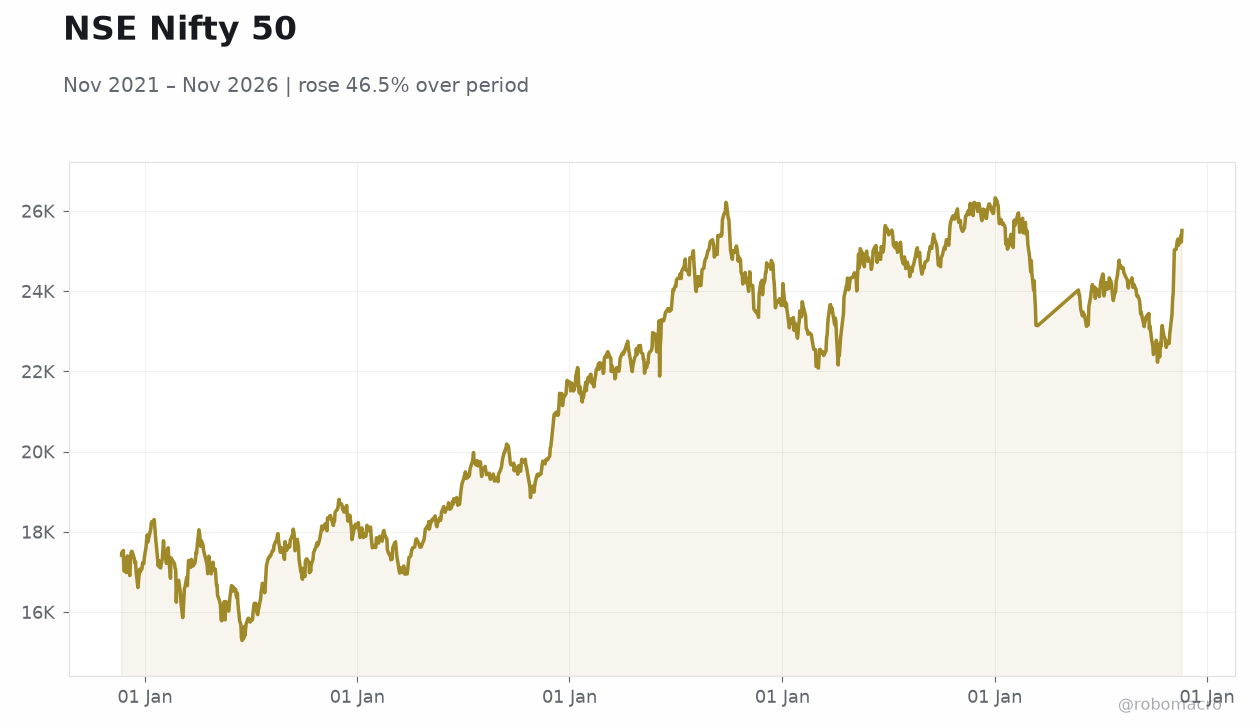 NSE Nifty 50 | Type: macro_line | NSE Nifty 50: 2.551e+04 (2026-11-19) | Range: 1.529e+04–2.633e+04 | Trend(6pt): 1.742e+04,1.765e+04,2.2e+04,2.552e+04,2.539e+04,2.551e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Rupee hits seven-month high as foreign inflows return and AI-trade unwinding supports India positioning
- October CPI at 6.08% breaches RBI's upper tolerance band, prompting Goldman Sachs to forecast 75bp of hikes by Q2 2027
- Equities slip with Nifty down 0.63% to 25,227.95 while Brent crude drops 2.24% to $89.89
Yesterday's Recap
Indian equities closed lower with the Nifty 50 falling 0.63% to 25,227.95 and the Sensex shedding 0.61% to 82,031.81, though both indices recovered sharply from intraday lows. The rupee strengthened 0.20% against the dollar to 93.28, touching a seven-month high as Societe Generale flagged "three powerful tailwinds" supporting the currency. G-Sec yields ended a choppy session little changed as traders awaited fresh cues on the interest rate trajectory.
HDFC Bank outperformed with a 1.69% gain while Reliance added 0.92%, bucking the broader weakness. Brent crude slid 2.24% to $89.89, offering marginal relief on the import bill. Gold tumbled 3.13% to $3,624.80 amid a broader commodities selloff.
The Day Ahead
No major scheduled Indian data releases are on the calendar for today, leaving markets to trade on global cues and positioning ahead of the December 4 MPC decision. Bond traders will continue monitoring foreign portfolio flows after reports that overseas investors are flocking back to Indian assets, allowing the RBI to pare its FX market footprint. Equity markets will watch for follow-through in banking stocks after HDFC Bank's outperformance and assess whether the recent rally in Nifty and Bank Nifty can sustain.
Rupee direction remains tied to the AI-trade unwinding theme that has underpinned India positioning. Oil's decline below $90 will be watched for pass-through implications on the import-sensitive inflation outlook.
Other Economic Notes
October CPI at 6.08% YoY has pushed inflation above the RBI's upper tolerance limit, complicating the policy path after the October 7 rate hike to 5.50%. Domestic savings are increasingly cited as an unheralded growth source, with opinion pieces highlighting household financial flows as a structural buffer. Edible oil import dynamics show soybean oil at 5.83 million tonnes out of 16.92 million tonnes total in 2025-26, a shift in the import mix with implications for the food inflation basket.
Foreign inflows into Indian assets are providing the RBI room to reduce FX intervention, a sign of improving external balance dynamics.