Japan Macro Daily(Beta Mode)
BoJ Hike Looms as Trade Data Approaches
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 64,011.34 | -1.93% |
| USD/JPY | 154.32 | +0.59% |
| EUR/JPY | 178.10 | +0.13% |
| GBP/JPY | 208.38 | -0.14% |
| Gold | 4,337.90 | -1.61% |
| Brent Crude | 106.22 | +1.54% |
| Bitcoin | 79,039.44 | +2.86% |
| Japan 2Y Govt Yield | 0.84% | +15.68% |
| Japan 10Y Govt Yield | 2.67% | +0.75% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
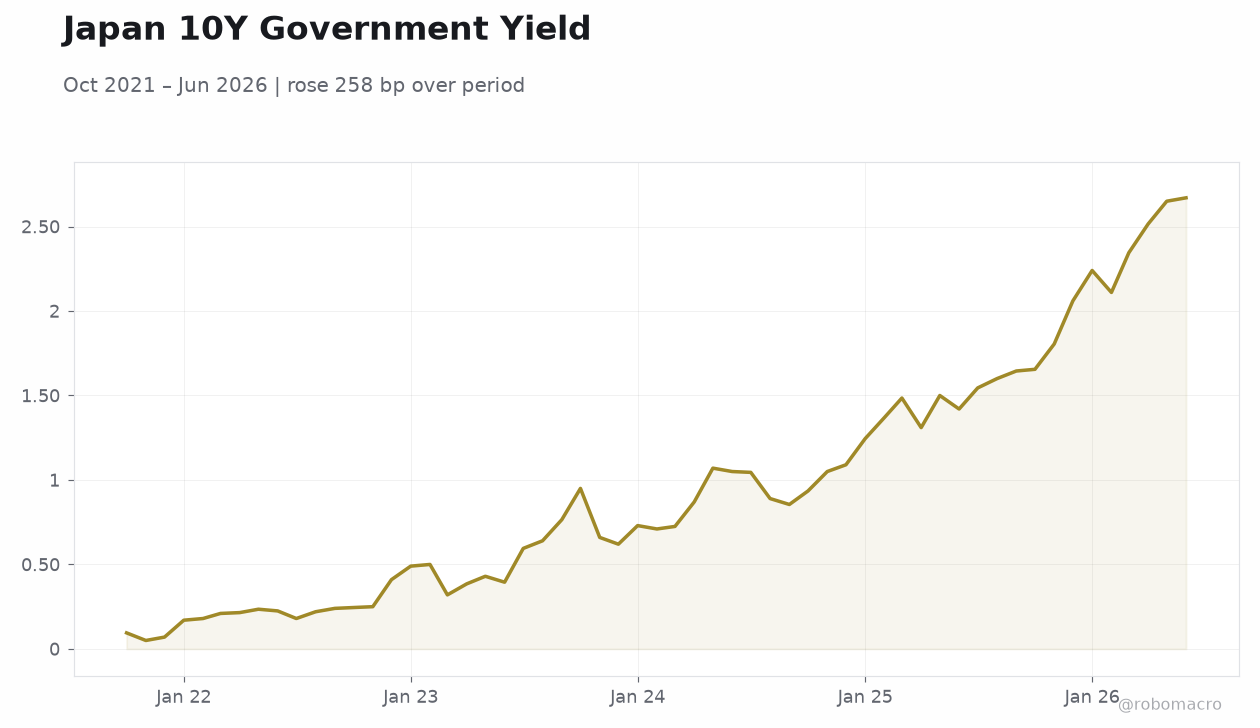 Japan 10Y Government Yield | Type: macro_line | Yield %: 2.67 (2026-06-01) | Range: 0.05–2.67 | Trend(5pt): 0.095,0.41,0.71,1.31,2.67
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-09-15) | |||
| Trade Balance | -634,500m | -1,052,600m | 19:50 |
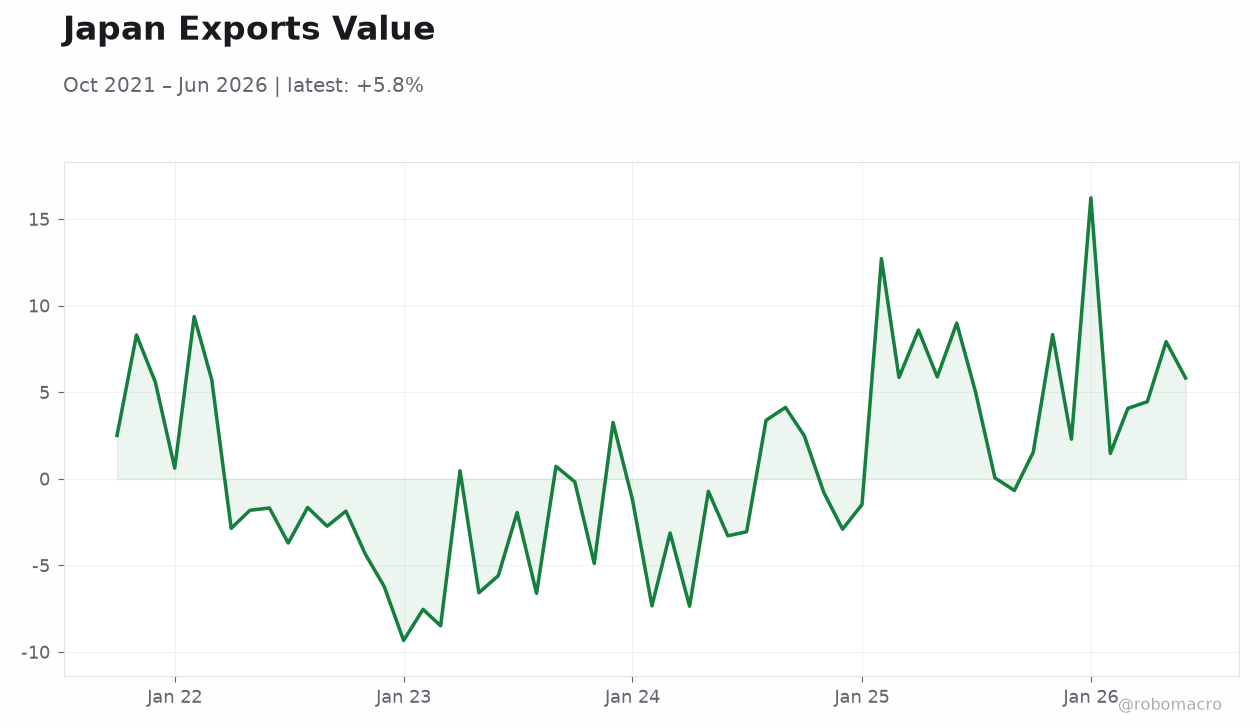
| Exports Year-over-Year | 23.20 | 18.20 | 19:50 |
| Machinery Orders Month-over-Month | 9.70 | -2.80 | 19:50 |
| Machinery Orders Year-over-Year | 16.90 | 15.30 | 19:50 |
| Thursday (2026-09-17) | |||
| Inflation Rate Year-over-Year | 2 | - | 19:30 |
| Core Inflation Rate Year-over-Year | 1.80 | 1.80 | 19:30 |
| Friday (2026-09-18) | |||
| BoJ Interest Rate Decision | 1 | 1.25 | 23:00 |
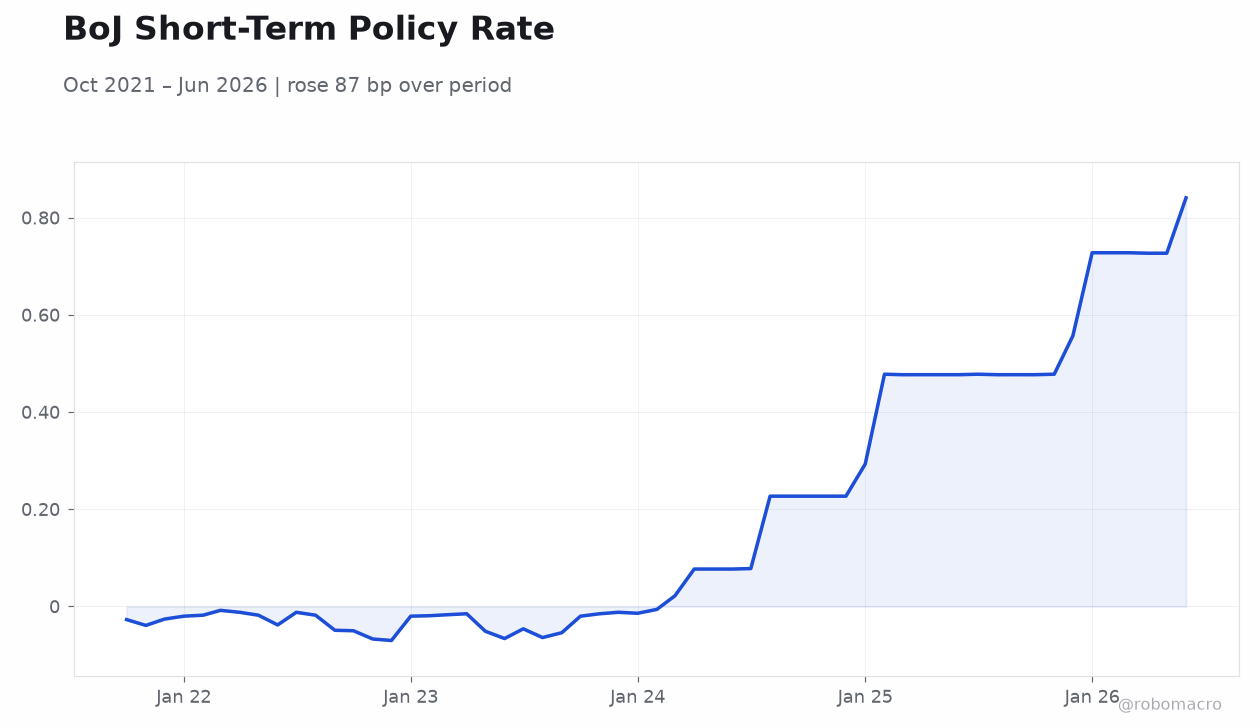
- Markets price 25 bp BoJ rate increase to 1.25% at the September 17 meeting.
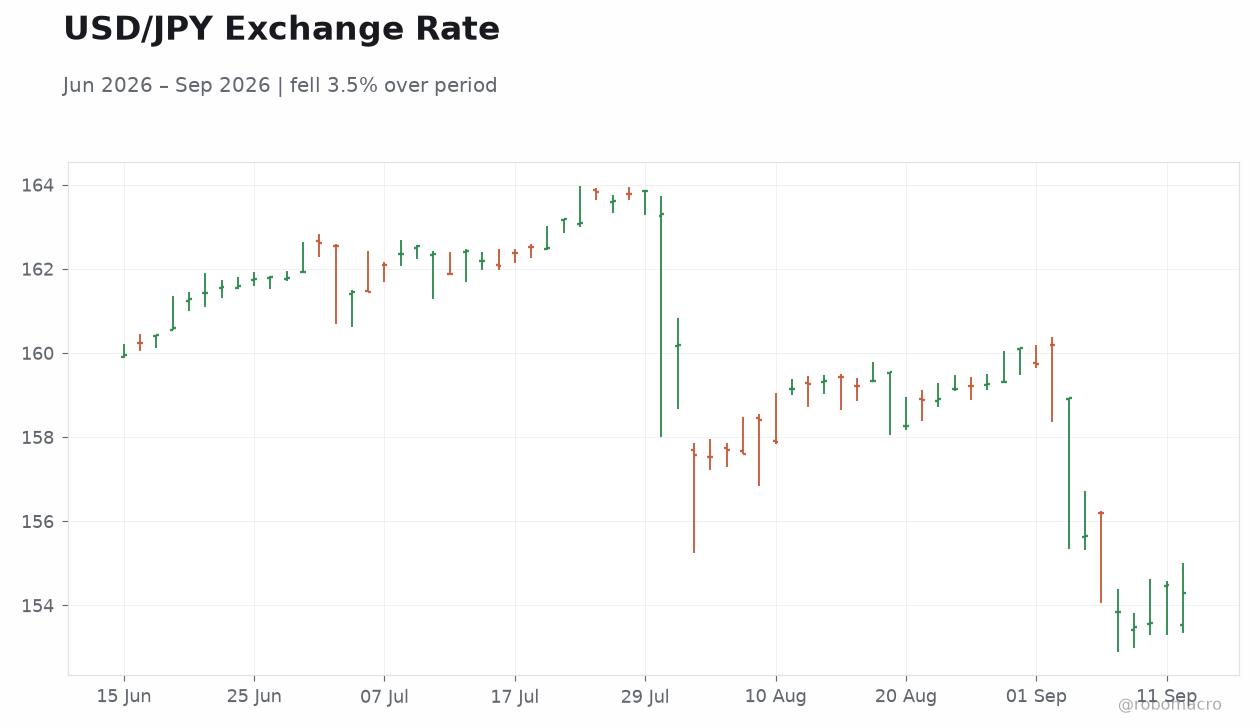
- Nikkei 225 falls 1.93% to 64,011.34 while USD/JPY rises 0.59% to 154.32.
- Japan 10Y JGB yield stands at 2.99% with producer prices supporting further tightening.
Yesterday's Recap
No economic releases occurred on September 13. The Nikkei 225 closed down 1.93% at 64,011.34 as investors positioned ahead of the BoJ decision. USD/JPY advanced 0.59% to 154.32 while EUR/JPY gained 0.13% to 178.10.
The Japan 2-year government yield jumped 15.68% to 0.84% and the 10-year yield stood at 2.99%. Brent crude gained 1.54% to 106.22 and gold declined 1.61% to 4,337.90. Bitcoin rose 2.86% to 79,039.44.
Coverage focused on elevated producer prices and the upcoming rate decision without any BoJ speakers appearing. Yen underperformance reflected positioning ahead of the policy meeting rather than any fundamental shift.
The Day Ahead
Trade Balance, Exports Year-over-Year, and Machinery Orders figures release on September 15 and will clarify external demand trends. Consensus points to a Trade Balance of -1,052.6 billion yen and Exports growth of 18.2%. Machinery Orders Month-over-Month are expected to contract 2.8%.
Inflation data and the BoJ Interest Rate Decision follow on September 17 with the policy rate consensus at 1.25%. Markets will scrutinise the BoJ’s updated outlook for guidance on the pace of normalisation. These releases arrive alongside the Fed meeting, heightening focus on cross-border capital flows and yen carry trade dynamics.
Other Economic Notes
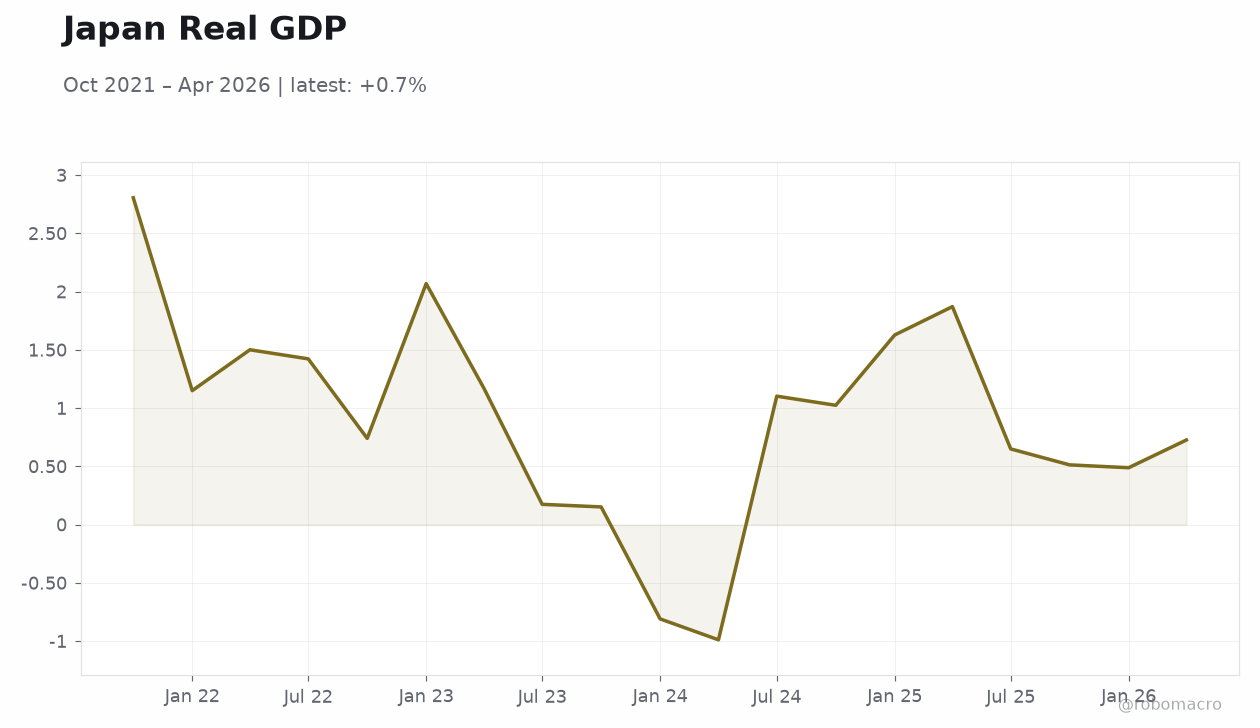
Producer price gains remain elevated and continue to back further BoJ tightening. Japan CPI YoY stands at 1.90% as of July 31, keeping real rates negative despite the expected hike. Capital spending indicators from machinery orders will test whether domestic demand can offset external weakness.
Yen underperformance into the meeting reflects positioning rather than a shift in fundamentals. Broader commentary highlights a policy-regime shift that could support the currency once the rate path clarifies. Supply-driven inflation pressures noted by officials add justification for the move.