Japan Macro Daily(Beta Mode)
BoJ Hike Looms as Yen Weakens Ahead of Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 63,492.99 | -0.81% |
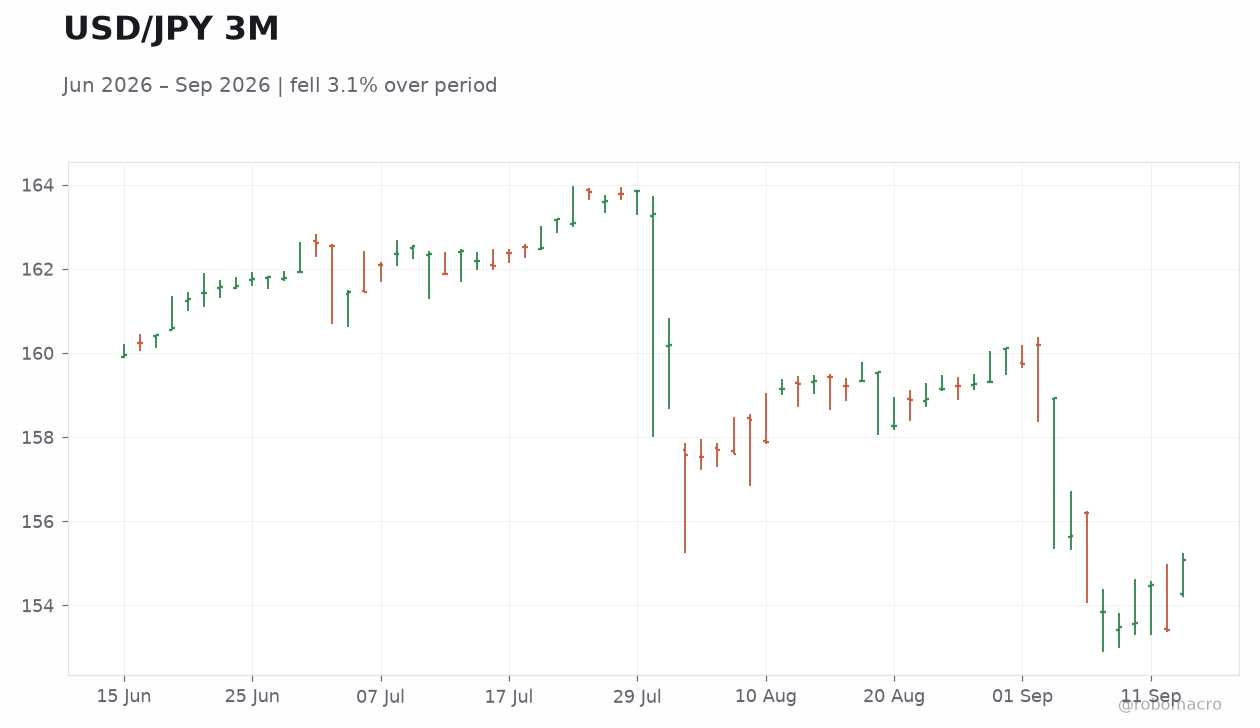
| USD/JPY | 155.04 | +0.42% |
| EUR/JPY | 178.91 | +0.58% |
| GBP/JPY | 208.92 | +0.23% |
| Gold | 4,333.20 | -0.43% |
| Brent Crude | 108.51 | +2.68% |
| Bitcoin | 75,802.18 | -3.02% |
| Japan 2Y Govt Yield | 1.84% | 0 bp |
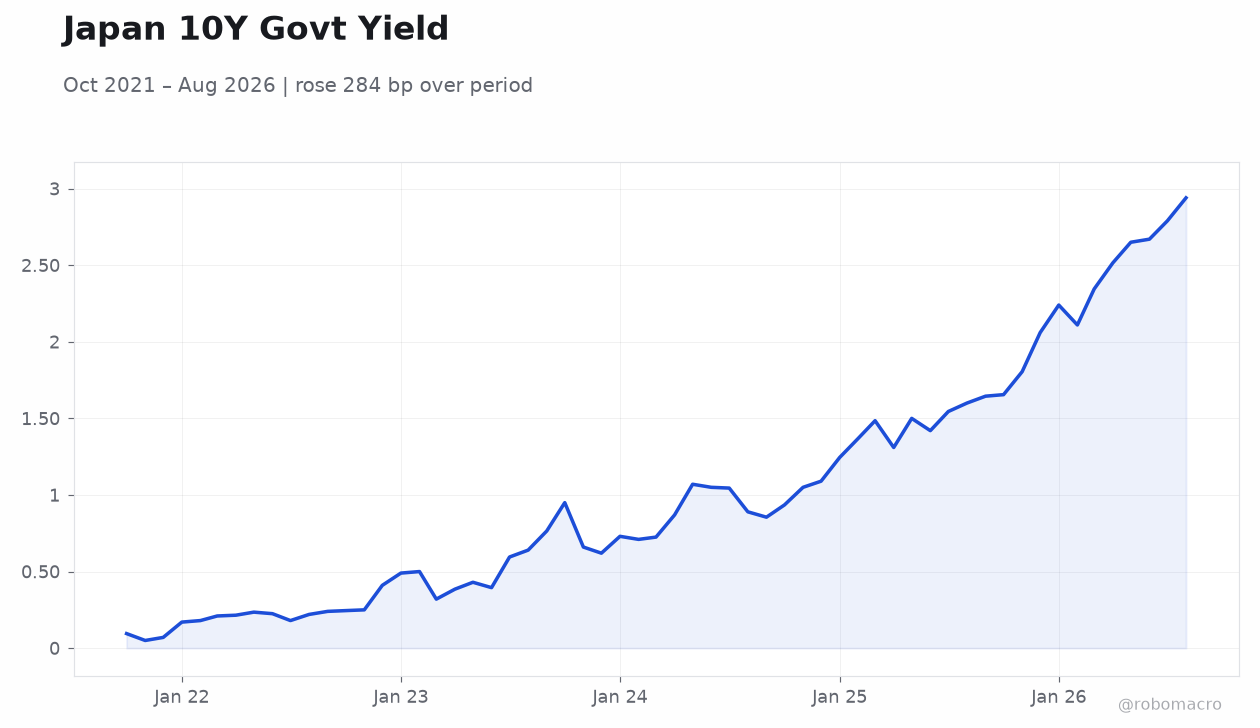
| Japan 10Y Govt Yield | 2.99% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
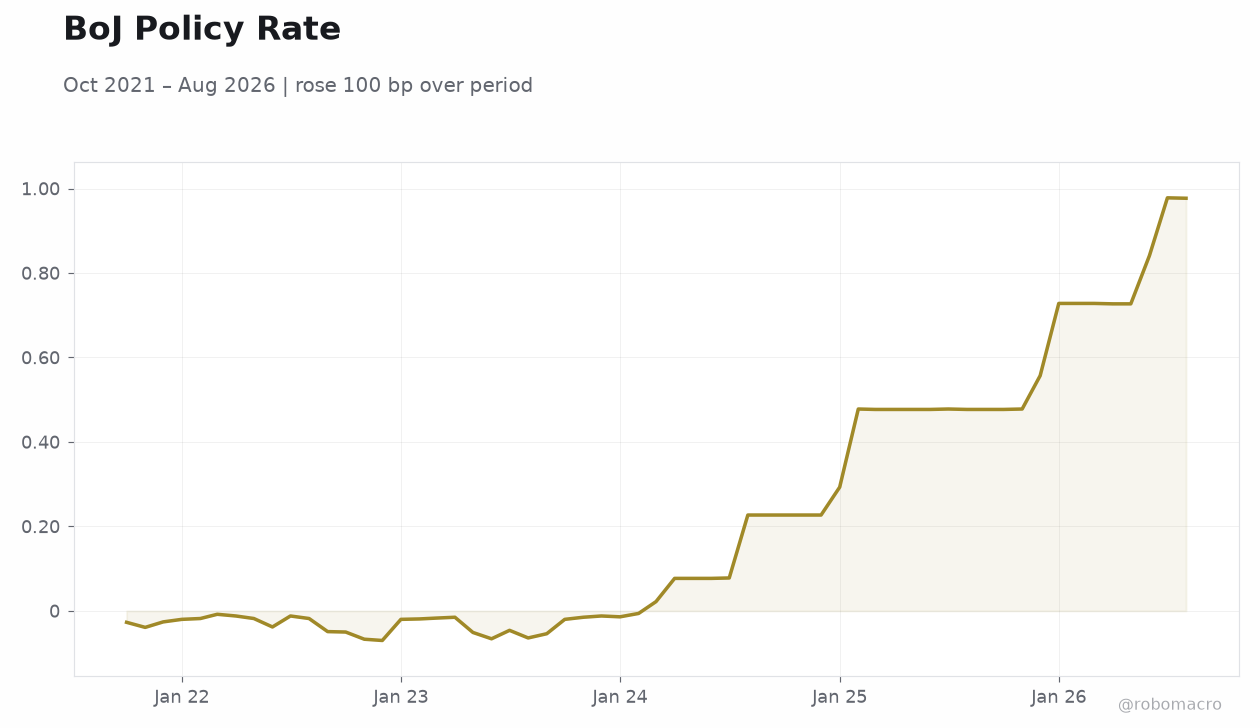 BoJ Policy Rate | Type: macro_line | Policy Rate %: 0.977 (2026-08-01) | Range: -0.07–0.978 | Trend(6pt): -0.027,-0.07,-0.006,0.477,0.841,0.977
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | -634,500m | -1,052,600m | 15:50 |
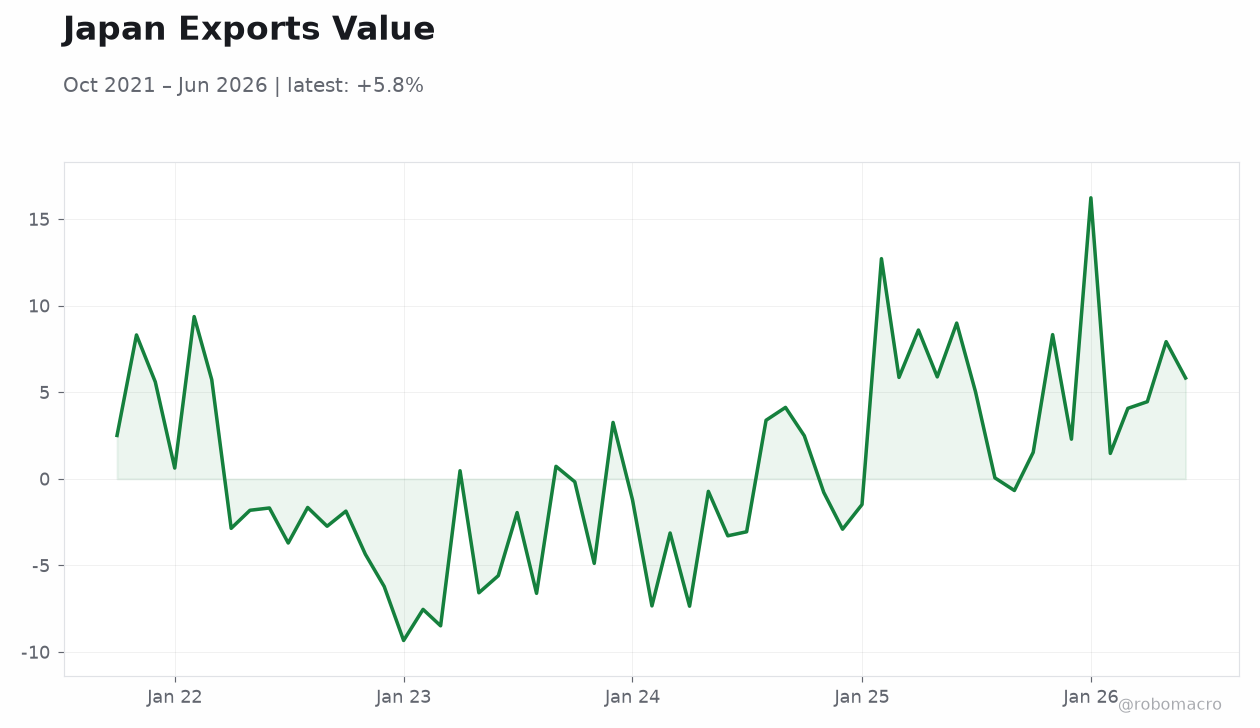
| Exports Year-over-Year | 23.20 | 18.20 | 15:50 |
| Machinery Orders Month-over-Month | 9.70 | -2.80 | 15:50 |
| Machinery Orders Year-over-Year | 16.90 | 15.30 | 15:50 |
| Thursday (2026-09-17) | |||
| Inflation Rate Year-over-Year | 2 | - | 15:30 |
| Core Inflation Rate Year-over-Year | 1.80 | 1.80 | 15:30 |
| BoJ Interest Rate Decision | 1 | 1.25 | 19:00 |
- Trade balance and machinery orders due today at 15:50 JST with markets expecting sharp deterioration in external balances.
- BoJ policy rate decision on Thursday carries consensus for a 25 bp lift to 1.25% from the current 1.00%.
- Yen underperformed into the meeting with USD/JPY closing at 155.04 after a 0.42% daily gain.
Yesterday's Recap
No economic data were released on September 14. The Nikkei 225 fell 0.81% to close at 63,492.99 while USD/JPY rose 0.42% to 155.04. EUR/JPY advanced 0.58% to 178.91 and GBP/JPY gained 0.23% to 208.92.
The Japan 2-year government yield held steady at 1.84% and the 10-year yield remained at 2.99%. Brent crude climbed 2.68% to 108.51 while gold slipped 0.43% to 4,333.20. Bitcoin declined 3.02% to 75,802.18.
Market attention stayed fixed on the upcoming Bank of Japan meeting with no speeches or minutes released. The absence of fresh domestic indicators left positioning driven entirely by global rate expectations and yen-intervention speculation.
The Day Ahead
Four high- and medium-impact releases are scheduled for 15:50 JST today. The trade balance is expected to widen to -1,052.6 billion yen from the prior -634.5 billion. Exports year-over-year are forecast to slow to 18.2% from 23.2%.
Machinery orders month-over-month are projected to contract 2.8% after a 9.7% gain while the year-over-year reading is seen easing to 15.3% from 16.9%. Thursday brings August inflation figures at 15:30 JST followed by the BoJ interest rate decision at 19:00 JST where markets price a move to 1.25%. The trade balance print carries the largest immediate potential to shift USD/JPY and JGB yields.
Any material miss on exports could reinforce views that external demand is cooling faster than anticipated, adding pressure on the currency ahead of the policy announcement.
Other Economic Notes
Japan’s external sector continues to face headwinds from softer global demand and a stronger yen trajectory priced into the BoJ decision. Analysts note that any sustained yen rally will depend on the scale of the rate increase and the tone of the accompanying outlook report. Reports also flag the possibility that Japanese authorities sold Treasuries to finance record-scale yen intervention in recent weeks.
The combination of still-elevated energy prices and moderating export growth is keeping the current-account surplus under pressure. Markets remain focused on whether the BoJ will signal further normalisation steps beyond Thursday’s expected adjustment. ↓ p.2