Japan Macro Daily(Beta Mode)
Yen Weakens After BOJ Disappoints Markets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 65,018.95 | +1.38% |
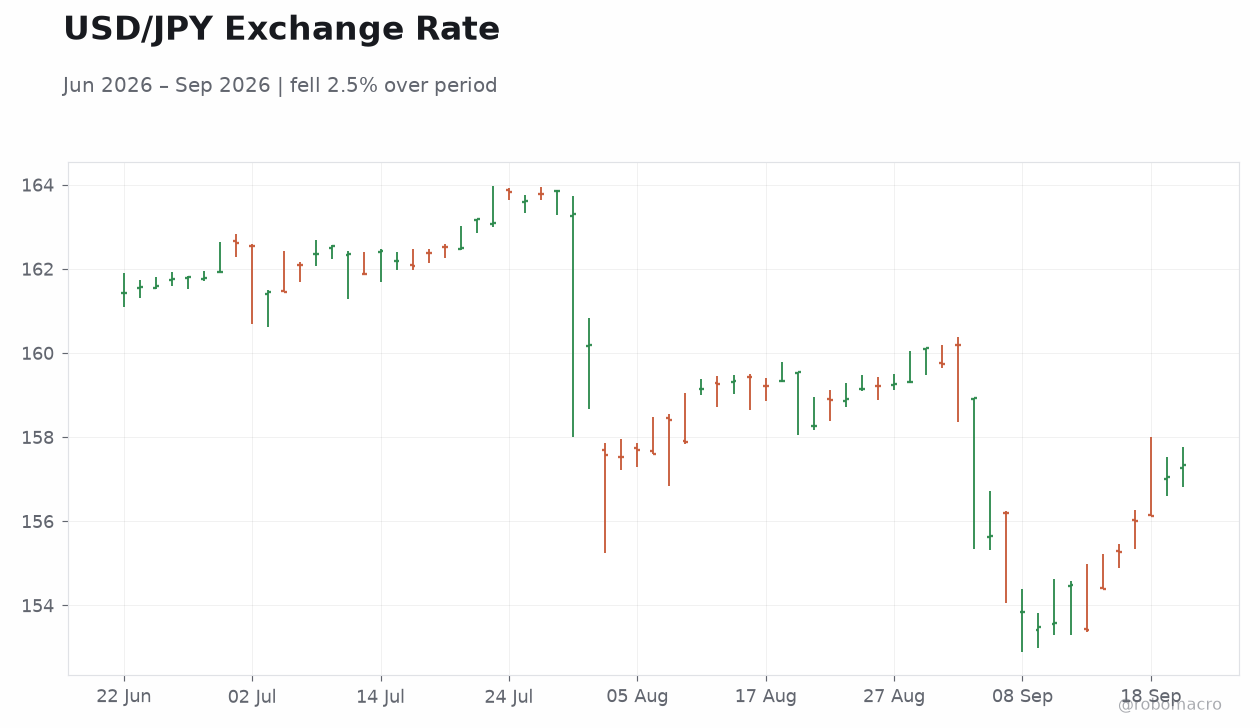
| USD/JPY | 157.33 | -0.02% |
| EUR/JPY | 180.15 | -0.14% |
| GBP/JPY | 209.96 | -0.15% |
| Gold | 4,396.90 | +0.30% |
| Brent Crude | 98.52 | -1.81% |
| Bitcoin | 86,285.46 | -0.37% |
| Japan 2Y Govt Yield | 1.87% | +2 bp |
| Japan 10Y Govt Yield | 2.99% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
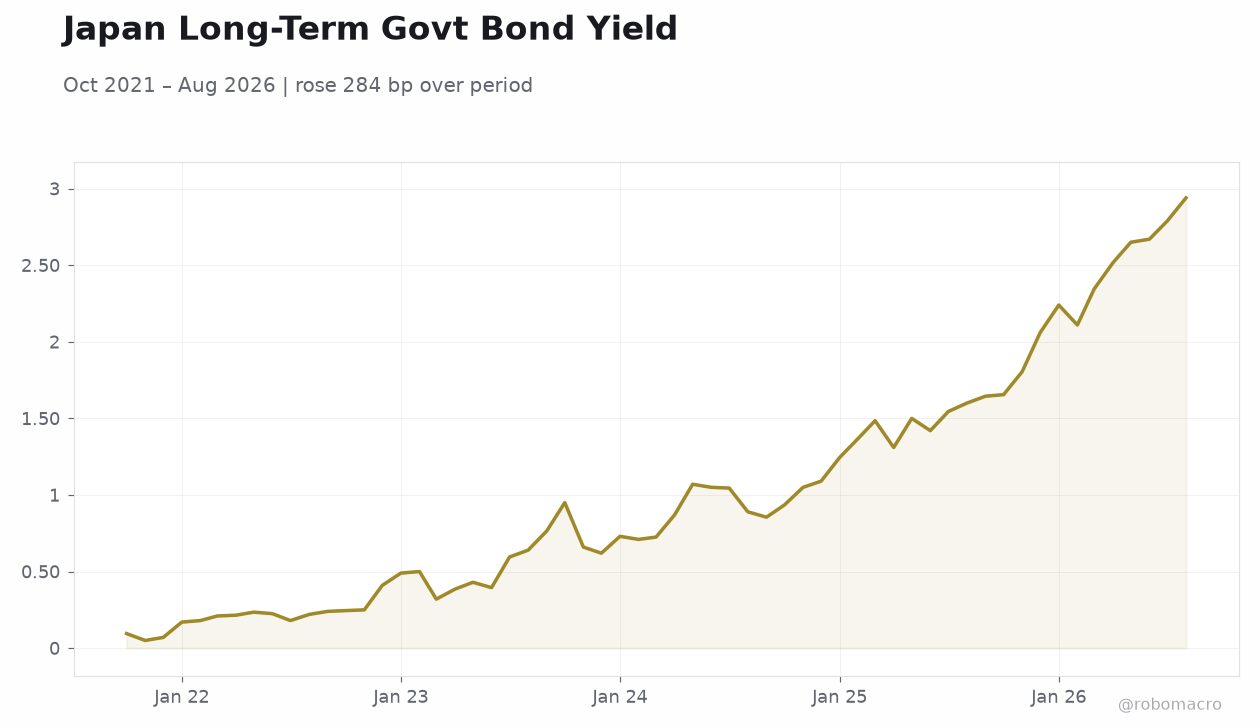 Japan Long-Term Govt Bond Yield | Type: macro_line | Yield %: 2.94 (2026-08-01) | Range: 0.05–2.94 | Trend(6pt): 0.095,0.41,0.71,1.31,2.67,2.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nikkei 225 rises 1.38% to 65,018.95 as yen softness persists
- USD/JPY holds at 157.33 after BoJ rate decision disappoints markets
- Japan 10Y JGB yield eases 1 bp to 2.99% while 2Y yield climbs 2 bp to 1.87%
Yesterday's Recap
No economic data releases occurred on 21 September. The Nikkei 225 advanced 1.38% to close at 65,018.95 while Brent crude fell 1.81% to 98.52 and gold gained 0.30% to 4,396.90. USD/JPY settled at 157.33, little changed on the day, as EUR/JPY and GBP/JPY each declined modestly.
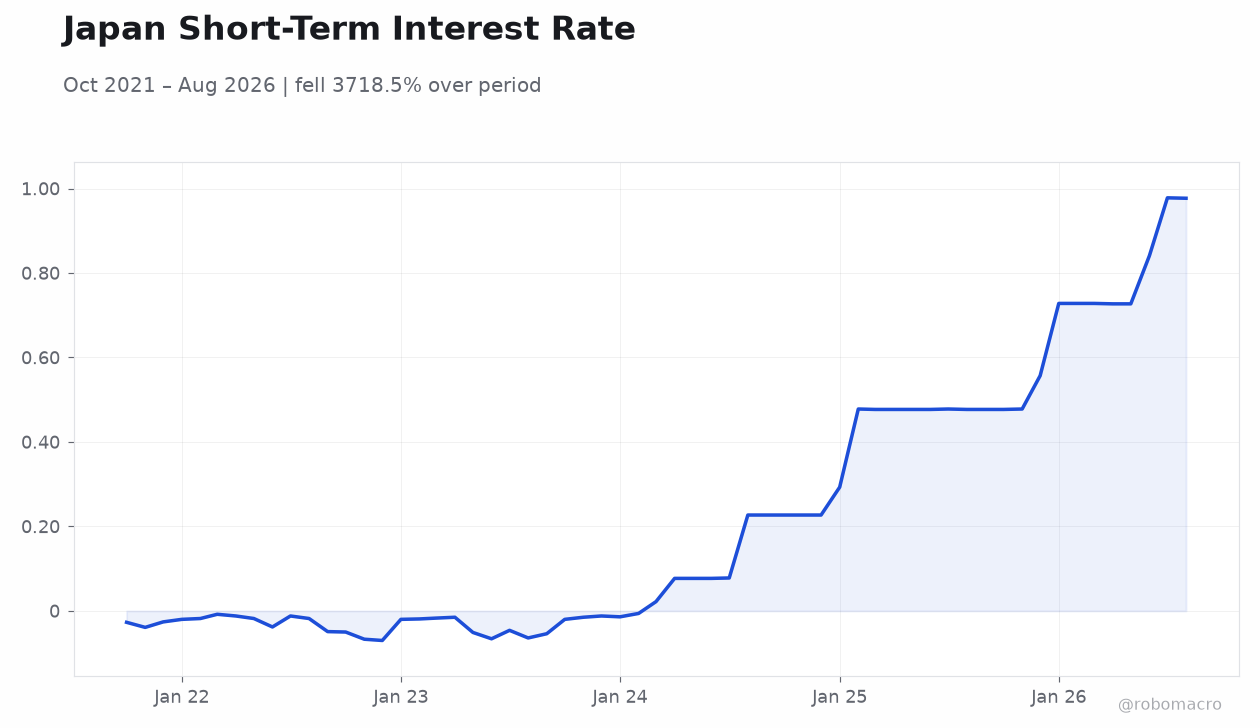
Japan 2-year JGB yields rose 2 bp to 1.87% and the 10-year yield slipped 1 bp to 2.99%. News flow centred on the Bank of Japan’s recent split vote and the yen’s post-decision slide, leaving the currency vulnerable during Japan’s public holiday. Market participants noted that carry trades remained active despite the rate increase, with sustained yen weakness viewed as raising the prospect of official intervention.
Bitcoin closed 0.37% lower at 86,285.46, adding to subdued risk sentiment without direct impact on yen crosses.
The Day Ahead
No domestic data releases or Bank of Japan events are scheduled for 22 September. Markets will monitor USD/JPY levels closely for any signs of renewed depreciation pressure. Global equity and commodity moves, including Brent crude and gold, may influence yen sentiment through risk and carry channels.
Attention also remains on whether the recent rate decision alters expectations for the BoJ’s quarterly pace of policy adjustments. Traders will watch for any official comments on exchange-rate developments during the holiday period.
Other Economic Notes
Coverage highlighted the first sustained post-bubble increase in big Japanese banks’ domestic loan share, signalling gradual normalisation in credit demand. Japan’s CPI stood at 1.90% year-on-year as of end-August, providing limited immediate impetus for faster tightening. Yen weakness continues to support exporter earnings yet raises imported inflation risks for households.
Broader themes include the durability of the yen’s rate differential against major currencies and the potential for intervention if depreciation accelerates further. The 1.00% policy rate leaves real yields negative relative to CPI, sustaining pressure on the currency.