Japan Macro Daily(Beta Mode)
Yen Nears 160 as Intervention Risks Re-Emerge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 65,018.95 | +1.38% |
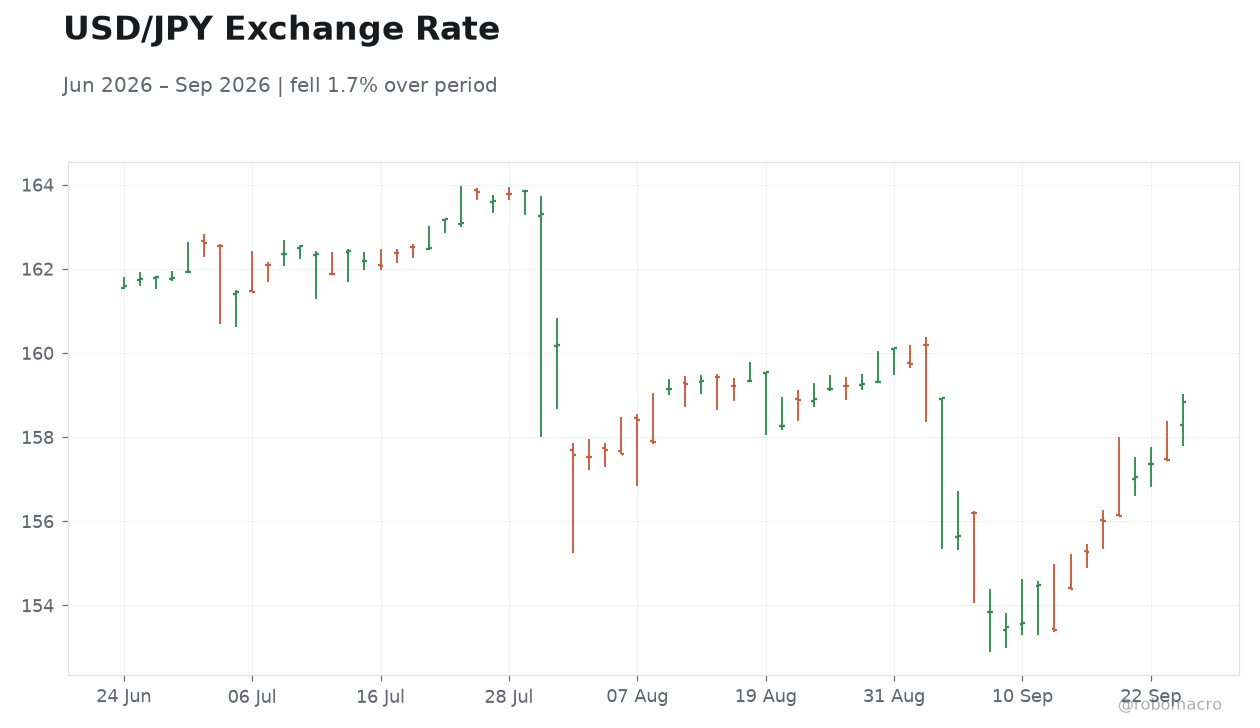
| USD/JPY | 158.82 | +0.86% |
| EUR/JPY | 180.69 | +0.24% |
| GBP/JPY | 209.87 | -0.11% |
| Gold | 4,307.10 | -0.26% |
| Brent Crude | 107.11 | +3.91% |
| Bitcoin | 84,352.61 | -0.04% |
| Japan 2Y Govt Yield | 1.85% | -2 bp |
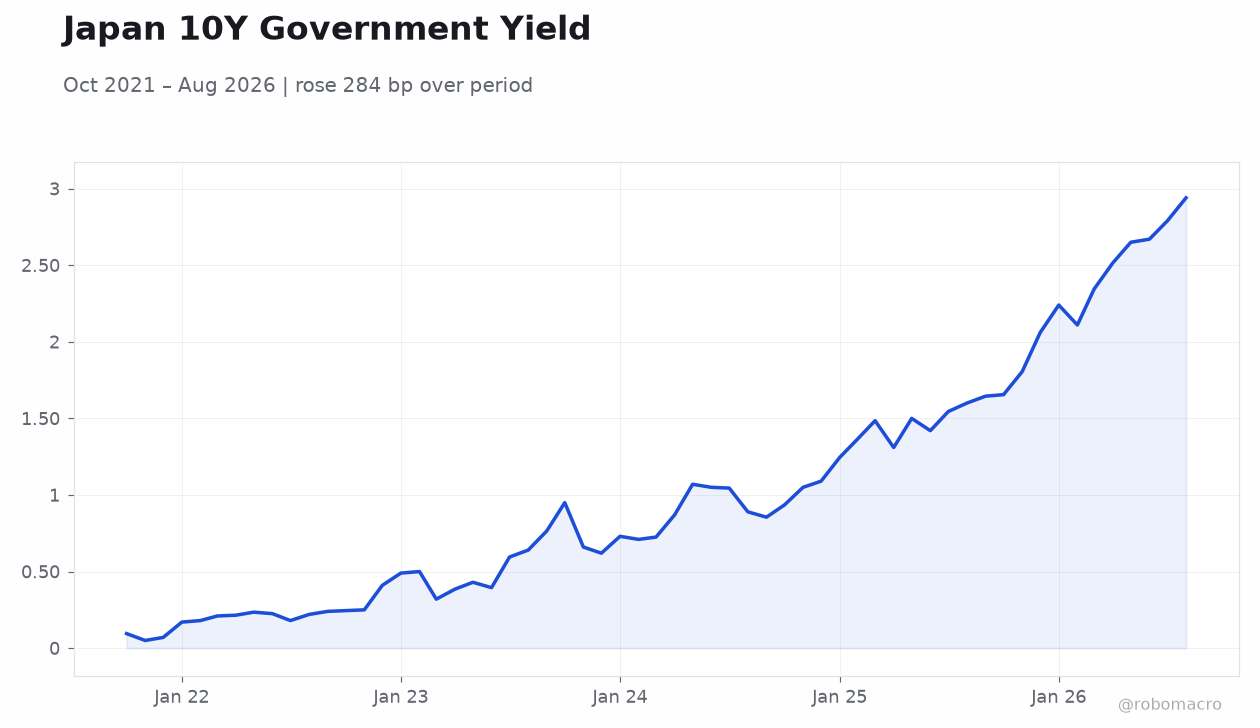
| Japan 10Y Govt Yield | 2.98% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
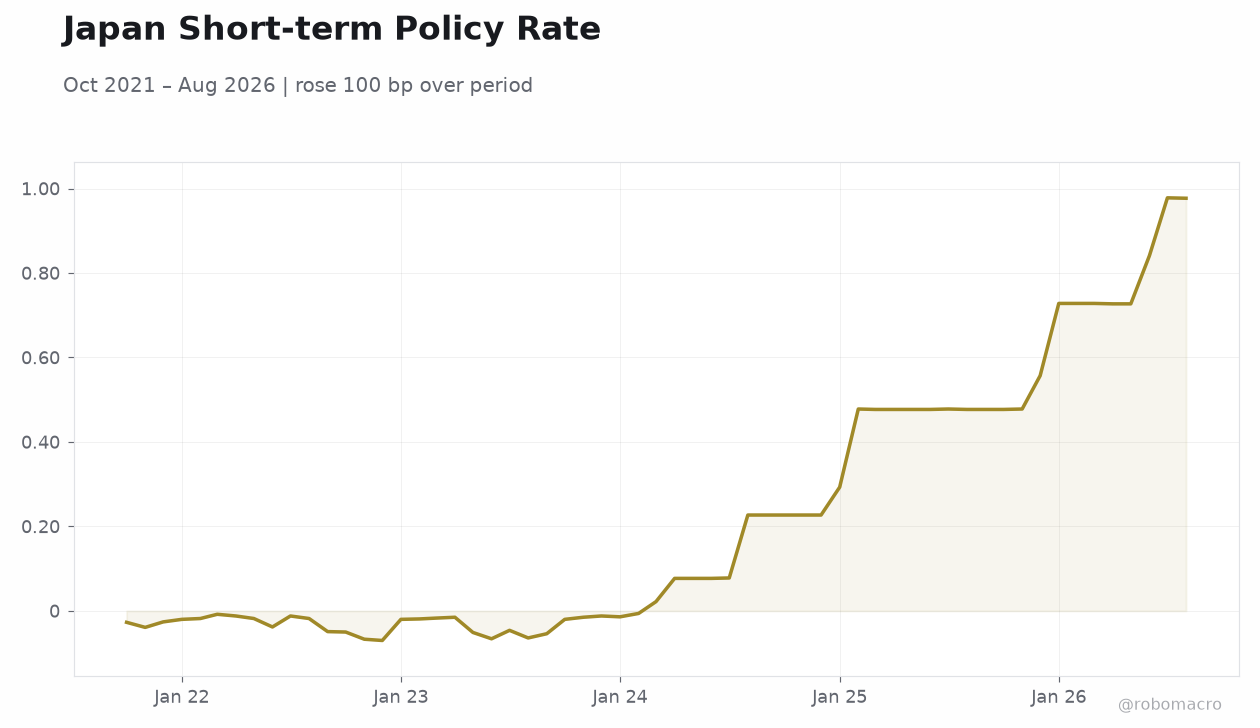 Japan Short-term Policy Rate | Type: macro_line | Percent: 0.977 (2026-08-01) | Range: -0.07–0.978 | Trend(6pt): -0.027,-0.07,-0.006,0.477,0.841,0.977
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nikkei 225 climbs 1.38% to 65,018.95 on AI-driven chip gains
- USD/JPY advances 0.86% to 158.82, testing post-intervention levels
- Brent crude jumps 3.91% to 107.11 amid tanker cost shocks
Yesterday's Recap
Japanese markets recorded no economic data releases on 23 September. The Nikkei 225 advanced 1.38% to close at 65,018.95, led by chip stocks amid broader AI rally momentum. USD/JPY rose 0.86% to 158.82 while EUR/JPY gained 0.24% to 180.69, reflecting persistent yen softening despite the recent Bank of Japan rate increase.
The 2-year JGB yield fell 2 basis points to 1.85% and the 10-year yield eased 1 basis point to 2.98%. Brent crude surged 3.91% to 107.11 on reports of $1 million daily oil-tanker costs, adding fresh inflation pressure. Gold declined 0.26% to 4,307.10 and Bitcoin held near flat at 84,352.61.
Multiple reports highlighted re-emerging foreign-exchange intervention risks as USD/JPY approached the 160 threshold. GBP/JPY eased 0.11% to 209.87 as the wide interest-rate gap versus the UK continued to support sterling. Commentary from several outlets noted that the 4% USD/JPY rally challenges the post-intervention downtrend, with Fed rate-hike expectations lifting US yields and weighing further on the yen ahead of the next BoJ decision.
The Day Ahead
No Japanese economic releases or Bank of Japan events are scheduled for 24 September. Markets will monitor USD/JPY movement near 160 for any official intervention signals. Attention remains on US yields and Federal Reserve policy expectations that continue to weigh on the yen.
Traders will also track global equity sentiment, particularly AI-related flows supporting Japanese exporters. Oil price developments could influence near-term inflation expectations ahead of the next policy meeting. Yen weakness is viewed as supportive for multinationals, while tanker-cost shocks add imported inflation risks that may complicate gradual policy normalisation.
Other Economic Notes
Japan’s 2026 GDP per capita stands at $34,017 according to FourWeekMBA estimates. Elevated tanker costs threaten a fresh inflation shock that could complicate the Bank of Japan’s gradual normalisation path. AI-driven equity strength and yen weakness together support Japanese exporters and equity valuations.
The wide interest-rate differential versus the United States and United Kingdom continues to pressure the yen lower. These factors collectively shape the external backdrop for domestic growth and price stability. August CPI at 1.90% leaves measured room for further adjustments without immediate overheating concerns.