Japan Macro Daily(Beta Mode)
Yen Rises on Warnings of Weak Currency
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 66,364.20 | +1.30% |
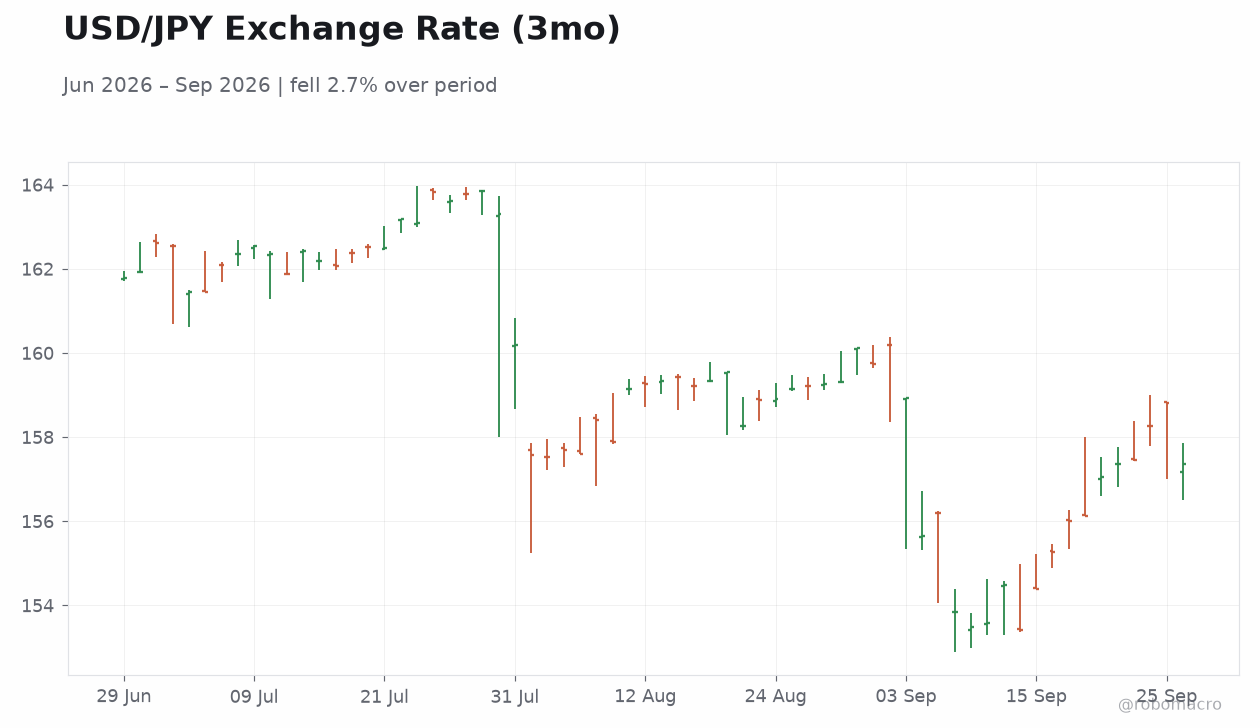
| USD/JPY | 157.43 | -0.87% |
| EUR/JPY | 178.95 | -0.94% |
| GBP/JPY | 208.74 | -0.50% |
| Gold | 4,145.10 | -4.08% |
| Brent Crude | 98.67 | -5.42% |
| Bitcoin | 83,578.22 | -1.04% |
| Japan 2Y Govt Yield | 1.95% | +4 bp |
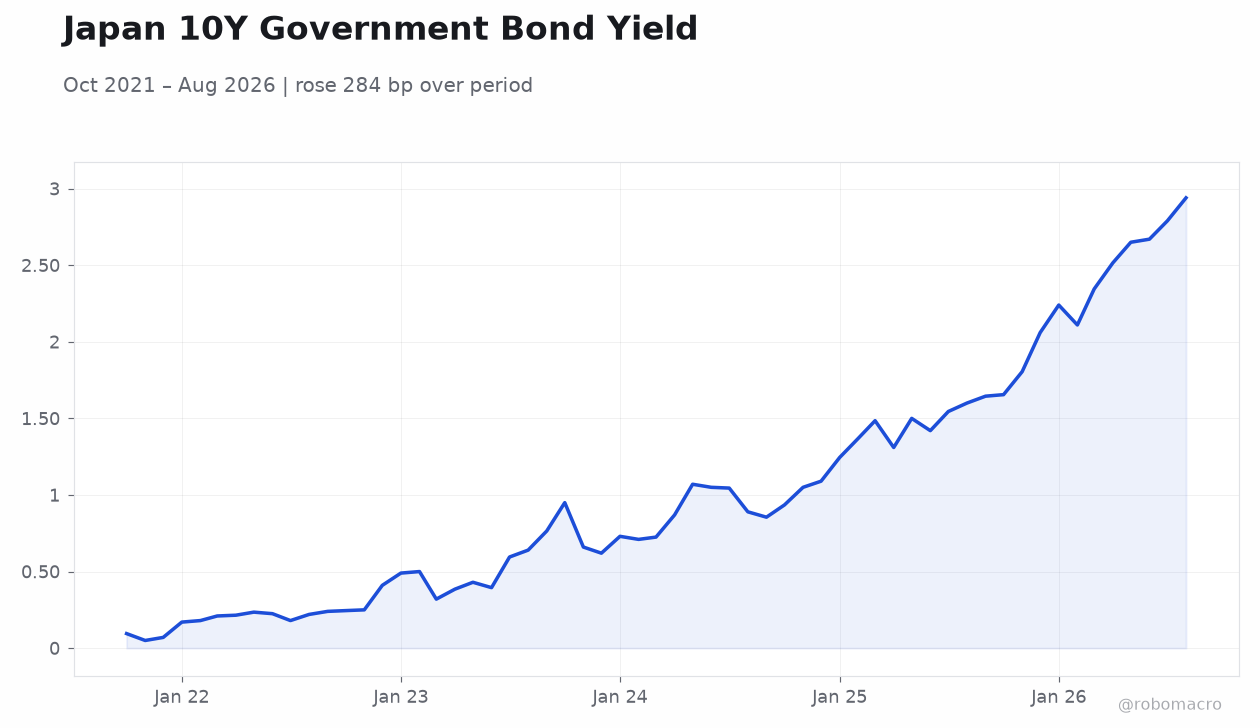
| Japan 10Y Govt Yield | 3.07% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
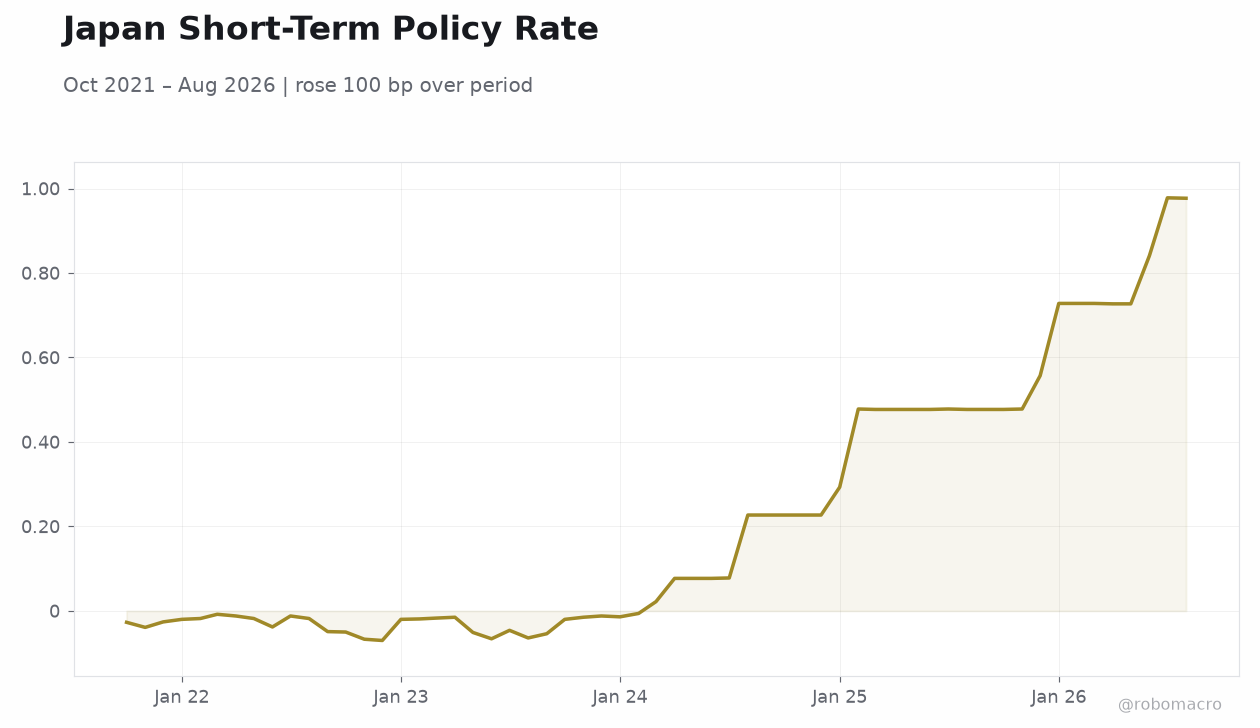 Japan Short-Term Policy Rate | Type: macro_line | %: 0.977 (2026-08-01) | Range: -0.07–0.978 | Trend(6pt): -0.027,-0.07,-0.006,0.477,0.841,0.977
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-09-29) | |||
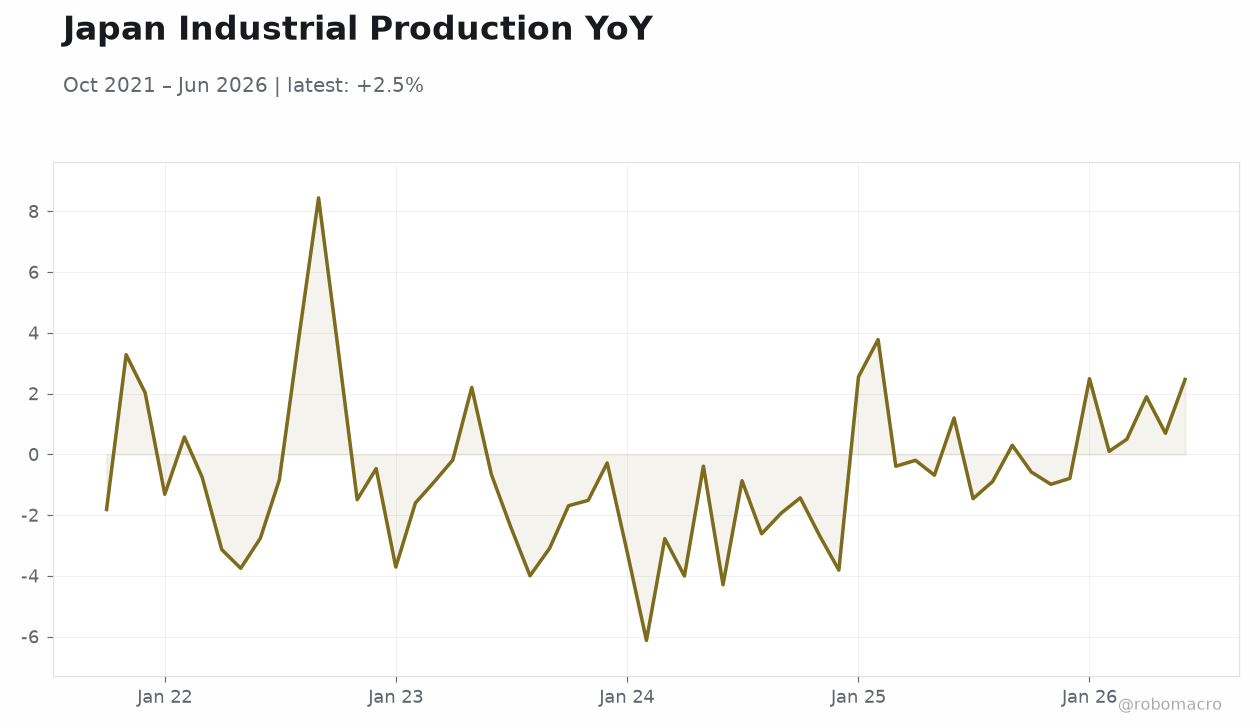
| Industrial Production Month-over-Month Preliminary | -0.20 | 1.70 | 15:50 |
| Retail Sales Year-over-Year | 4 | 3.30 | 15:50 |
| Wednesday (2026-09-30) | |||
| Housing Starts Year-over-Year | 8.20 | 7 | 21:00 |
| Tankan Large Manufacturers Index | 22 | 25 | 15:50 |
| BoJ Summary of Opinions | - | - | 15:50 |
| Thursday (2026-10-01) | |||
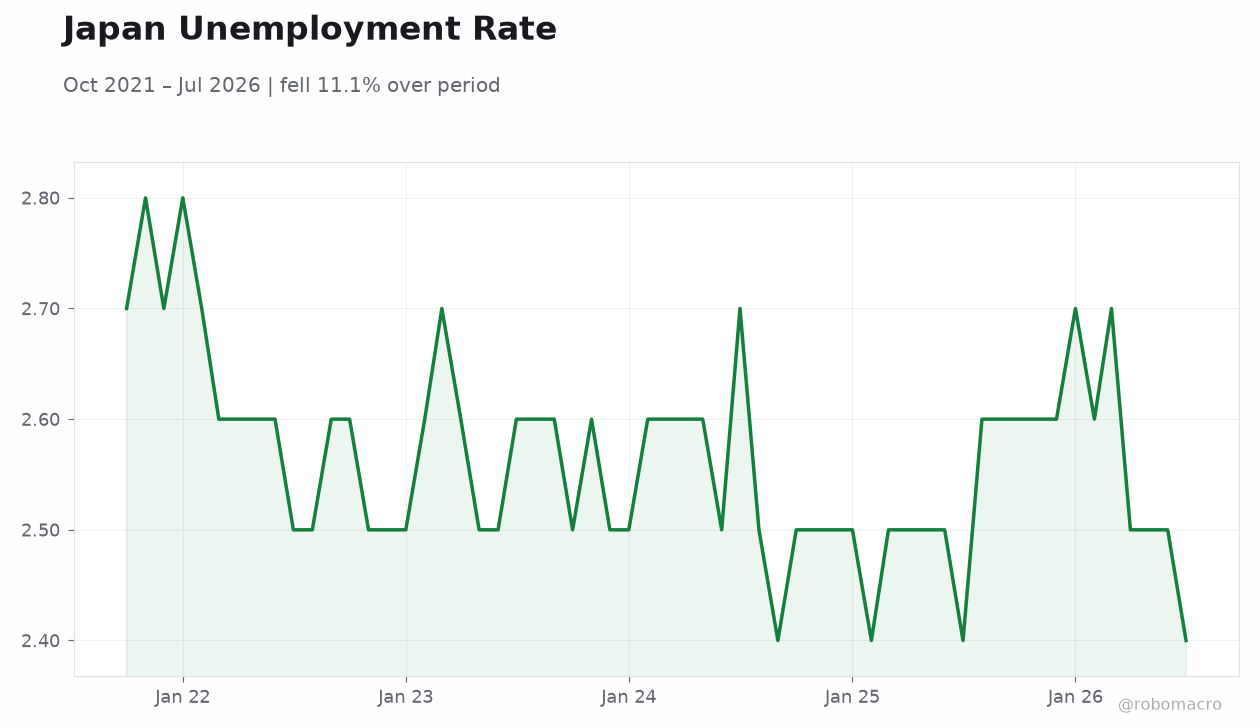
| Headline Unemployment Rate | 2.40 | 2.40 | 15:30 |
- Yen strengthens as officials flag weak currency risks and coordinate with US on stronger levels.
- Nikkei 225 gains 1.30% while 2-year JGB yield rises 4 bp to 1.95%.
- Markets price faster BoJ normalisation ahead of Tankan and Summary of Opinions.
Yesterday's Recap
No economic data releases occurred on 27 September. Markets instead reacted to statements from Japanese officials that a weak yen poses problems for the economy. USD/JPY fell 0.87% to 157.43 while EUR/JPY dropped 0.94% to 178.95.
The Nikkei 225 advanced 1.30% to 66,364.20 as investors positioned for higher policy rates. The 2-year JGB yield increased 4 bp to 1.95% while the 10-year yield held steady at 3.07%. Gold declined 4.08% and Brent crude fell 5.42%, reflecting broader risk-off flows.
Officials also noted US concerns over yen weakness without altering existing coordination principles. Tokyo defended BoJ independence amid the comments, reinforcing expectations that policy decisions remain data-driven rather than politically influenced.
The Day Ahead
Industrial Production MoM and Retail Sales YoY release at 15:50 JST on 29 September, with consensus forecasts of +1.7% and +3.3% respectively. Housing Starts YoY follows on 30 September. The Tankan Large Manufacturers Index, expected at 25 versus 22 prior, arrives alongside the BoJ Summary of Opinions at 15:50 JST that day.
The unemployment rate prints on 1 October. These releases will shape expectations for the next policy adjustment. Markets will scrutinise the Summary of Opinions for signals on the pace of rate normalisation.
The Tankan reading in particular offers a timely gauge of corporate sentiment ahead of any further tightening steps.
Other Economic Notes
Service inflation reached a multi-year high, reinforcing the case for further tightening. Domestic demand stocks may respond to clearer BoJ signals on the path to the 2% target. Japan’s experience continues to challenge narratives linking high debt directly to inflation outcomes.
Political developments, including a new party registering zero support, remain peripheral to near-term macro dynamics. Carry-trade positions estimated near $2.3 trillion add sensitivity to any yen appreciation. The combination of firmer service prices and external pressure on the currency keeps the focus squarely on how quickly the central bank can normalise without disrupting growth.