Japan Macro Daily(Beta Mode)
BoJ Minutes Fuel Hike Bets as Yields Climb
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 65,877.62 | -0.73% |
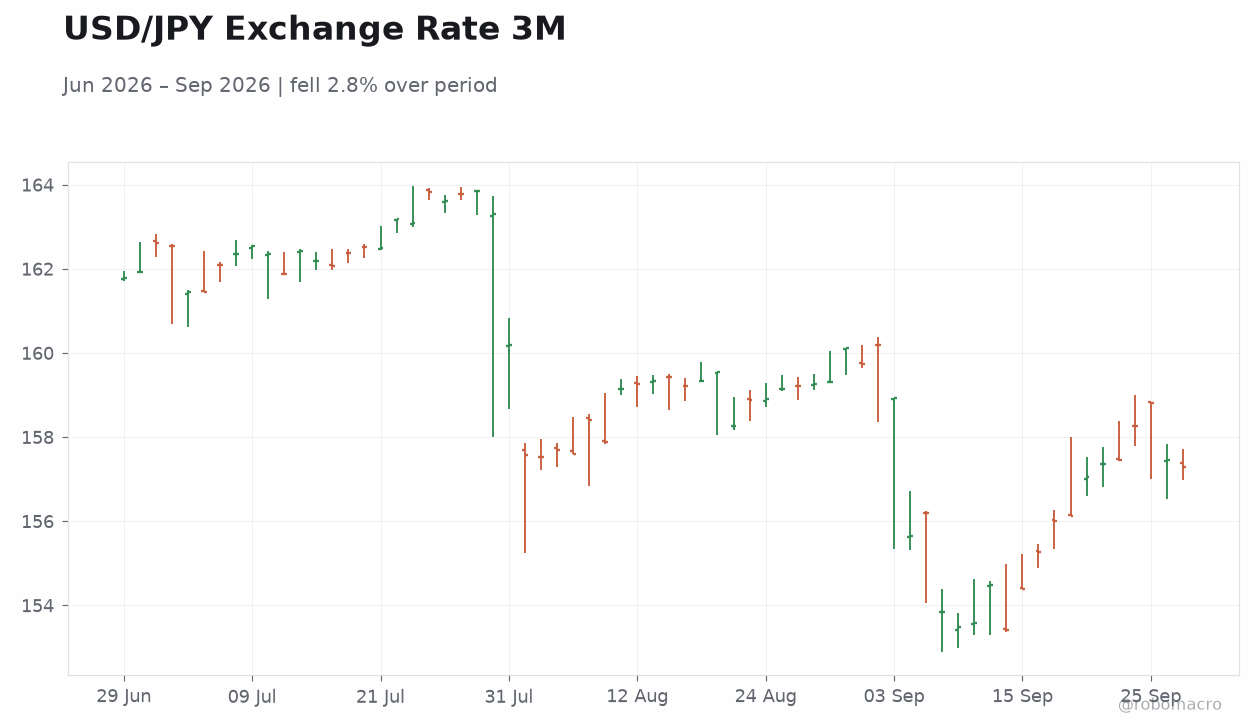
| USD/JPY | 157.31 | -0.10% |
| EUR/JPY | 178.34 | -0.46% |
| GBP/JPY | 208.03 | -0.13% |
| Gold | 4,213.90 | +1.09% |
| Brent Crude | 95.69 | -9.11% |
| Bitcoin | 83,586.24 | +0.10% |
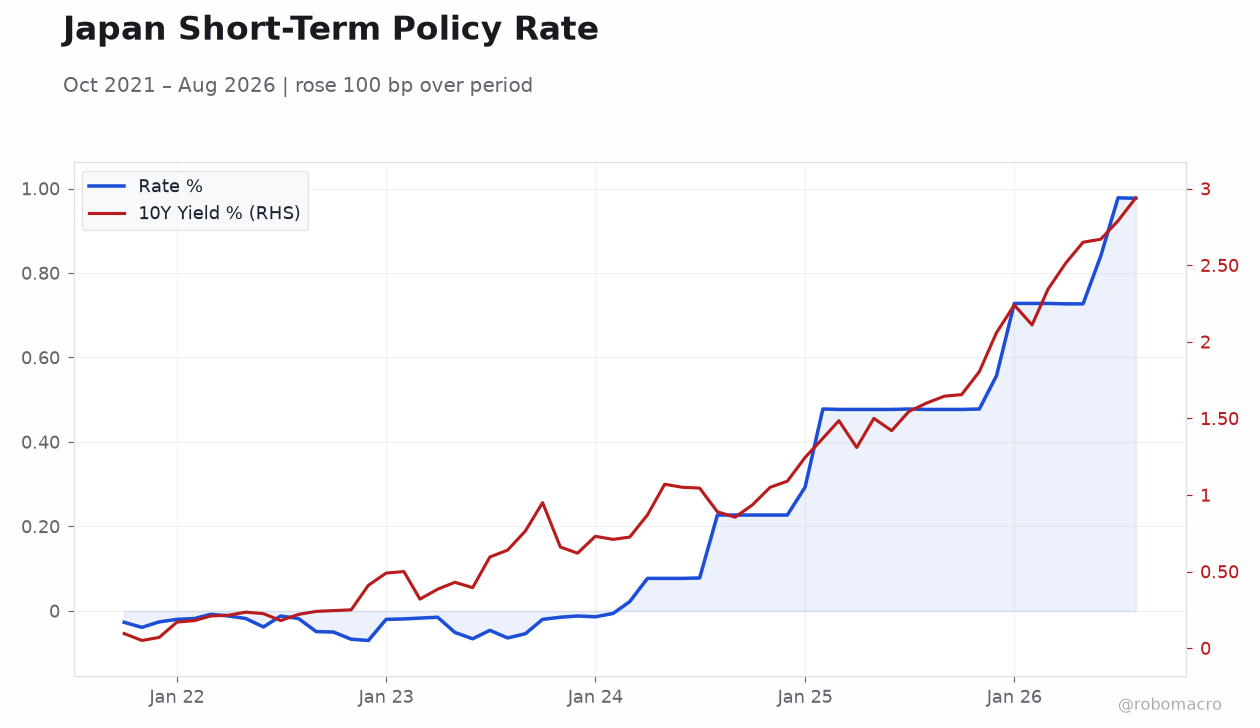
| Japan 2Y Govt Yield | 1.95% | +4 bp |
| Japan 10Y Govt Yield | 3.08% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
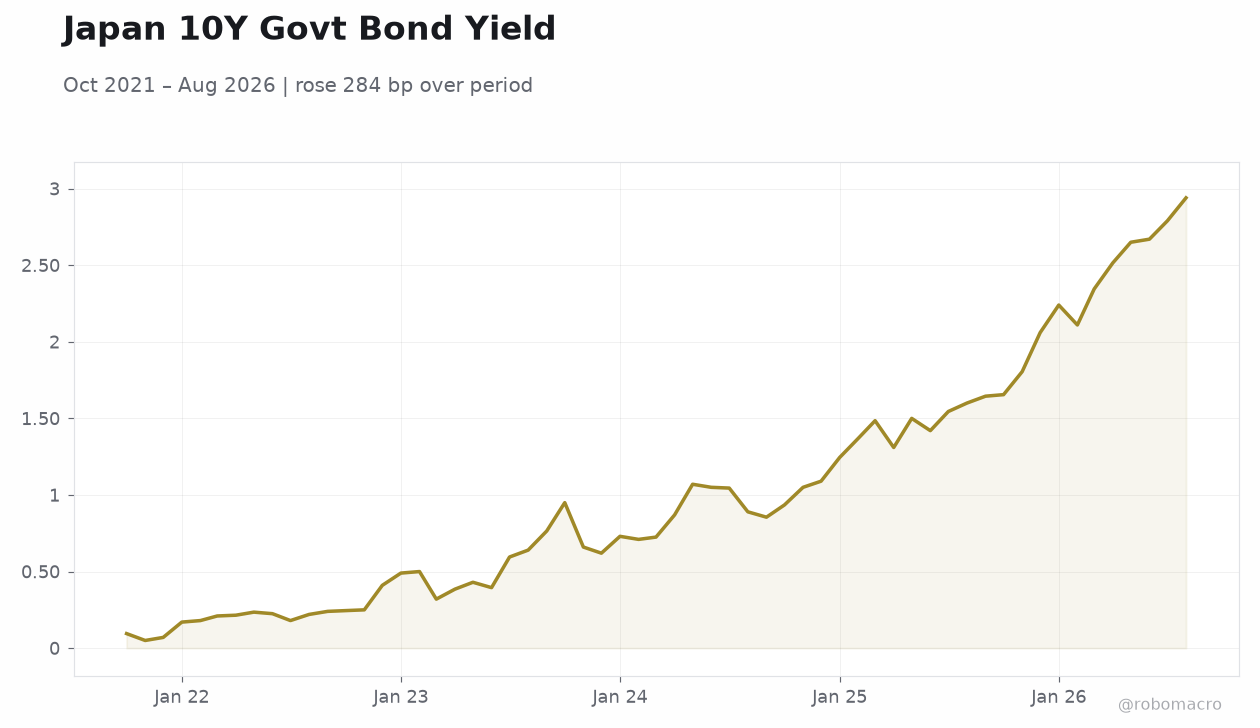 Japan 10Y Govt Bond Yield | Type: macro_line | Yield %: 2.94 (2026-08-01) | Range: 0.05–2.94 | Trend(6pt): 0.095,0.41,0.71,1.31,2.67,2.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
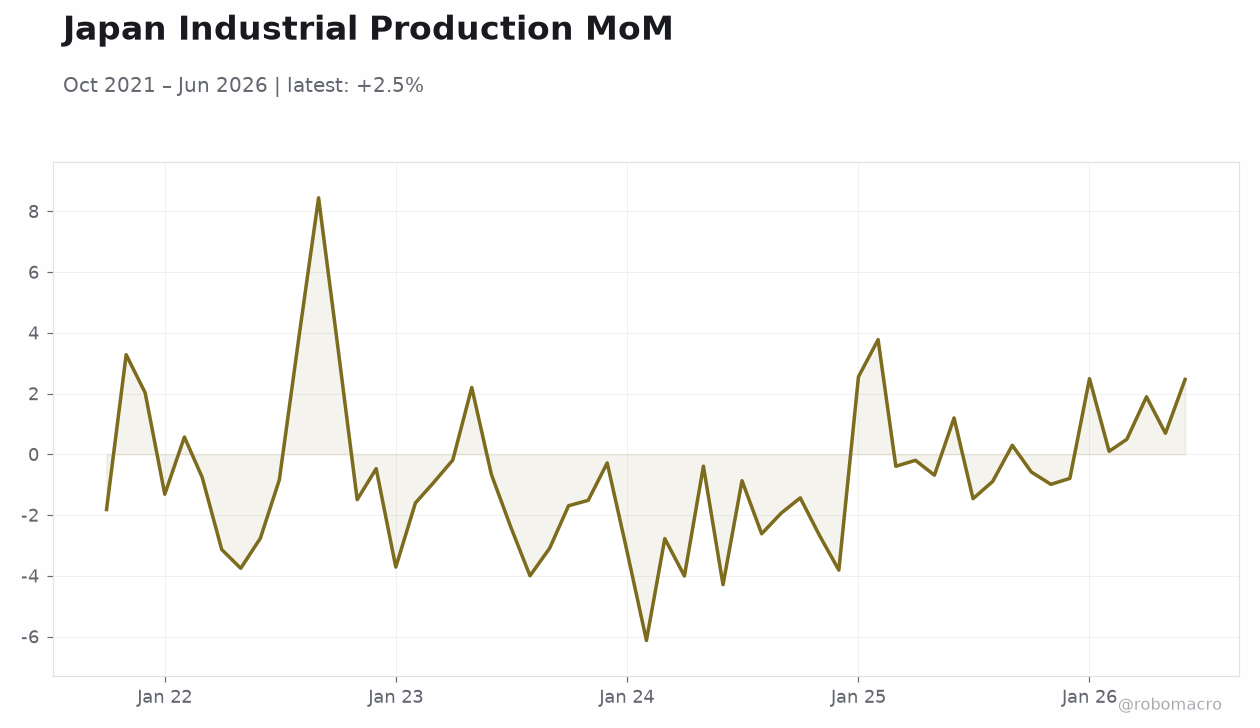
| Industrial Production Month-over-Month Preliminary | -0.20 | 1.70 | 15:50 |
| Retail Sales Year-over-Year | 4 | 3.30 | 15:50 |
| Wednesday (2026-09-30) | |||
| Housing Starts Year-over-Year | 8.20 | 7 | 21:00 |
| Tankan Large Manufacturers Index | 22 | 25 | 15:50 |
| BoJ Summary of Opinions | - | - | 15:50 |
| Thursday (2026-10-01) | |||
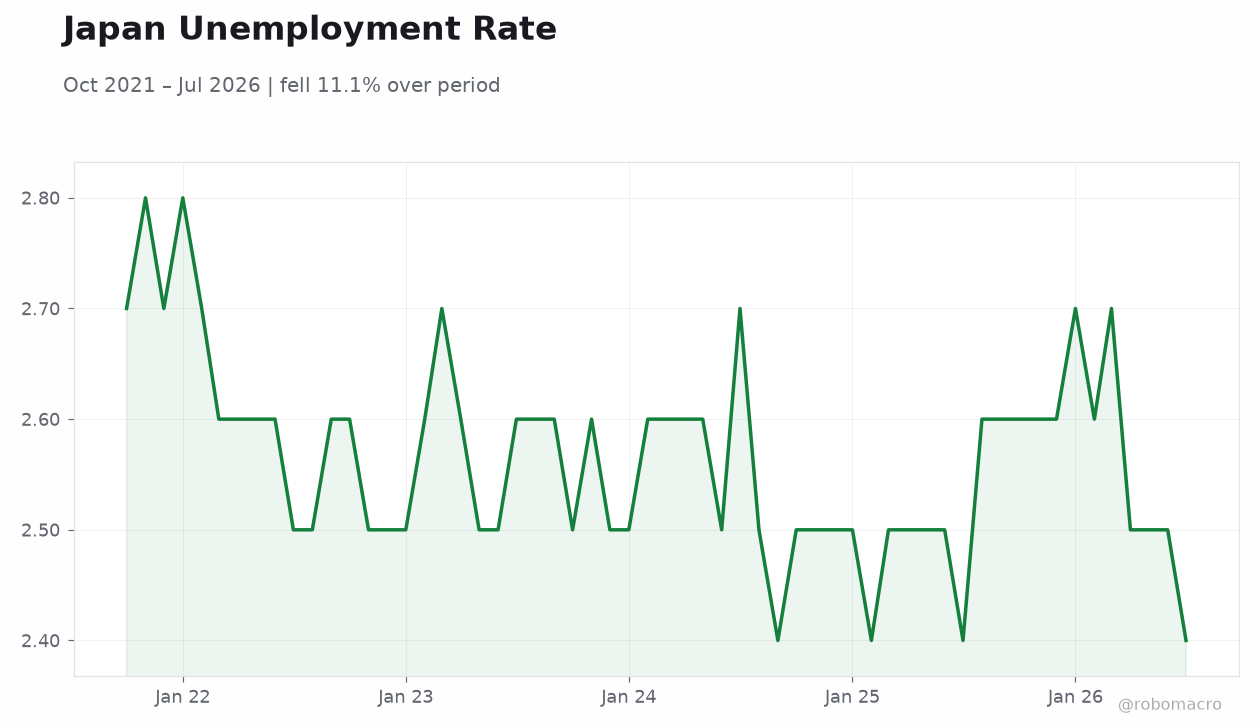
| Headline Unemployment Rate | 2.40 | 2.40 | 15:30 |
- July BoJ minutes show debate on accelerating rate hikes.
- 2-year JGB yield reaches 1.95% as October move odds rise.
- Yen steadies near 157.31 after fresh intervention warnings.
Yesterday's Recap
No economic data releases occurred on 28 September. The Nikkei 225 fell 0.73% to close at 65,877.62 while USD/JPY eased 0.10% to 157.31. The Japan 2-year government yield rose 4 basis points to 1.95% and the 10-year yield added 1 basis point to 3.08%.
July BoJ minutes released over the weekend revealed policymakers discussed the need for faster rate hikes to anchor 2% inflation. An ex-BoJ official stated that an October rate increase remains a real possibility. Tokyo stepped up verbal intervention warnings, with Citi noting action likely near 160.
Nidec CEO Mitsuya Kishida announced his resignation amid these market developments.
The Day Ahead
Industrial Production Month-over-Month Preliminary and Retail Sales Year-over-Year are due at 15:50 today with consensus forecasts of +1.7% and +3.3% respectively. Housing Starts Year-over-Year follow at 21:00. Tomorrow brings the high-impact Tankan Large Manufacturers Index at 15:50, expected to rise to 25 from 22, alongside the BoJ Summary of Opinions.
Markets will assess these releases for signs of domestic demand strength and implications for near-term policy tightening. The Headline Unemployment Rate is scheduled for 15:30 on 1 October.
Other Economic Notes
Japan service inflation has reached a more than two-year high, reinforcing the case for further BoJ tightening. The country continues to diversify energy imports away from the Middle East following repeated supply shocks. July minutes indicate the committee has shifted focus toward firmly anchoring 2% inflation rather than tolerating undershoots.
Corporate developments such as the Nidec leadership change add to sector-specific volatility. Broader data show Japan CPI YoY at 1.90% as of end-August, leaving real yields attractive relative to peers.
Global Macro News
Brent Crude dropped 9.11% to 95.69, easing imported energy costs for Japan. Gold advanced 1.09% to 4,213.90 as investors sought safe-haven assets amid oil volatility. Bitcoin edged 0.10% higher to 83,586.24.
USD/JPY has rallied 4% recently, testing post-intervention downtrends and prompting renewed warnings from Tokyo officials. ↓ p.2