Japan Macro Daily(Beta Mode)
Weak Data Dim BOJ Hike Odds
Market Snapshot
| Asset | Level | Change |
|---|---|---|
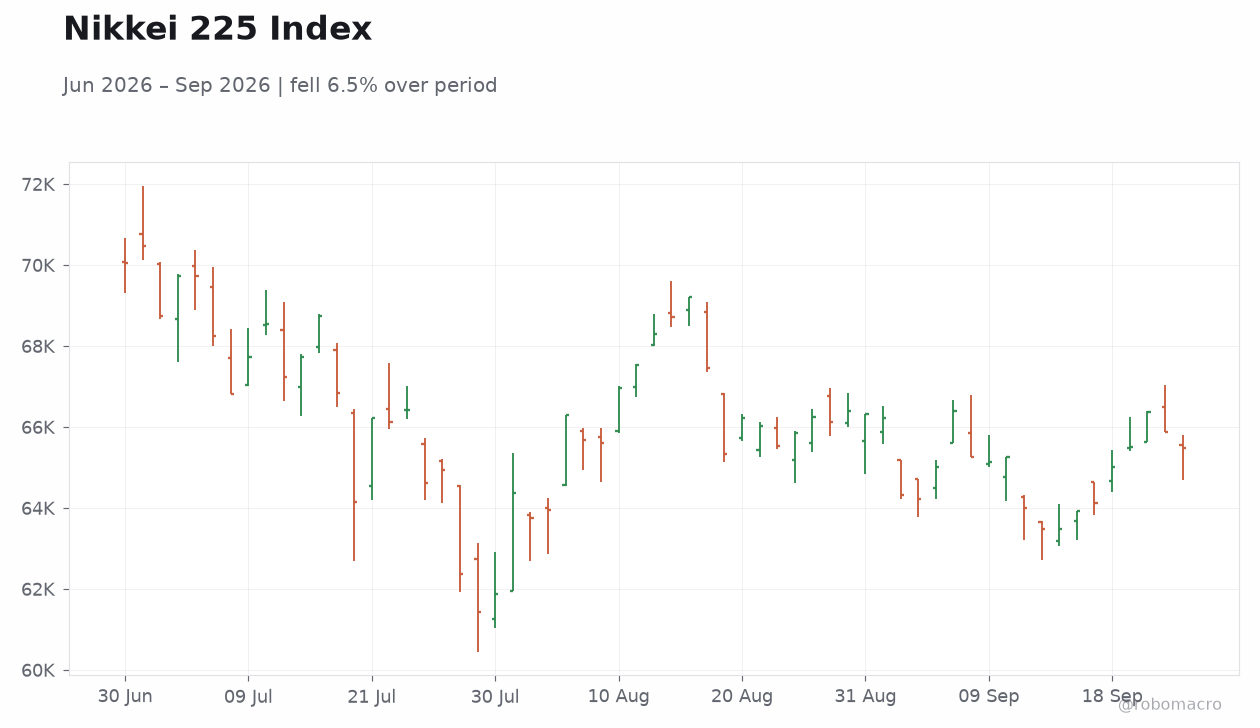
| Nikkei 225 | 65,481.27 | -0.60% |
| USD/JPY | 157.41 | +0.00% |
| EUR/JPY | 178.33 | -0.10% |
| GBP/JPY | 208.73 | +0.08% |
| Gold | 4,189.20 | +0.23% |
| Brent Crude | 97.92 | -4.55% |
| Bitcoin | 83,666.94 | +0.05% |
| Japan 2Y Govt Yield | 1.98% | +3 bp |
| Japan 10Y Govt Yield | 3.08% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Month-over-Month Preliminary | -0.20 | 1.70 | -1.70 |
| Retail Sales Year-over-Year | 3.70 | 3.30 | 2.70 |
| Housing Starts Year-over-Year | 8.20 | 7 | 6.10 |
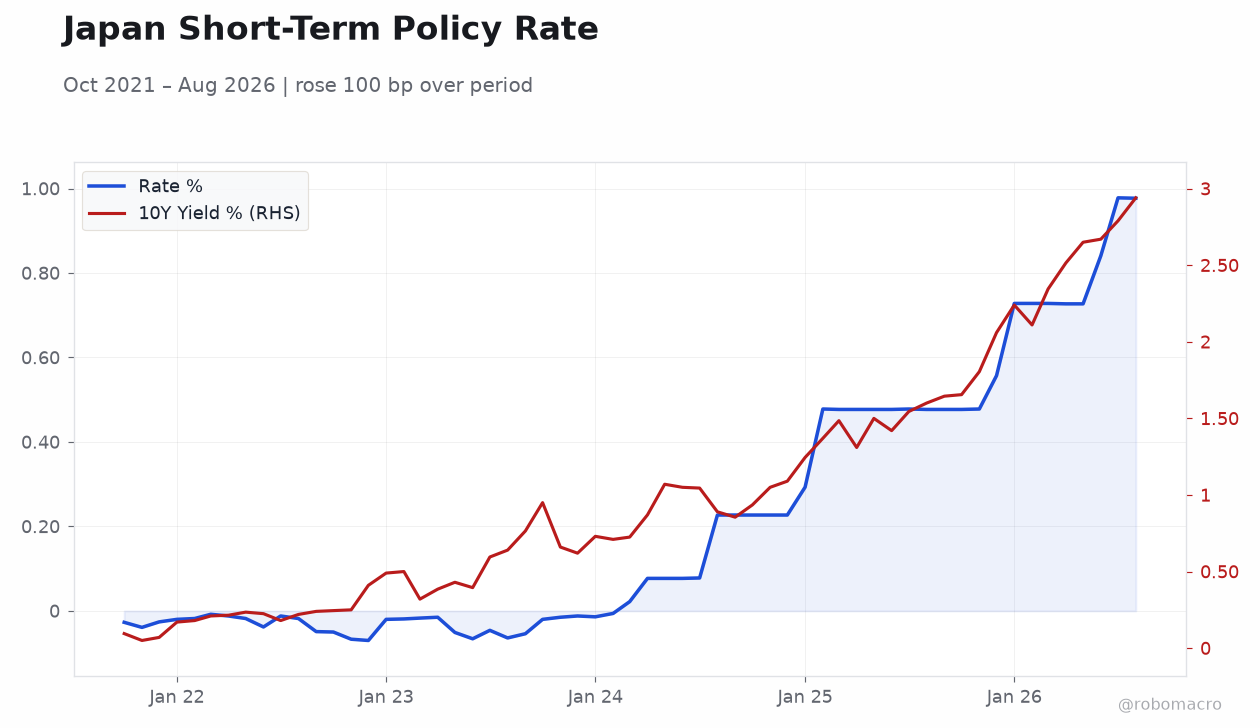
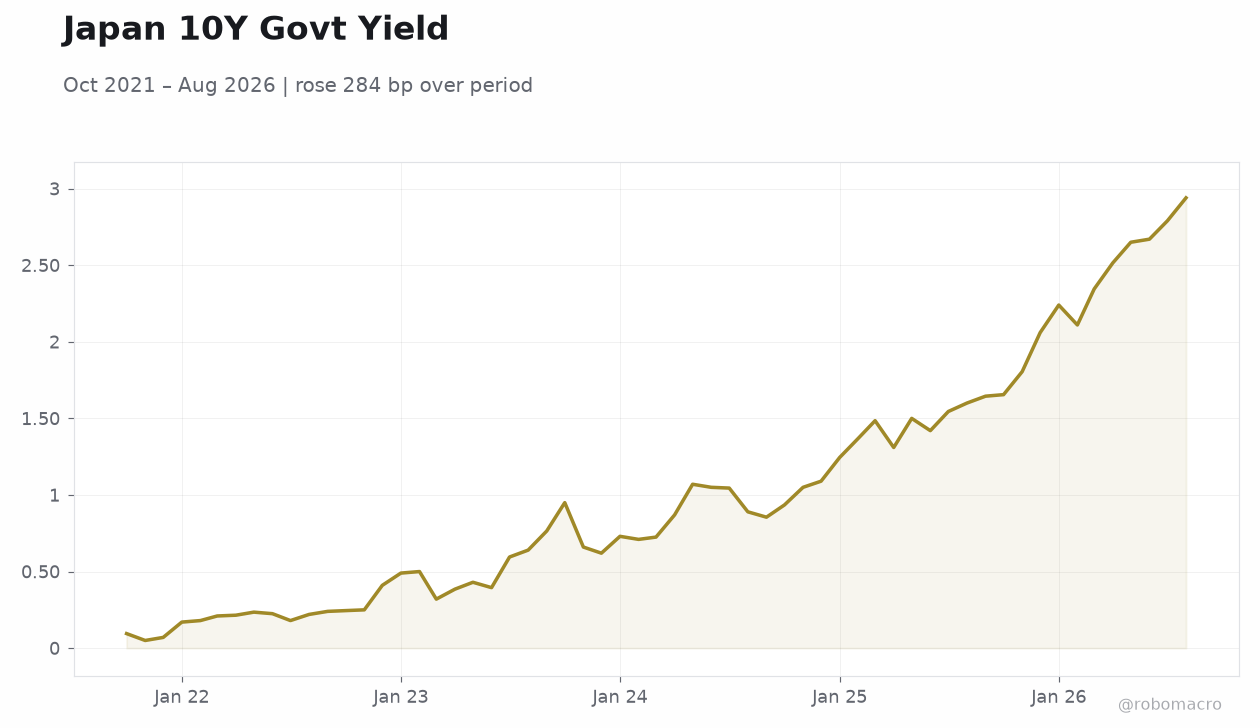 Japan 10Y Govt Yield | Type: macro_line | Yield %: 2.94 (2026-08-01) | Range: 0.05–2.94 | Trend(6pt): 0.095,0.41,0.71,1.31,2.67,2.94
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tankan Large Manufacturers Index | 22 | 25 | 15:50 |
| BoJ Summary of Opinions | - | - | 15:50 |
| Thursday (2026-10-01) | |||
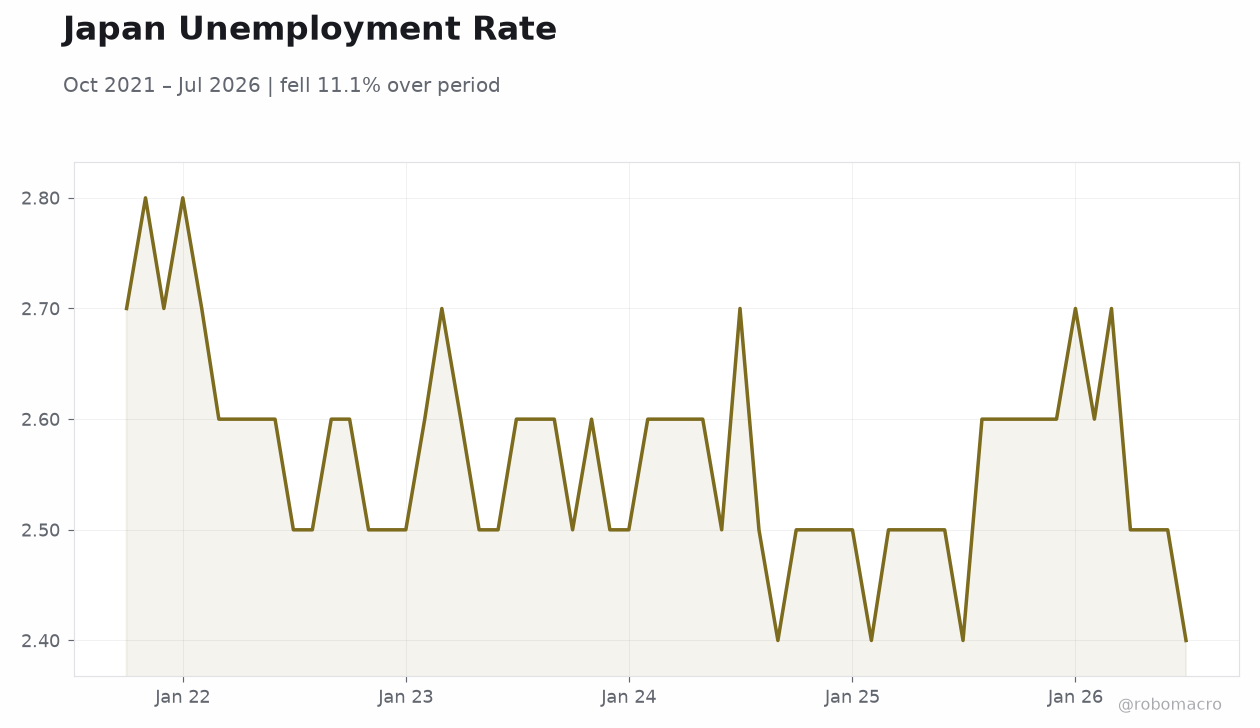
| Headline Unemployment Rate | 2.40 | 2.40 | 15:30 |
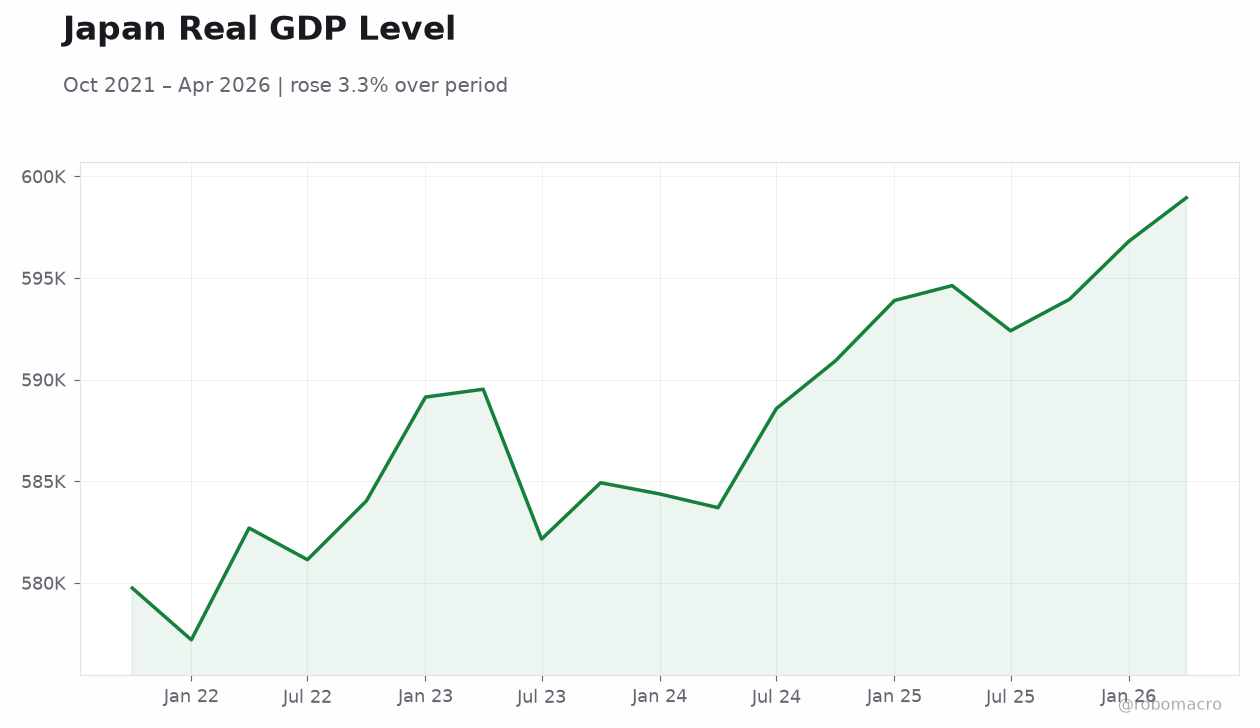
- Industrial production fell 1.7% MoM, well below consensus.
- Retail sales growth slowed to 2.7% YoY from 3.7%.
- Tankan Large Manufacturers Index and BoJ Summary of Opinions due today.
Yesterday's Recap
Japanese industrial production contracted 1.7% month-over-month in the preliminary September reading, missing the 1.7% consensus and following a 0.2% decline previously. Retail sales rose 2.7% year-over-year, below the 3.3% expected and 3.7% prior print. Housing starts increased 6.1% year-over-year, softer than the 7.0% consensus and 8.2% earlier figure.
The Nikkei 225 fell 0.60% to 65,481.27 while USD/JPY held at 157.41. The Japan 2-year government yield rose 3 basis points to 1.98% and the 10-year yield stayed at 3.08%. Markets showed muted reaction to the soft data releases amid reports that authorities paused forex intervention after modest yen strength.
The yen reached a two-week high, reducing immediate pressure on the currency. Japanese economic panel members repeatedly emphasised the Bank of Japan’s independence while noting the need for government coordination. The currency remains viewed as undervalued from Tokyo’s perspective, leaving intervention risk intact on renewed weakness.
The Day Ahead
The Tankan Large Manufacturers Index for September is scheduled for release at 15:50 JST with consensus at 25 versus the prior 22. The BoJ Summary of Opinions will be published at the same time and is expected to provide further colour on policy views. Markets will assess whether the soft production and consumption figures alter corporate sentiment captured in the Tankan survey.
The unemployment rate is due tomorrow at 15:30 JST with consensus unchanged at 2.4%. Attention will remain on any signals regarding the timing of further policy adjustments.
Other Economic Notes
Japanese economic panel members stressed the Bank of Japan’s institutional independence while calling for continued government coordination. Reports indicated authorities paused yen-buying intervention following the currency’s modest strengthening. The yen remains viewed as undervalued in Tokyo, leaving intervention risk intact on renewed weakness.
Broader commentary highlighted that recent data softness may temper near-term expectations for additional rate increases. Citi analysts flagged potential intervention around 160 should USD/JPY test higher. UK growth outperformance supported sterling against the yen.