Japan Macro Daily(Beta Mode)
Soft Data Weighs on BOJ Hike Bets
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 66,753.72 | +1.94% |
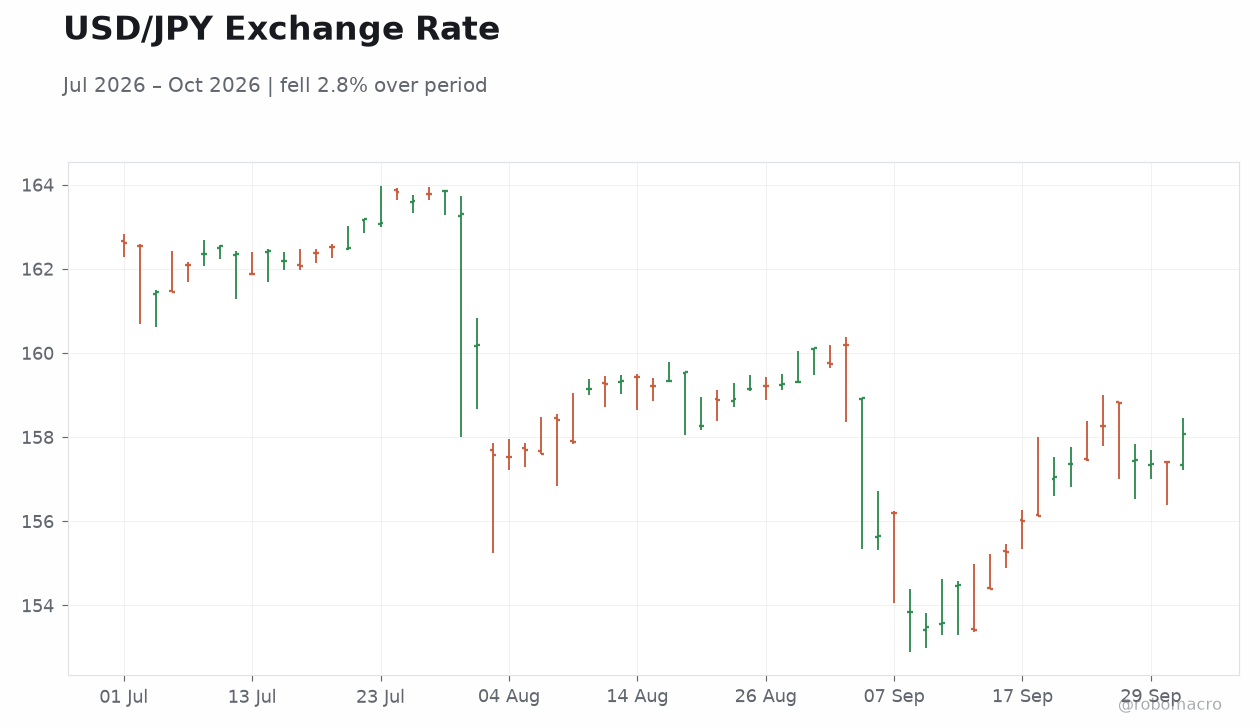
| USD/JPY | 158.11 | +0.35% |
| EUR/JPY | 177.53 | -0.53% |
| GBP/JPY | 208.60 | -0.18% |
| Gold | 4,209.00 | +0.53% |
| Brent Crude | 102.22 | -1.27% |
| Bitcoin | 84,608.33 | +1.26% |
| Japan 2Y Govt Yield | 1.98% | 0 bp |
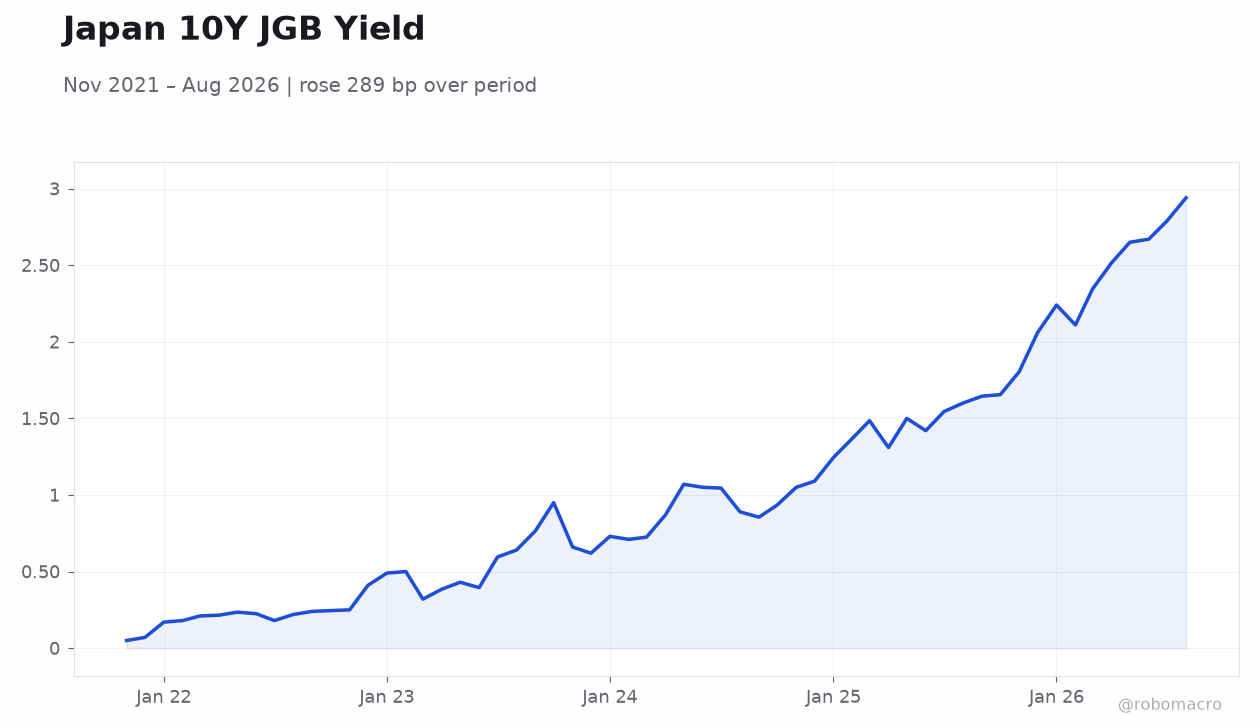
| Japan 10Y Govt Yield | 3.06% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Month-over-Month Preliminary | -0.20 | 1.70 | -1.70 |
| Retail Sales Year-over-Year | 3.70 | 3.30 | 2.70 |
| Housing Starts Year-over-Year | 8.20 | 7 | 6.10 |
| Tankan Large Manufacturers Index | 22 | 25 | 24 |
| BoJ Summary of Opinions | - | - | - |
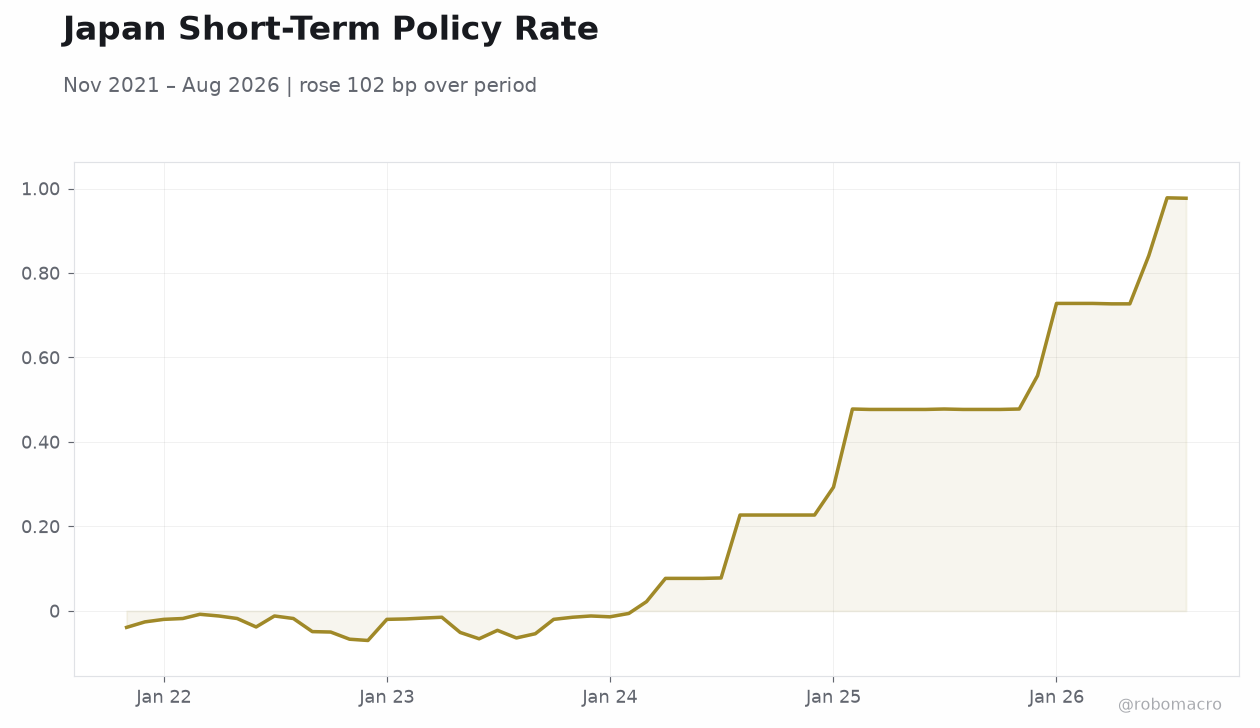 Japan Short-Term Policy Rate | Type: macro_line | %: 0.977 (2026-08-01) | Range: -0.07–0.978 | Trend(6pt): -0.039,-0.02,0.022,0.477,0.978,0.977
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
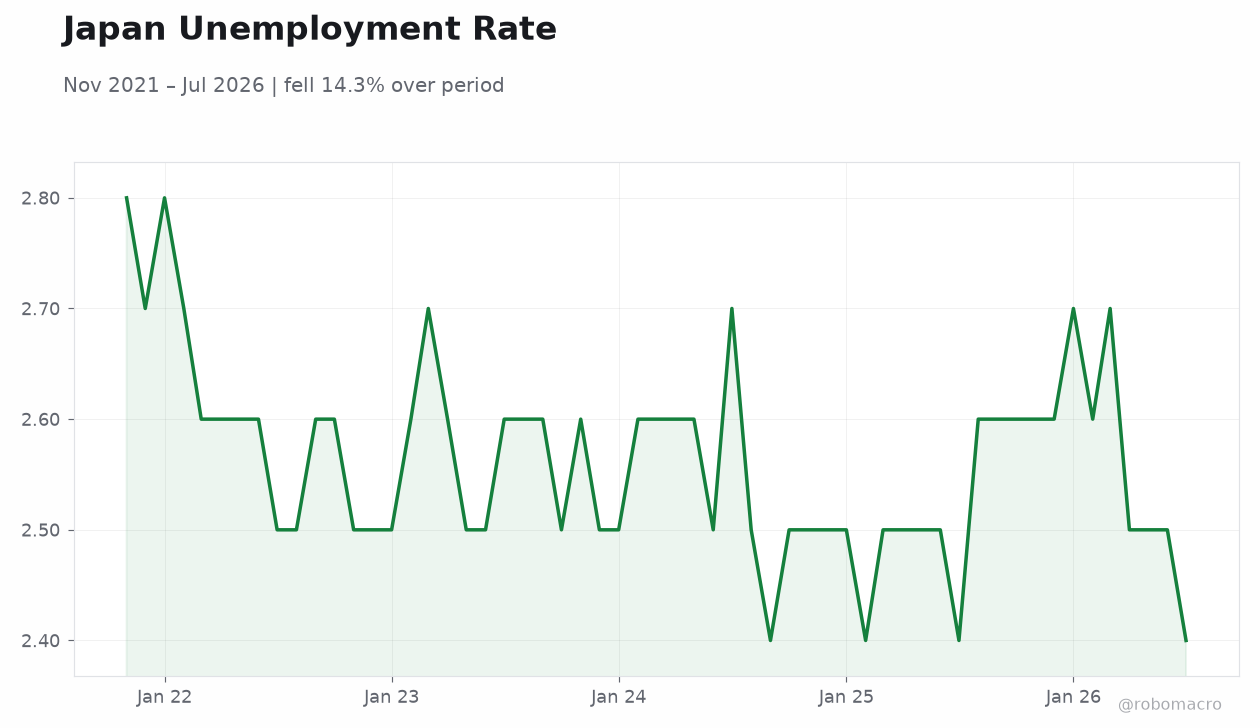
| Headline Unemployment Rate | 2.40 | 2.40 | 15:30 |
- Industrial production contracted 1.7% MoM against 1.7% consensus, while retail sales slowed to 2.7% YoY.
- Tankan large manufacturers index reached 24, close to the 25 forecast, signalling resilient business sentiment.
- Japan paused forex intervention after modest yen gains, with the 10-year JGB yield easing 2 bp to 3.06%.
Yesterday's Recap
Industrial production printed -1.7% month-over-month, well below the 1.7% consensus and prior -0.2% reading, while retail sales rose only 2.7% year-over-year versus 3.3% expected. Housing starts also disappointed at 6.1% year-over-year. The Tankan large manufacturers index edged to 24 from 22, just short of the 25 consensus, indicating steady but not accelerating optimism.
The Bank of Japan released its Summary of Opinions alongside the data. Nikkei 225 rose 1.94% to 66,753.72 and USD/JPY climbed 0.35% to 158.11. The 10-year JGB yield fell 2 bp to 3.06% while the 2-year yield held at 1.98%.
Markets priced reduced odds of consecutive rate hikes after the summary release.
The Day Ahead
Headline unemployment rate is scheduled for release at 15:30 JST with consensus unchanged at 2.4%. No other high-impact Japanese data or Bank of Japan speeches appear on the calendar. Traders will monitor any deviation that could alter near-term policy expectations.
The single print is unlikely to shift pricing materially unless it surprises sharply. Attention remains on yen direction and any follow-up comments from officials.
Other Economic Notes
Economic panel members repeatedly stressed Bank of Japan independence while calling for continued government coordination. Sanae Takaichi pledged measures to restore confidence in the weak yen. The finance minister reported President Trump’s concerns over yen weakness.
Japan paused forex intervention once the currency strengthened modestly. Nidec recorded a $3.6 billion loss tied to EV motor write-downs, highlighting sector-specific pressures amid broader yen volatility.
Global Macro News
Higher US yields offset hawkish elements in the Bank of Japan summary and contributed to further yen softening. Trump’s expressed concerns about yen weakness added external political pressure on Japanese policymakers. Australian dollar strength against the yen followed better-than-expected trade data from Australia.
↓ p.2