Japan Macro Daily(Beta Mode)
Weak Data Eases BoJ Tightening Pressure
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 68,309.46 | -0.94% |
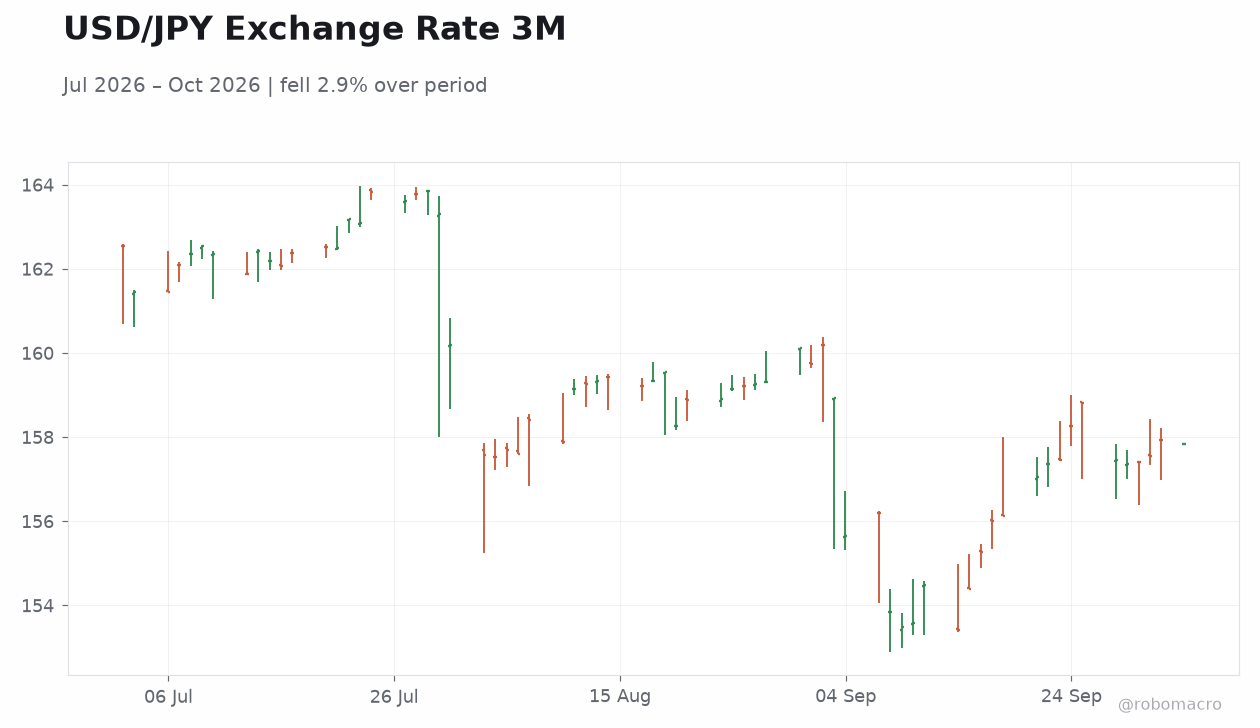
| USD/JPY | 157.83 | -0.06% |
| EUR/JPY | 177.30 | -0.18% |
| GBP/JPY | 209.07 | +0.32% |
| Gold | 4,162.30 | -0.95% |
| Brent Crude | 102.25 | -0.06% |
| Bitcoin | 85,790.83 | +1.21% |
| Japan 2Y Govt Yield | 1.94% | -4 bp |
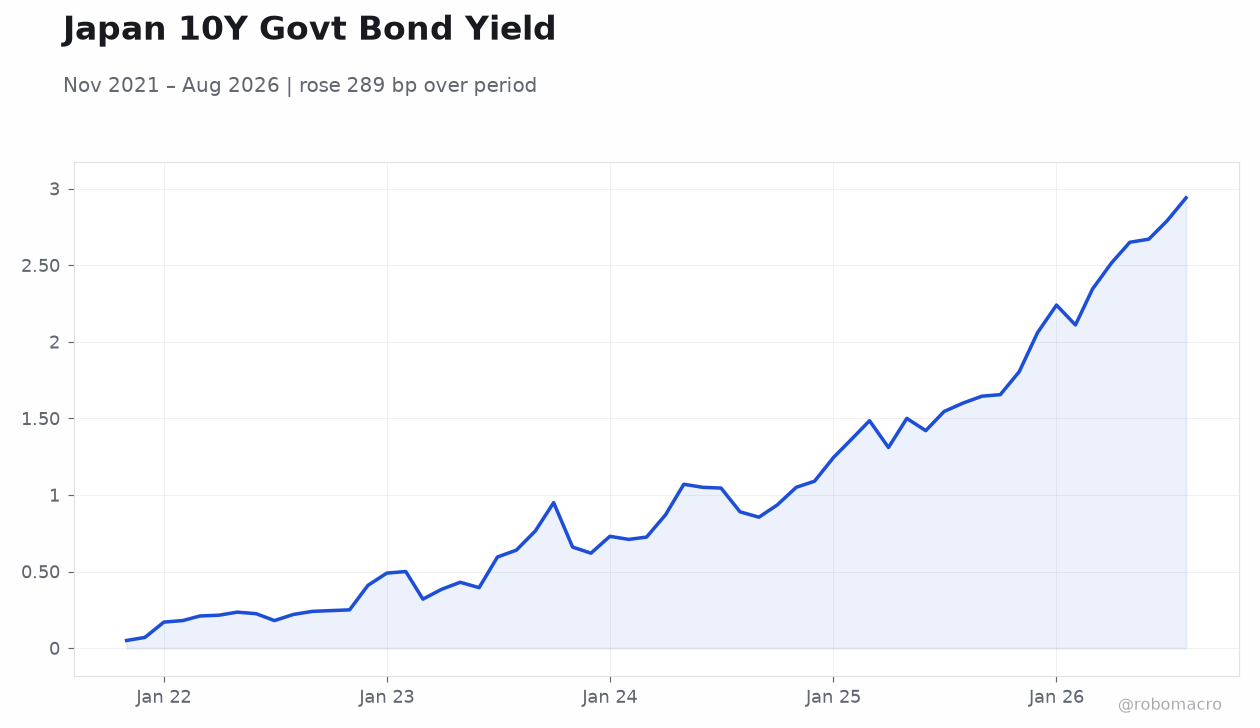
| Japan 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Industrial Production Month-over-Month Preliminary | -0.20 | 1.70 | -1.70 |
| Retail Sales Year-over-Year | 3.70 | 3.30 | 2.70 |
| Housing Starts Year-over-Year | 8.20 | 7 | 6.10 |
| Tankan Large Manufacturers Index | 22 | 25 | 24 |
| BoJ Summary of Opinions | - | - | - |
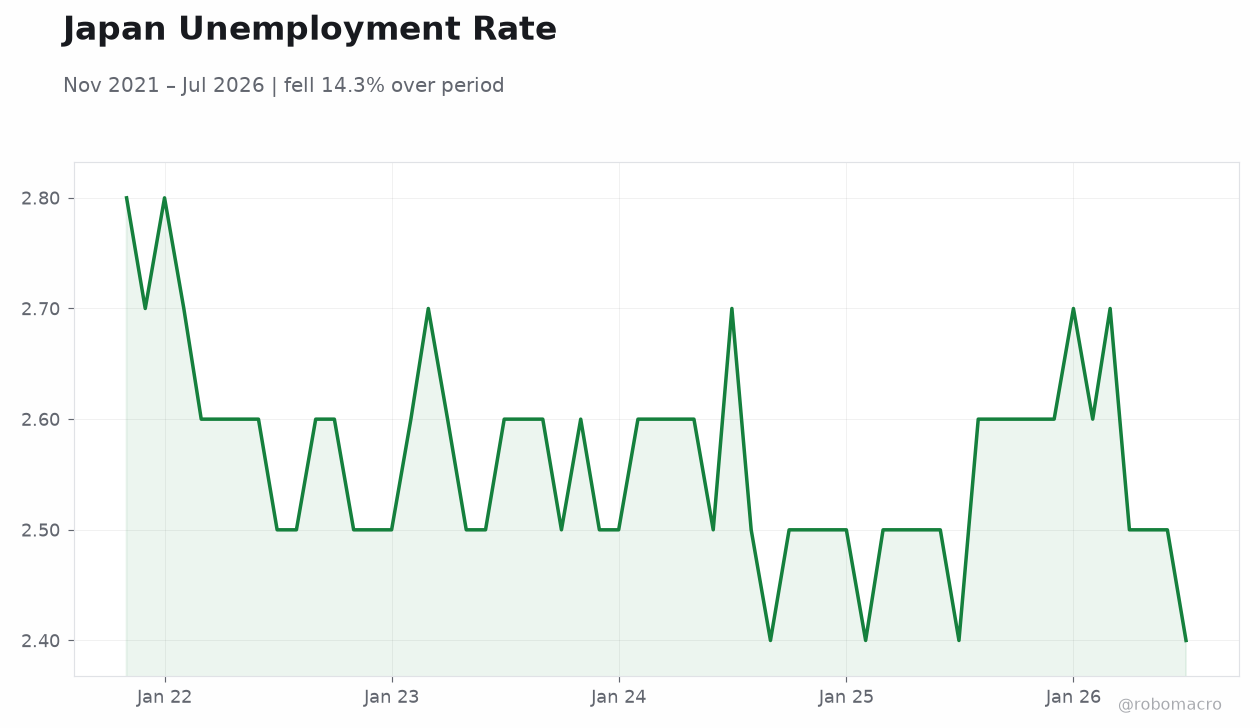
| Headline Unemployment Rate | 2.40 | 2.40 | 2.50 |
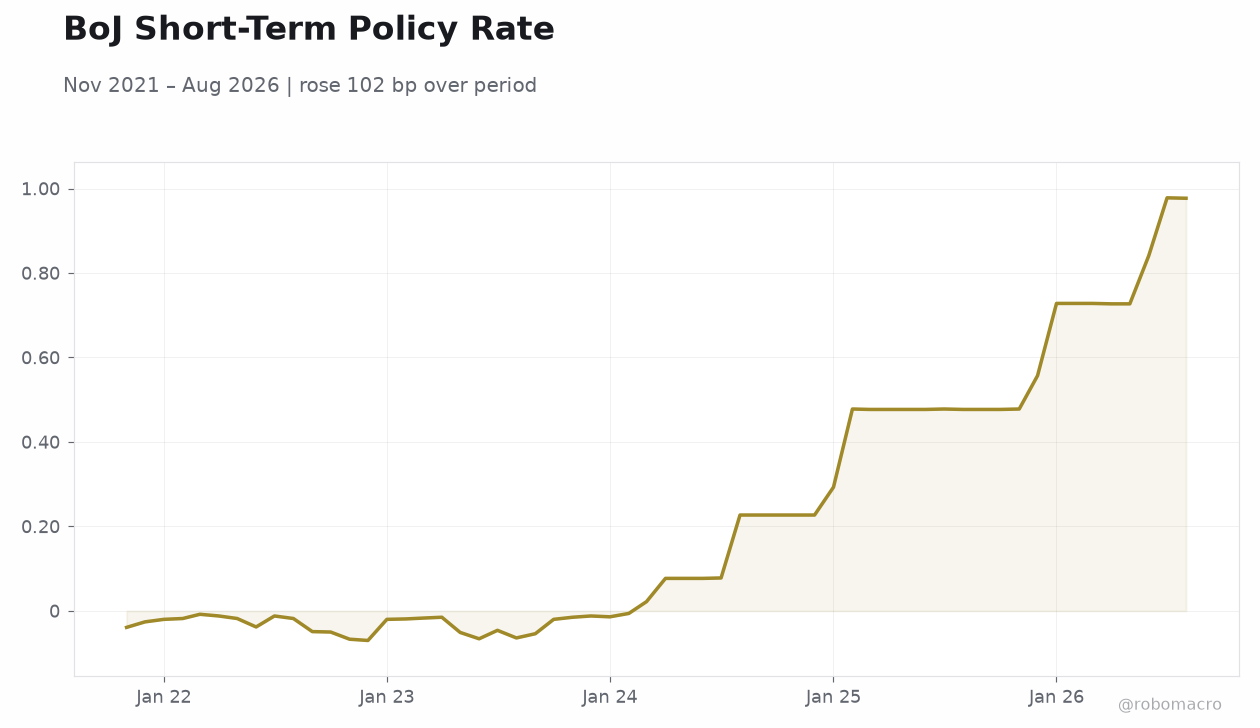 BoJ Short-Term Policy Rate | Type: macro_line | Rate %: 0.977 (2026-08-01) | Range: -0.07–0.978 | Trend(6pt): -0.039,-0.02,0.022,0.477,0.978,0.977
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Industrial production plunged 1.7% month-over-month against 1.7% consensus
- Tankan large manufacturers index rose to 24, below 25 expected
- Finance minister signals end of reflation era and yen stability focus
Yesterday's Recap
Japan’s industrial production contracted 1.7% month-over-month in September, missing the 1.7% consensus and reversing the prior -0.2% reading. Retail sales grew 2.7% year-over-year, below the 3.3% forecast and prior 3.7%. Housing starts rose 6.1% year-over-year versus 7.0% expected.
The Tankan large manufacturers index reached 24, short of the 25 consensus though above the prior 22. Unemployment edged up to 2.5% from 2.4%. The Bank of Japan released its Summary of Opinions alongside the data.
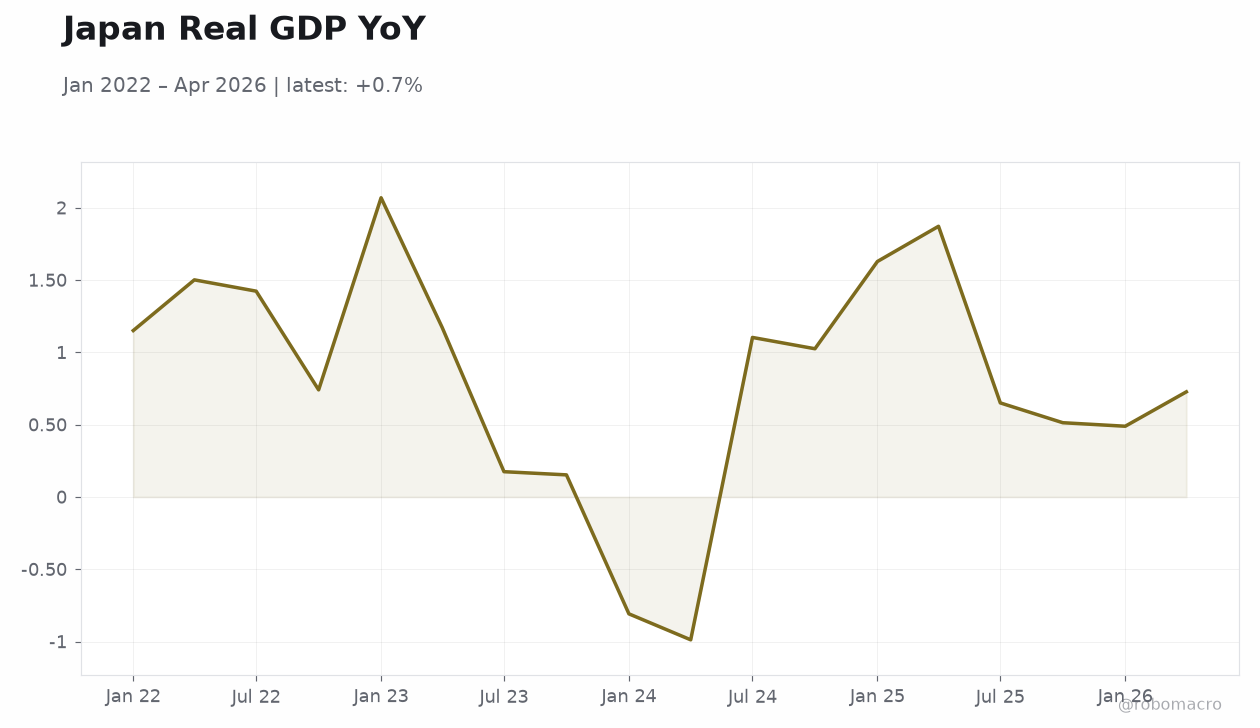
Markets responded with the Nikkei 225 falling 0.94% to 68,309.46 and the 2-year JGB yield declining 4 basis points to 1.94%. USD/JPY held near 157.83. The cluster of misses, especially the sharp drop in industrial production and softer retail and housing prints, points to softer momentum than markets had priced.
The modest Tankan beat versus prior was still below consensus. These outcomes are likely to temper expectations for near-term Bank of Japan tightening and reduce pressure on JGB yields and the yen.
The Day Ahead
No economic releases or Bank of Japan events are scheduled for October 4 or 5. Traders will monitor any follow-up comments from officials on the Summary of Opinions. Attention may shift to global risk sentiment and US data that could influence yen flows.
Market participants will assess whether the recent data cluster alters pricing for the next policy meeting. Yen volatility could remain contained pending further fiscal or trade-related statements from Tokyo and Washington.
Other Economic Notes
Long-term JGB yields have risen amid concerns over fiscal credibility, prompting calls for stronger budget discipline. Japan’s CPI stood at 1.90% year-over-year in August, supporting the view that the deflation era has ended. Officials have stressed that excessively loose monetary policy is no longer required.
These developments coincide with the 2-year yield at 1.94% and the policy rate at 1.25%. Sustained higher rates could pressure government borrowing costs if growth momentum stays soft.