RoboMacro ResearchAlso todaySee the Equities Daily

Japan Macro Daily(Beta Mode)

October 13, 2026 robomacro.com

JGBs Rally, Yen Firms Ahead of Koeda

Nikkei 22569,030.92-0.02%
USD/JPY158.33-0.12%
EUR/JPY177.25+0.19%
GBP/JPY209.78+0.18%

Market Snapshot

AssetLevelChange
Nikkei 22569,030.92-0.02%
USD/JPY158.33-0.12%
EUR/JPY177.25+0.19%
GBP/JPY209.78+0.18%
Gold4,182.00-0.21%
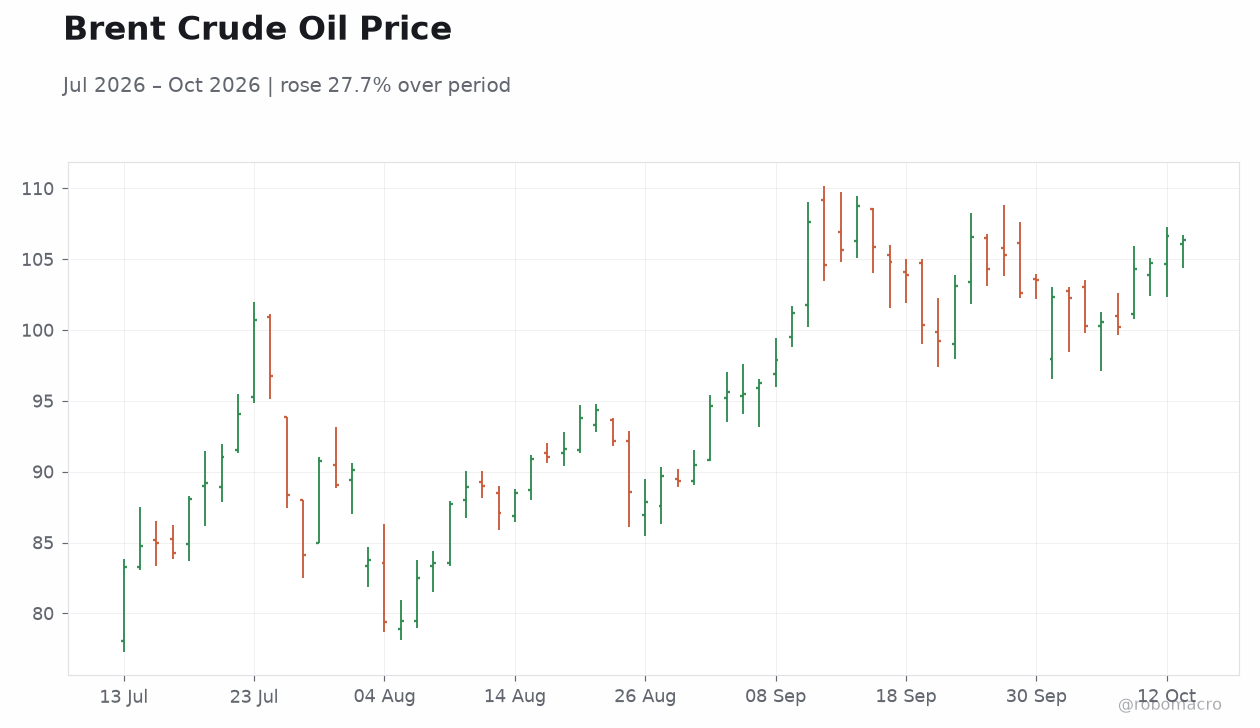
Brent Crude106.38-0.25%
Bitcoin83,343.37+1.93%
Japan 2Y Govt Yield1.91%-3 bp
Japan 10Y Govt Yield3.03%-6 bp

Prior Economic Events

Data Prior Cons Actual
No events available
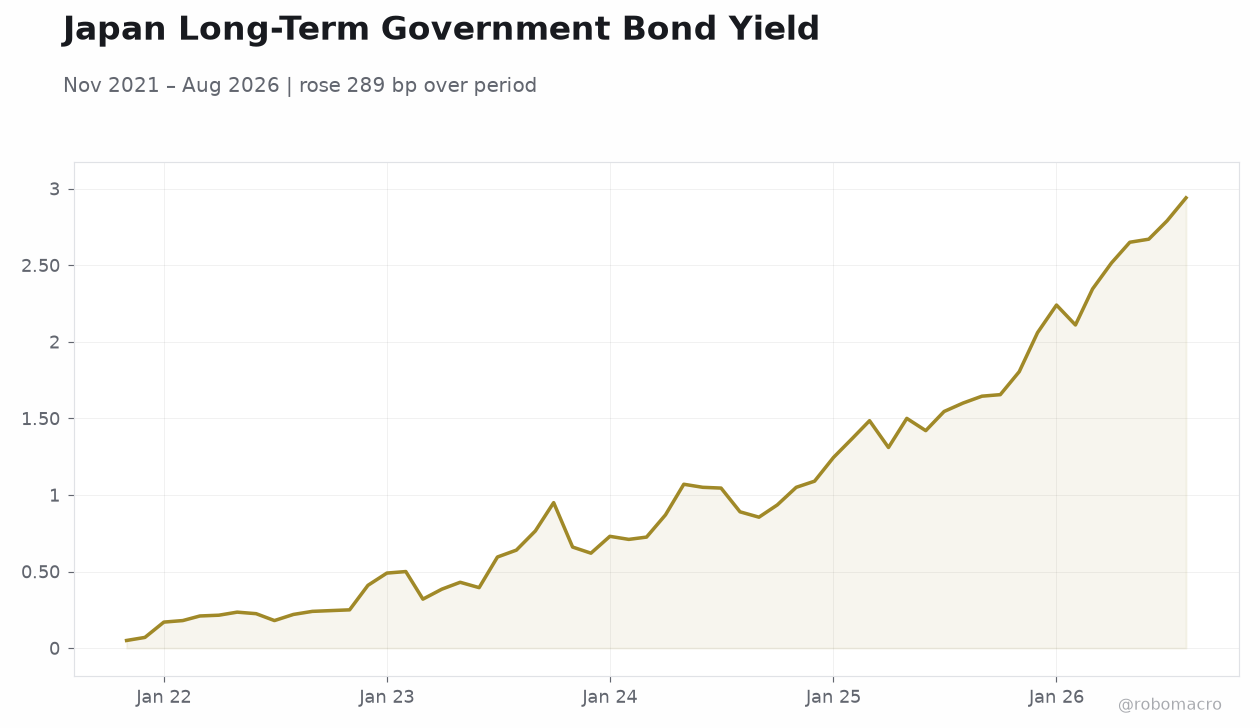
Japan Long-Term Government Bond YieldJapan Long-Term Government Bond Yield | Type: macro_line | 10Y JGB Yield (%): 2.94 (2026-08-01) | Range: 0.05–2.94 | Trend(6pt): 0.05,0.49,0.725,1.5,2.79,2.94

Today's Economic Events

Data Prior Cons Time
Wednesday (2026-10-14)
Machinery Orders Month-over-Month-3.702.5019:50
Machinery Orders Year-over-Year11.20-19:50
BoJ Koeda Speech--21:30
  • 10-year JGB yield eased 6 bp to 3.03% and the 2-year slipped 3 bp to 1.91% as bonds rallied into a heavy data week
  • September PPI cooled on a firmer yen and softer oil, but wholesale inflation remains elevated enough to keep rate-hike expectations alive
  • Machinery orders and a speech from BoJ board member Koeda headline Wednesday's calendar

Yesterday's Recap

Tokyo trading on Monday was quiet and tilted slightly risk-off, with the Nikkei 225 essentially flat at 69,030.92, down just 0.02%. The government bond market did the heavy lifting: the 10-year JGB yield eased 6 bp to 3.03% and the 2-year fell 3 bp to 1.91%, a bull-steepening move consistent with position squaring rather than fresh macro information. In FX, USD/JPY slipped 0.12% to 158.33, while the yen gained against the euro, with EUR/JPY up only 0.19% at 177.25 after a bout of euro weakness tied to stagflation concerns in the euro area.

GBP/JPY held near 209.78. The yen's firmer footing came despite a mixed commodity backdrop — Brent crude slipped 0.25% to $106.38 and gold lost 0.21% to $4,182 — with markets weighing intervention risk against the dollar's grind higher. Bitcoin's 1.93% jump to 83,343 signalled residual risk appetite in pockets of the complex.

September's corporate goods price data, released late last week, showed wholesale inflation cooling more than expected on the stronger yen and retreating energy costs, yet the level remains high enough to underpin the case for further normalisation. With no calendar prints due Monday, attention has already rotated to Wednesday's machinery orders and Koeda's remarks.

The Day Ahead

Wednesday brings the first tier-one domestic prints in over a week. Machinery orders are forecast to rebound 2.5% month-over-month in August after a 3.7% contraction, a swing that matters for the capex narrative underpinning the wage-price cycle; the year-on-year comparison sits against an 11.2% base. At 21:30 ET, board member Koeda speaks — a high-impact event given her policy committee seat and the market's hunger for signals on the timing of the next move.

Any explicit discussion of the pace of hikes past the current 1.25% policy rate would move the front end of the JGB curve and USD/JPY. Also watch for colour on the balance of risks around the October meeting, where reports suggest the BoJ leans against back-to-back tightening. The session sets up the rest of the week's data flow and the tone for yen carry dynamics into month-end.

Page 1

Japan Macro Daily(Beta Mode)

October 13, 2026 robomacro.com
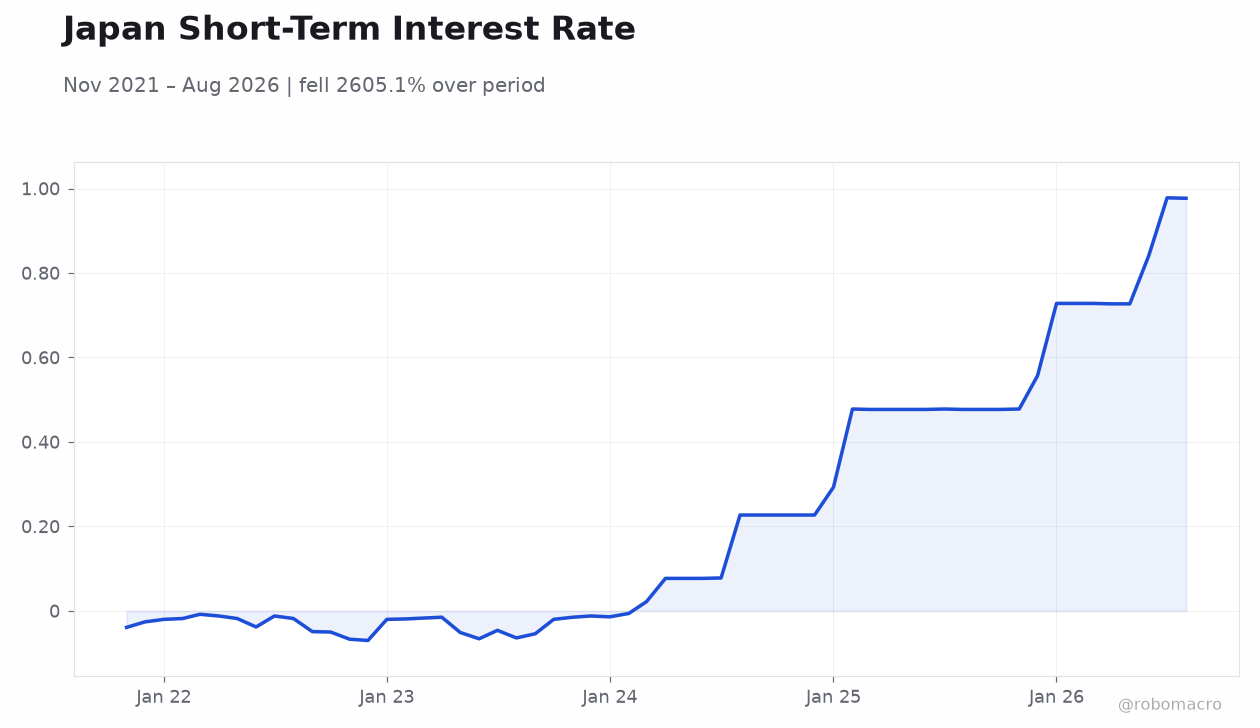
Japan Short-Term Interest Rate Japan Short-Term Interest Rate | Type: macro_line | Short-Term Rate (%): 0.977 (2026-08-01) | Range: -0.07–0.978 | Trend(6pt): -0.039,-0.02,0.022,0.477,0.978,0.977
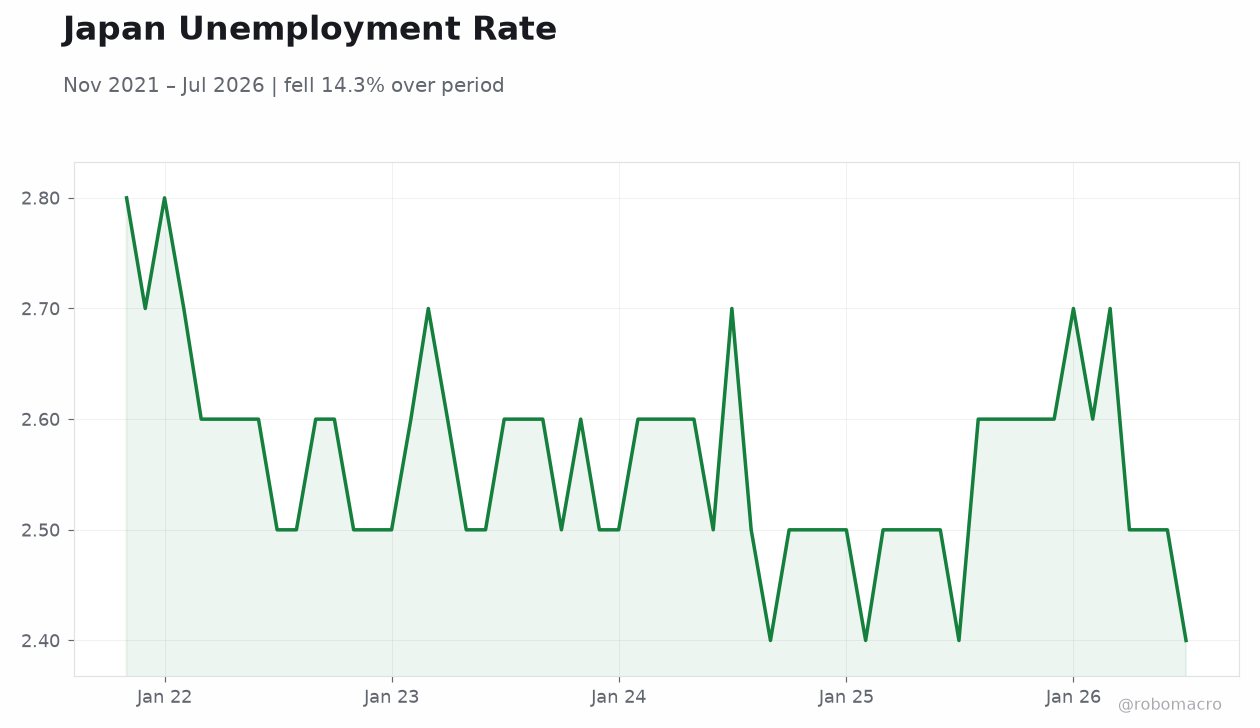
Japan Unemployment Rate Japan Unemployment Rate | Type: macro_line | Unemployment Rate (%): 2.4 (2026-07-01) | Range: 2.4–2.8 | Trend(5pt): 2.8,2.5,2.6,2.5,2.4
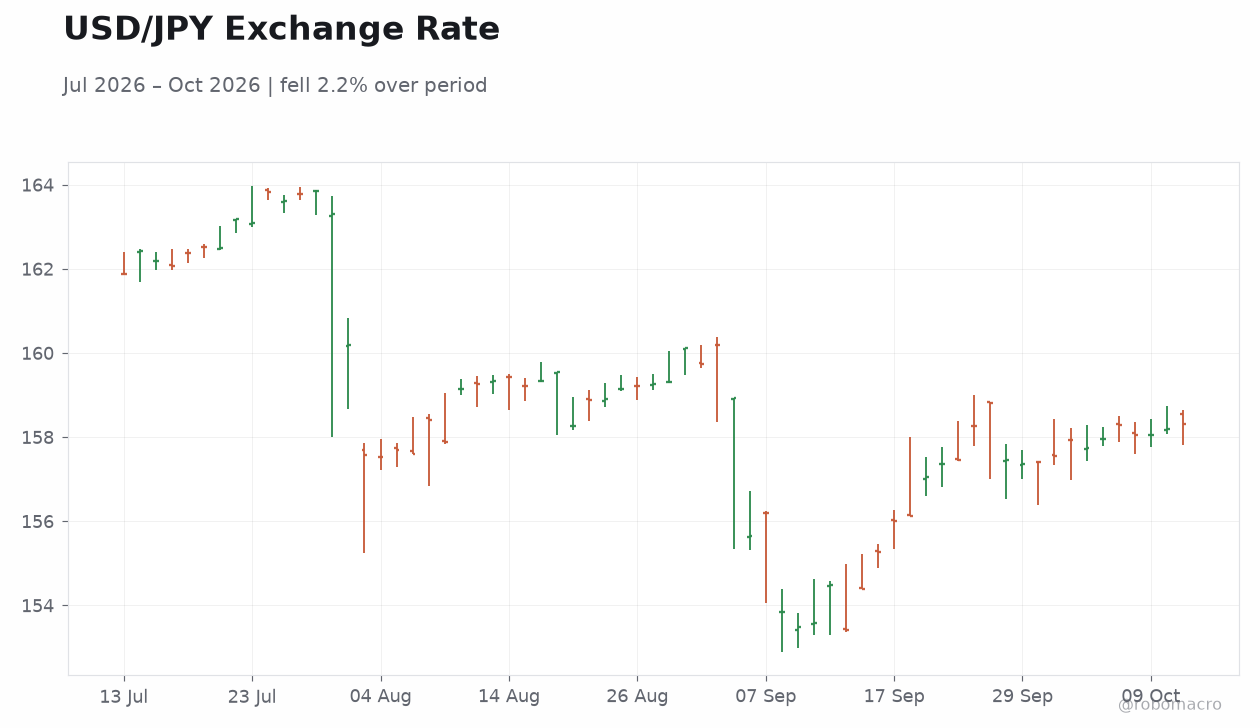
USD/JPY Exchange Rate USD/JPY Exchange Rate | Type: market_hloc | USD/JPY: 158.3 (2026-10-13) | Range: 153.4–163.9 | Trend(6pt): 161.9,157.5,159.2,156,158.1,158.3
Brent Crude Oil Price Brent Crude Oil Price | Type: market_hloc | Brent ($/bbl): 106.3 (2026-10-13) | Range: 79.36–108.8 | Trend(6pt): 83.3,79.36,87.84,103.9,106.7,106.3

Other Economic Notes

The fiscal dimension is re-entering the rates conversation, with commentary highlighting tension between the BoJ's tightening path and government borrowing needs — a dynamic that historically caps how far long-end yields can rally on monetary policy alone. Bank equity has been a clear beneficiary of the regime shift, with screens of lenders positioned for higher rates and a weaker yen attracting flows. The IMF's interim projections frame the macro backdrop: growth slowing to 0.7% in 2026 even as the policy rate grinds toward neutral, a combination that argues for a gradual hiking cadence rather than a front-loaded cycle.

Wholesale price resilience despite yen strength suggests pass-through into services inflation remains intact.

Global Macro News

The dollar's bid remains the dominant cross-market force, with USD/JPY grinding near the 200-day average and technical analysts flagging breakout risk on a sustained close above. Oil's rally has complicated the picture for import-sensitive Japan, supporting the yen-weakness narrative through the terms-of-trade channel even as headline energy costs cool domestically. In Europe, stagflation fears have undermined the euro, indirectly boosting the yen on crosses and reinforcing the view that Japan's relative policy-normalisation story still has legs.

The Bank of Korea's pledge to keep policy restrictive for now offers a regional read-across, underscoring that Asia's normalisation cycle remains incomplete and uneven. The BoE's Greene advocating faster hikes keeps global rate differentials wide, sustaining carry-trade appeal for the yen's funding role. ↓ p.3

Sponsored by Arbitrage Search
Page 2

Japan Macro Daily(Beta Mode)

October 13, 2026 robomacro.com

Continuation

Global Macro News (continued)

Geopolitically, Japan and the US are reviewing conduct codes for American troops in Okinawa, a low-market-impact item but one relevant to the bilateral relationship underpinning the security and trade agenda. Gold's retreat from record territory and Bitcoin's rebound round out a mixed risk ledger.

BoJ Watch

The policy rate stands at 1.25% following the most recent move, and the communications pattern suggests the board is in no rush to deliver consecutive hikes. Press reports indicate the BoJ leans against back-to-back tightening in October, consistent with the gradualist approach the IMF projects toward neutral. Yet the hawkish counterpoint persists: wholesale inflation remains elevated, and commentary has flagged the bank's readiness to move faster if price pressures broaden — a signal that the optionality, not the destination, has changed.

Koeda's Wednesday remarks will be parsed for exactly that nuance: whether the bar for a December or January move has lowered. The front-end's 3 bp decline to 1.91% suggests markets have modestly pared near-term hike odds, while the long end's rally to 3.03% reflects fiscal-supply and growth concerns as much as monetary expectations. With the yen recovering from pressured levels, the immediate case for intervention support has faded, giving the bank room to let the currency find its level.

Watch the spread between policy rhetoric and the 2s10s at 112 bp for the cleanest read on normalisation pacing.

Sponsored by Arbitrage Search
Page 3