RoboMacro ResearchAlso todaySee the VIX Daily

Japan Macro Daily(Beta Mode)

October 23, 2026 robomacro.com

CPI Tops Target, Yen Rallies on Hike Bets

Nikkei 22562,907.84-2.65%
USD/JPY156.90-0.78%
EUR/JPY175.60-1.16%
GBP/JPY209.75-0.97%

Market Snapshot

AssetLevelChange
Nikkei 22562,907.84-2.65%
USD/JPY156.90-0.78%
EUR/JPY175.60-1.16%
GBP/JPY209.75-0.97%
Gold4,011.40-1.21%
Brent Crude111.47-1.50%
Bitcoin81,493.62+0.22%
Japan 2Y Govt Yield1.91%0 bp
Japan 10Y Govt Yield2.91%-1 bp

Prior Economic Events

Data Prior Cons Actual
No events available
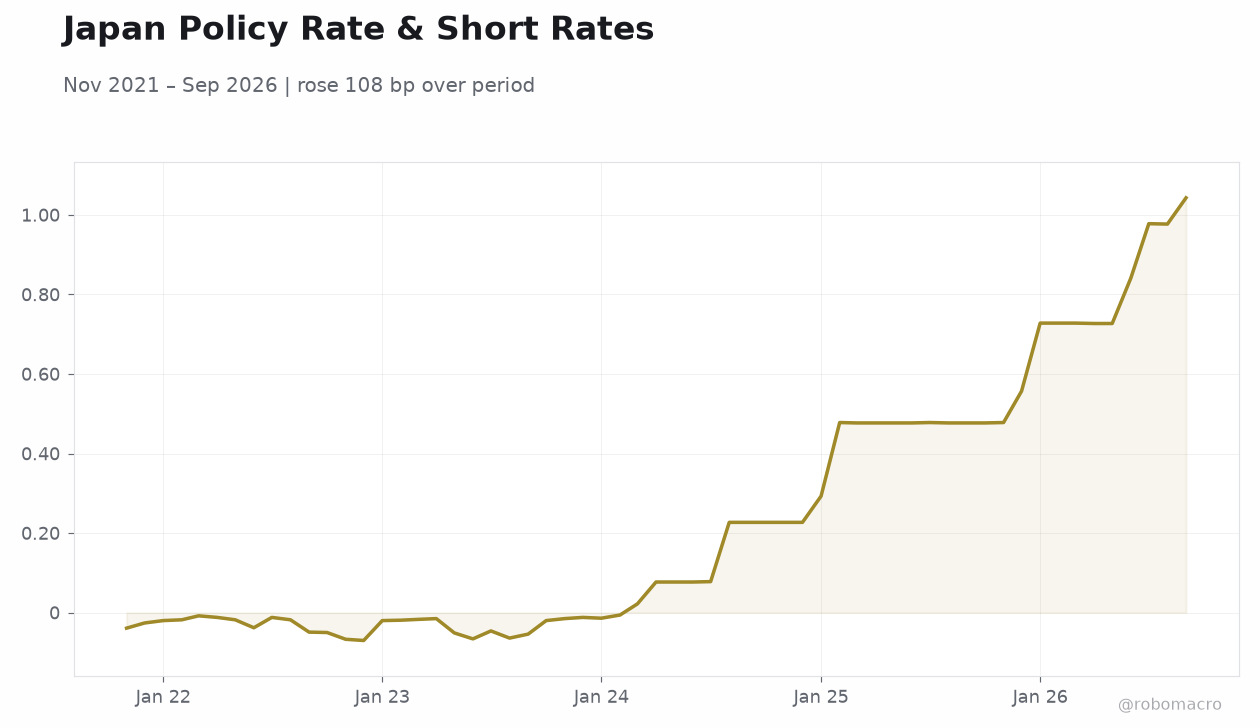
Japan Policy Rate & Short RatesJapan Policy Rate & Short Rates | Type: macro_line | Short-term Rate %: 1.043 (2026-09-01) | Range: -0.07–1.043 | Trend(6pt): -0.039,-0.02,0.022,0.477,0.978,1.043

Today's Economic Events

Data Prior Cons Time
No events available
  • Japan September CPI exceeded the BoJ’s 2% target for the first time this year, reinforcing expectations for a near-term policy rate increase.
  • The yen strengthened against the dollar while the Nikkei 225 declined sharply amid exporter concerns over higher borrowing costs.
  • JGB yields held steady with the 10-year easing 1 bp, reflecting measured market digestion of inflation data ahead of upcoming central bank meetings.

Yesterday's Recap

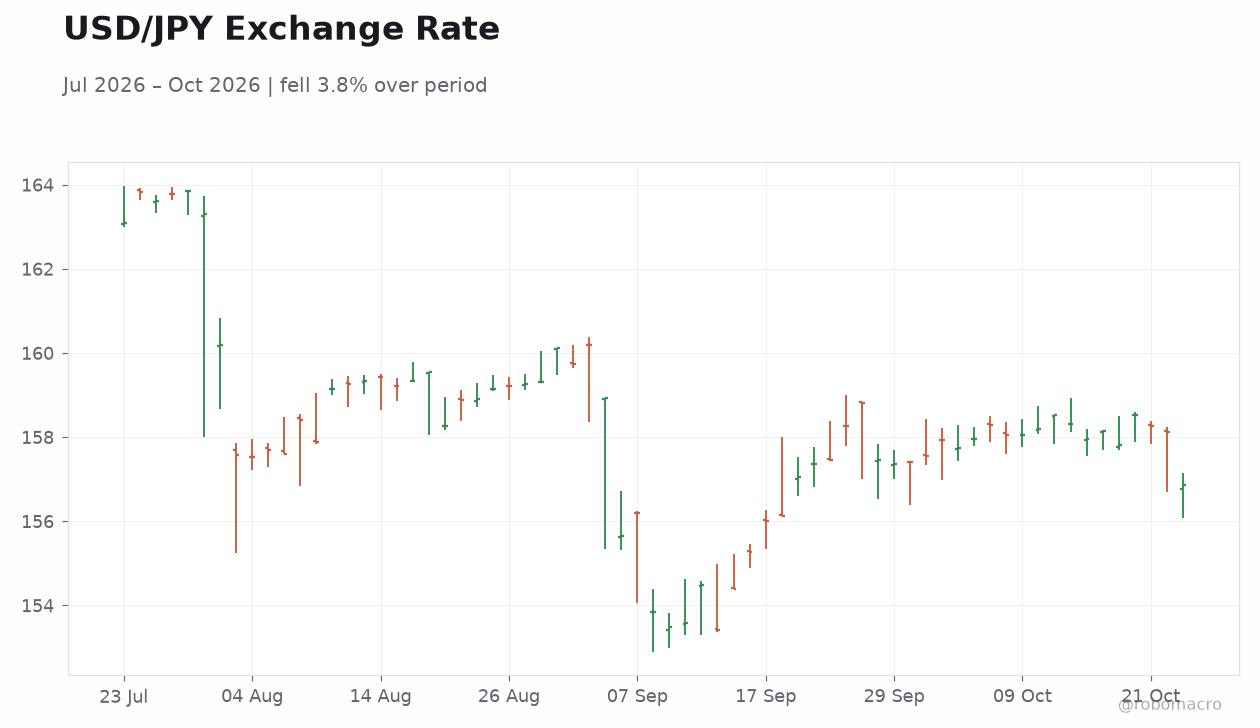
Japanese markets reacted to September CPI data showing inflation above the BoJ target for the first time in 2026. The Nikkei 225 fell 2.65% to close at 62,907.84 as exporters faced pressure from yen appreciation and rate-hike expectations. USD/JPY dropped 0.78% to 156.90, with the yen also advancing against the euro and sterling.

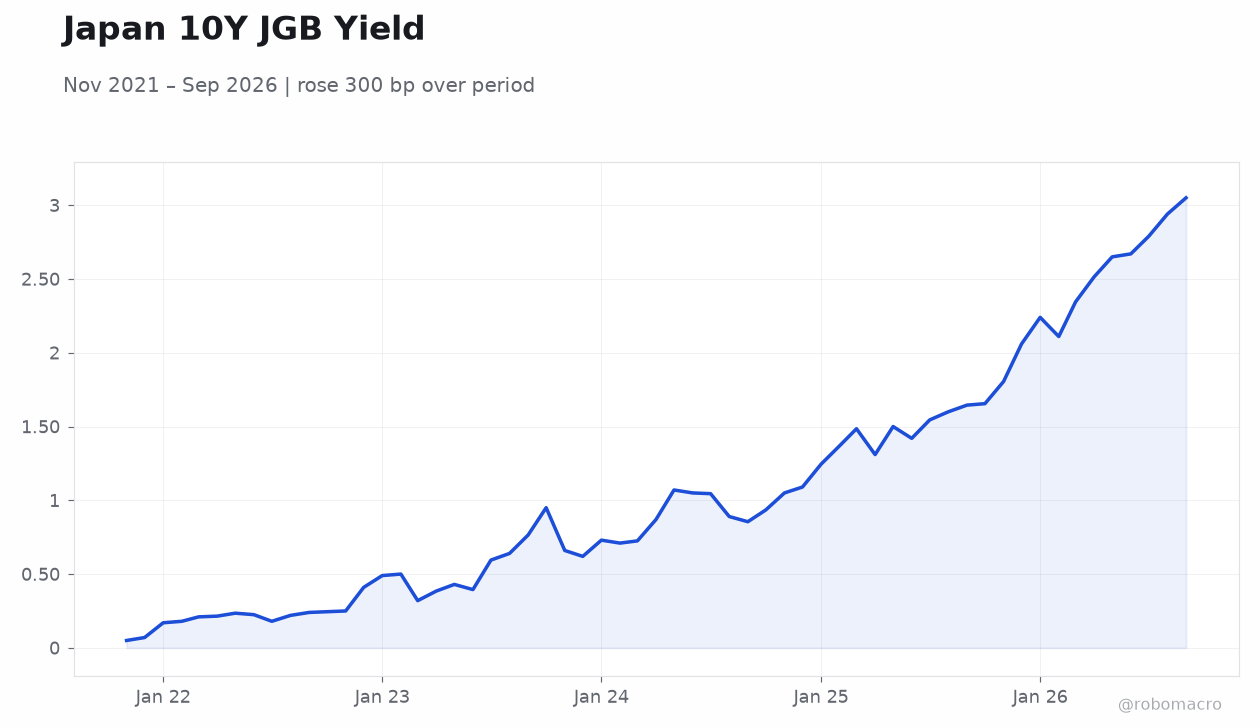
The 10-year JGB yield eased 1 bp to 2.91% while the 2-year yield remained unchanged at 1.91%. News flow highlighted retail deposit inflows into 2% accounts and labor-union demands for larger wage increases aligned with BoJ goals. Market participants positioned ahead of the next BoJ and Fed policy meetings, with limited follow-through after initial CPI-driven buying faded.

The yen retreated modestly from its one-month high as broader dollar moves dominated late-session trading. Deposit flows and wage talks underscored household and corporate adaptation to the 1.25% policy rate, while stable financial-system conditions reduced risks of dysfunction during normalisation.

The Day Ahead

Attention turns to the BoJ’s next policy meeting and any updates on quantitative easing operations or yield-curve control parameters. Market focus also includes the upcoming FOMC decision and potential signals on U.S. rates that could influence yen cross rates.

No major Japanese data releases are scheduled, leaving room for further commentary from BoJ officials on inflation persistence and wage trends. Traders will monitor any statements from Japan’s Economic and Fiscal Policy Minister on the timing of a deflation-exit declaration. Positioning is expected to remain cautious until clearer guidance emerges on the path of policy normalisation.

Cross-border capital flows into yen assets and the recent retreat in Brent crude and gold prices may further shape risk sentiment ahead of the meetings.

Other Economic Notes

Persistent core inflation above target has narrowed the gap between government and BoJ views on price stability, increasing the likelihood of an additional rate hike before year-end. ↓ p.2
Page 1

Japan Macro Daily(Beta Mode)

October 23, 2026 robomacro.com
Japan 10Y JGB Yield Japan 10Y JGB Yield | Type: macro_line | Long-term Yield %: 3.05 (2026-09-01) | Range: 0.05–3.05 | Trend(6pt): 0.05,0.49,0.725,1.5,2.79,3.05
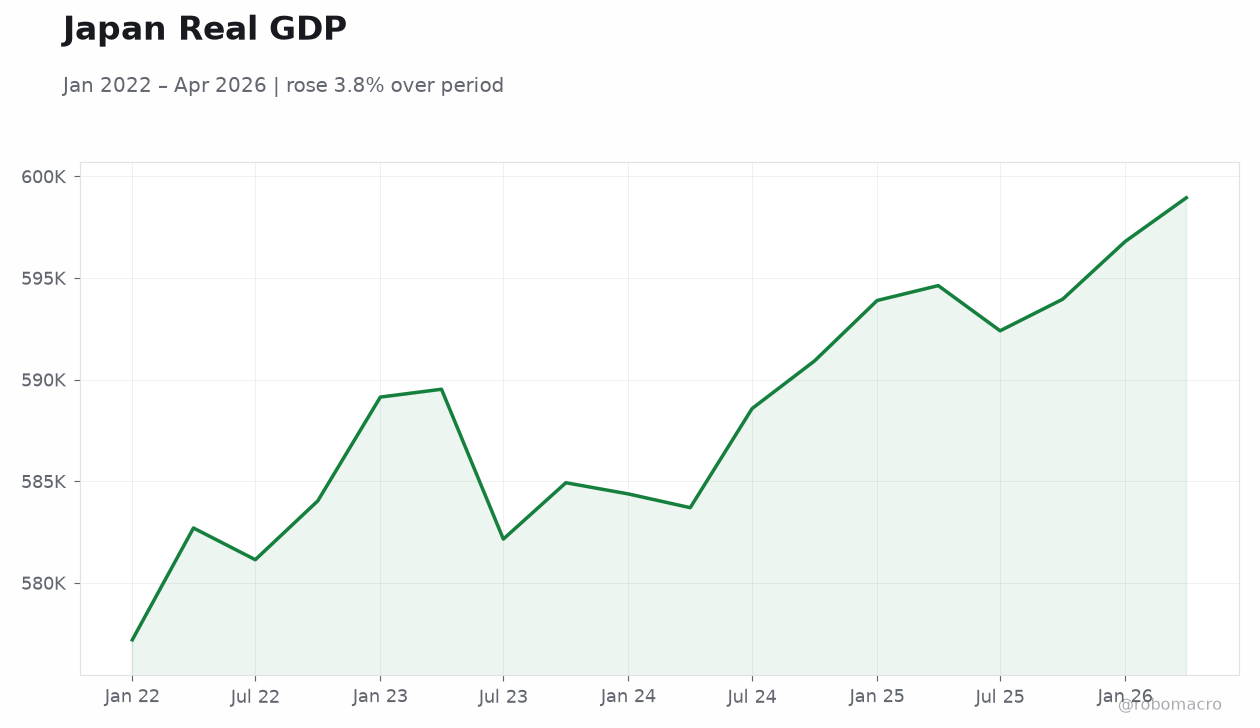
Japan Real GDP Japan Real GDP | Type: macro_line | Real GDP (bn JPY): 5.99e+05 (2026-04-01) | Range: 5.772e+05–5.99e+05 | Trend(6pt): 5.772e+05,5.891e+05,5.844e+05,5.939e+05,5.968e+05,5.99e+05
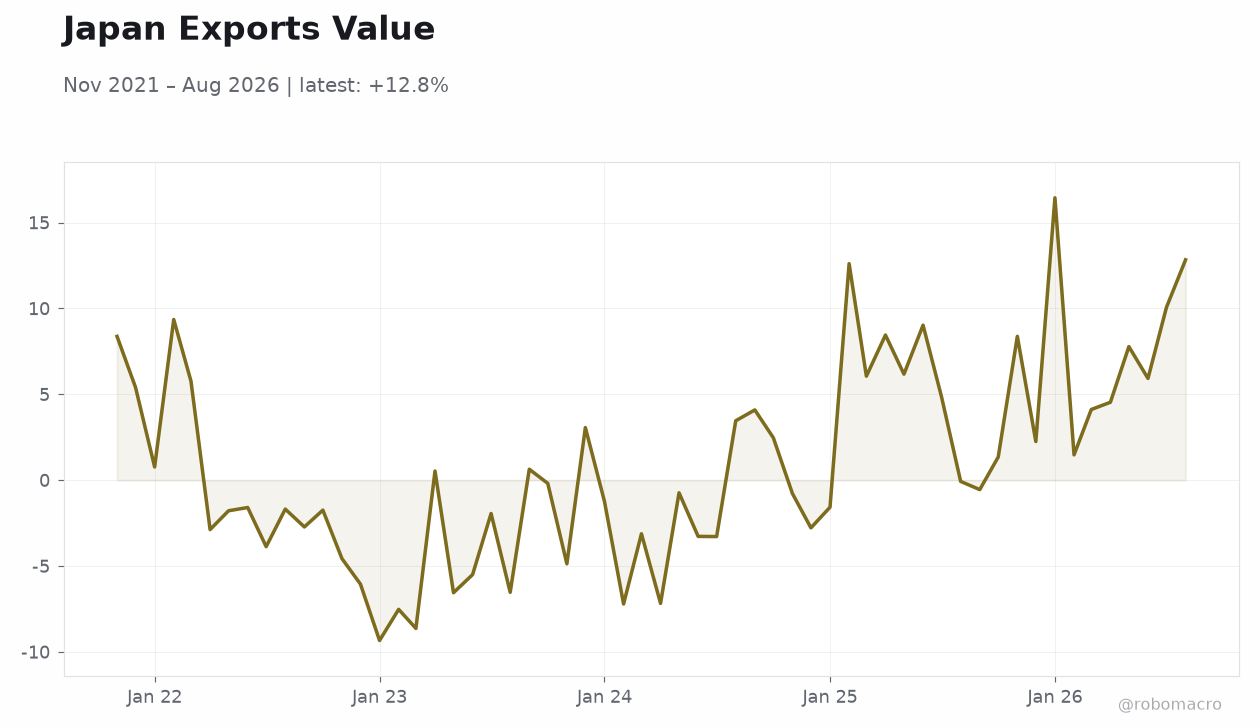
Japan Exports Value Japan Exports Value | Type: macro_line | Exports (USD mn): 12.83 (2026-08-01) | Range: -9.335–16.44 | Trend(6pt): 8.371,-9.335,-3.122,6.175,10.07,12.83
USD/JPY Exchange Rate USD/JPY Exchange Rate | Type: market_hloc | USD per JPY: 156.9 (2026-10-23) | Range: 153.4–163.9 | Trend(6pt): 163.1,159.4,156.2,157.4,158.3,156.9

Other Economic Notes (continued)

Deposit flows into higher-yielding accounts signal households are already adjusting to a higher-rate environment. Wage negotiations led by the top labor union are tracking BoJ preferences for sustained real-income gains that could support consumption. These domestic developments occur against a backdrop of stable financial-system conditions reported by the BoJ, reducing near-term risks of market dysfunction during normalisation.

Yen strength from policy expectations has eased imported inflation pressures, supporting measured tightening without abrupt balance-sheet shifts.

Global Macro News

The dollar traded broadly weaker after softer U.S. data reinforced expectations of Fed easing later this year, providing a supportive backdrop for yen gains. Eurozone and U.S.

flash PMI releases scheduled for today will offer fresh readings on global growth momentum that could affect risk sentiment toward Japanese equities. Brent crude and gold both declined, reflecting reduced geopolitical premium and lower inflation expectations outside Japan. Bitcoin held near session highs, indicating selective risk appetite in non-traditional assets.

Cross-border capital flows into yen assets have accelerated on BoJ policy divergence, supporting the currency even as equity markets corrected. Global investors are reassessing duration exposure in JGBs given the prospect of further BoJ tightening.

Sponsored by Arbitrage Search
Page 2

Japan Macro Daily(Beta Mode)

October 23, 2026 robomacro.com

Continuation

BoJ Watch

Recent inflation prints above the 2% target have cemented market conviction that the BoJ will raise its 1.25% policy rate again before December. BoJ communications continue to emphasise that financial-system stability remains intact, providing room for gradual normalisation without abrupt adjustments to bond purchases. Political pressure from figures such as Takaichi for increased JGB buying highlights ongoing tension between fiscal and monetary authorities over the pace of balance-sheet reduction.

The Summary of Opinions from the last meeting underscored members’ focus on wage-price dynamics, with several noting that sustained core inflation justifies further tightening. Yen strength driven by capital inflows and policy expectations has eased imported inflation pressures, potentially allowing the BoJ to proceed with measured hikes. Markets now price a high probability of a December move, with attention shifting to whether the BoJ will signal any change to its forward guidance on quantitative easing.

Sponsored by Arbitrage Search
Page 3