Japan Macro Daily(Beta Mode)
Japan Inflation Tops Target as Yen Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 62,189.65 | -0.80% |
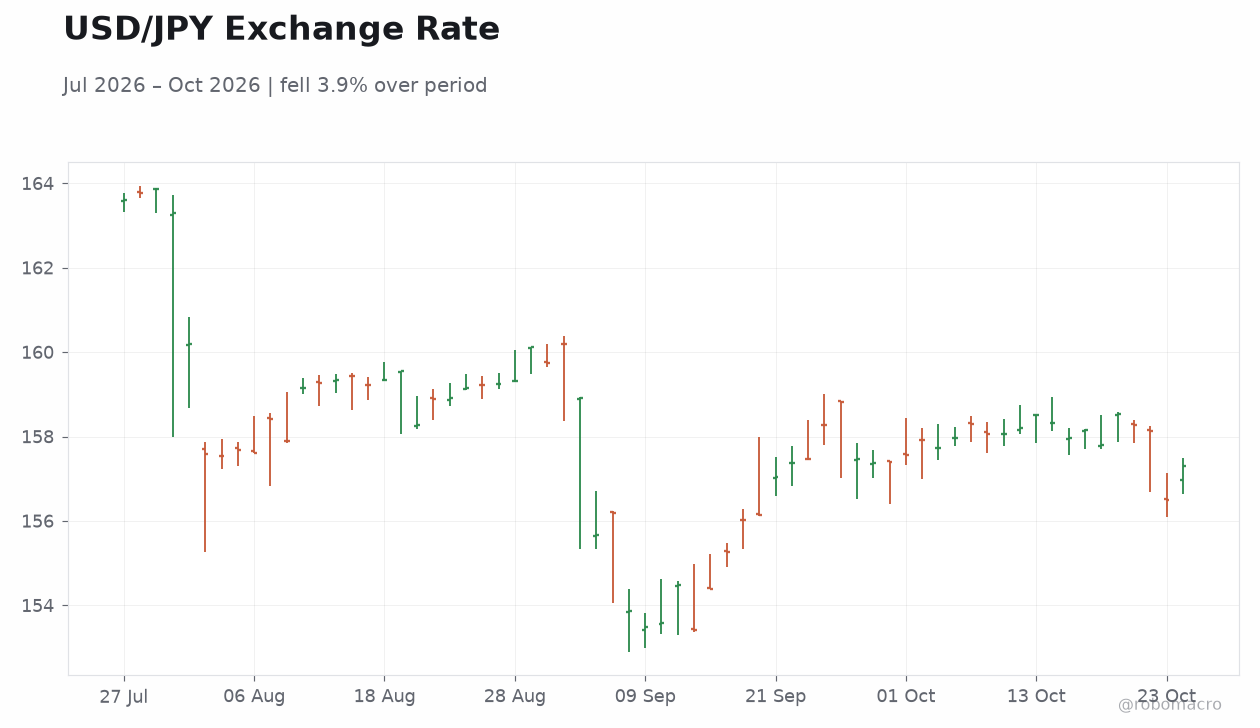
| USD/JPY | 157.29 | +0.51% |
| EUR/JPY | 175.97 | +0.21% |
| GBP/JPY | 210.04 | +0.13% |
| Gold | 4,033.60 | +0.64% |
| Brent Crude | 110.15 | -5.63% |
| Bitcoin | 80,230.18 | +0.26% |
| Japan 2Y Govt Yield | 1.87% | -4 bp |
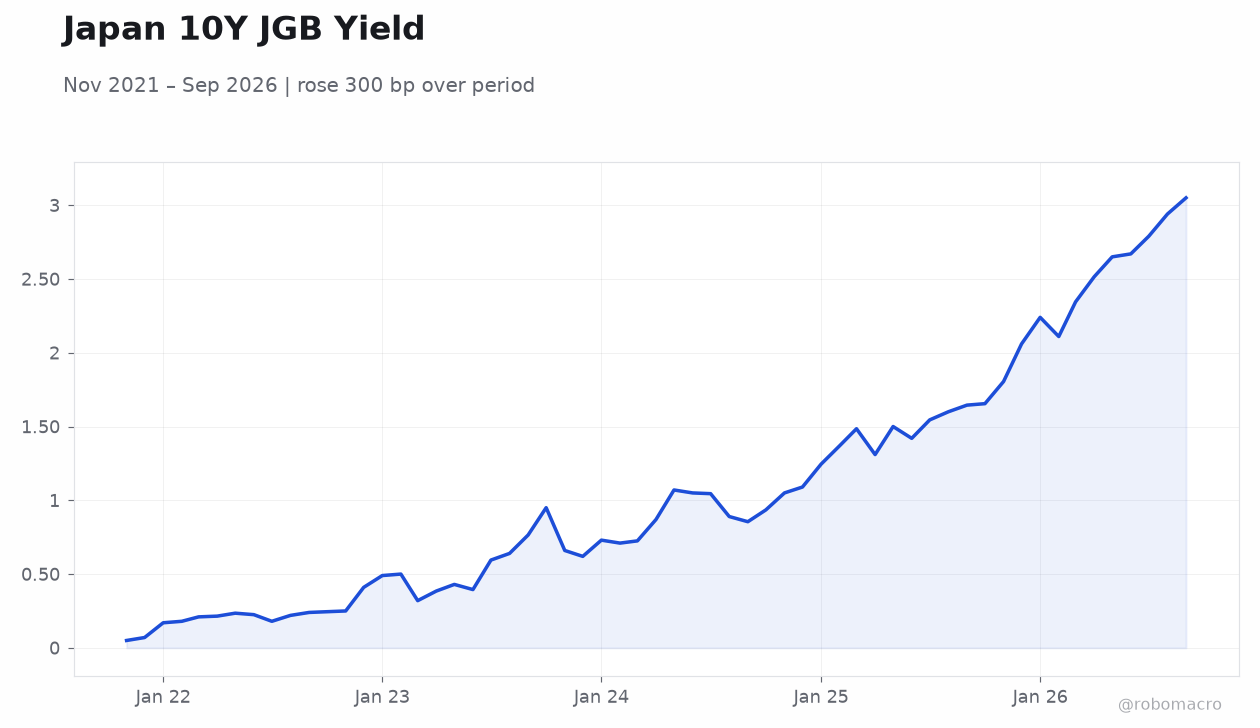
| Japan 10Y Govt Yield | 2.84% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
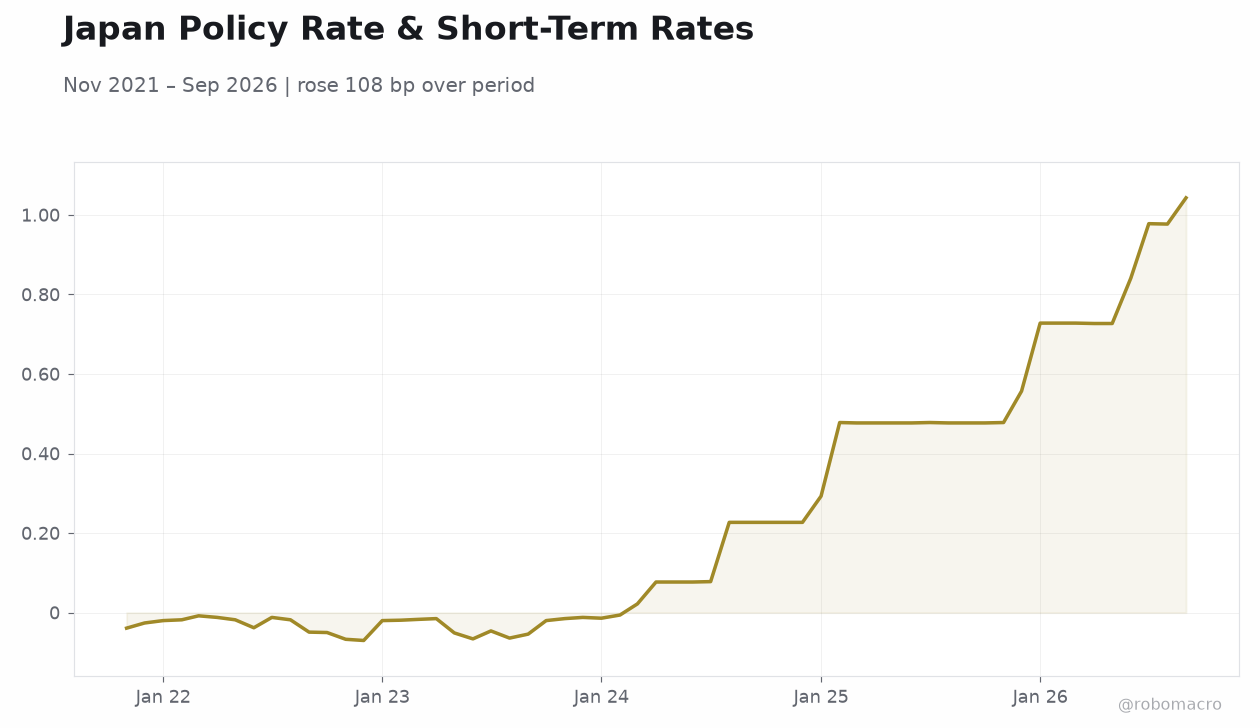 Japan Policy Rate & Short-Term Rates | Type: macro_line | Policy Rate %: 1.043 (2026-09-01) | Range: -0.07–1.043 | Trend(6pt): -0.039,-0.02,0.022,0.477,0.978,1.043
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-29) | |||
| Consumer Confidence Index | 35.40 | 35.10 | 01:00 |
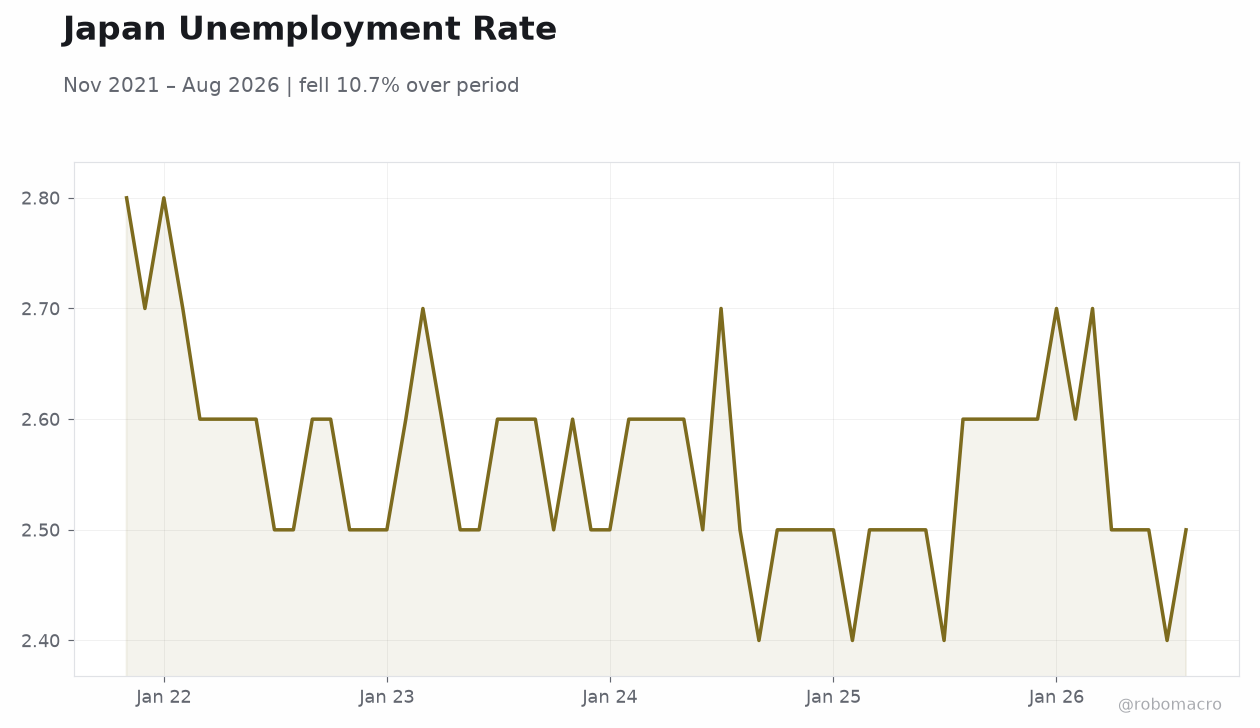
| Headline Unemployment Rate | 2.50 | 2.50 | 19:30 |
| Industrial Production Month-over-Month Preliminary | -2.40 | 1.30 | 19:50 |
| Retail Sales Year-over-Year | 2.70 | 3.30 | 19:50 |
| BoJ Interest Rate Decision | 1.25 | 1.25 | 23:00 |
| BoJ Quarterly Outlook Report | - | - | 23:00 |
| Friday (2026-10-30) | |||
| Housing Starts Year-over-Year | 6.10 | 2.90 | 01:00 |
- Core inflation reached 2.10% YoY, exceeding the BoJ target and supporting expectations for gradual normalisation.
- Markets expect the BoJ to hold the policy rate at 1.25% while signalling further tightening in the Quarterly Outlook.
- JGB yields declined with the 10-year easing 7 bp to 2.84% amid risk aversion and lower growth expectations.
Yesterday's Recap
Japanese inflation data released over the weekend showed core CPI at 2.10% YoY, the first sustained breach of the 2% target this year and a clear driver of market moves on 25 October. The yen weakened broadly, with USD/JPY rising 0.51% to 157.29 and EUR/JPY gaining 0.21%. Equity markets sold off, sending the Nikkei 225 down 0.80% to 62,189.65 as investors rotated into safe-haven assets.
The 2-year JGB yield fell 4 bp to 1.87% while the 10-year eased 7 bp to 2.84%, reflecting both lower growth expectations and demand for duration. Brent crude dropped 5.63% to $110.15, adding to the disinflationary global backdrop. Overall risk aversion intensified, lifting gold 0.64% and bitcoin 0.26% as cross-asset hedging increased.
The Day Ahead
Attention turns to Thursday’s BoJ policy decision and Quarterly Outlook Report, both due at 23:00 ET, where the committee is expected to keep the policy rate unchanged at 1.25%. Markets will scrutinise the new projections for any upward revision to inflation forecasts that could open the door to a December hike. Earlier in the session, consumer confidence, the unemployment rate, industrial production and retail sales prints will provide fresh readings on household and factory momentum.
Housing starts data on Friday will round out the week’s domestic releases. Traders will also monitor any language on wage trends and yen volatility in the Summary of Opinions.
Other Economic Notes
The return of core inflation above target marks a structural shift after years of sub-2% prints and strengthens the case for gradual policy normalisation. Yen movements are now influenced by both inflation differentials and expectations of BoJ tightening. JGB curve flattening has accelerated as front-end rates price in future hikes while longer yields remain anchored by global risk aversion.
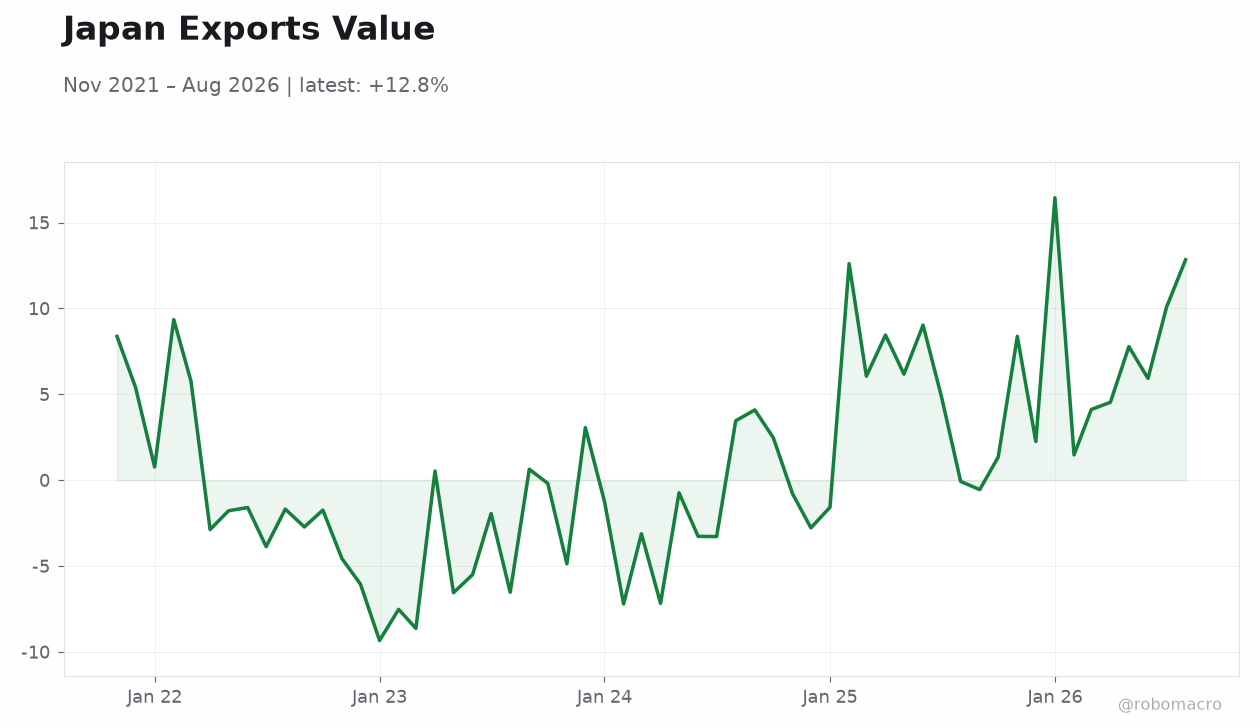
Domestic demand indicators remain mixed, with retail sales expected to improve but industrial production still recovering from the prior contraction. Capital outflows from Japanese investors have slowed, supporting the currency even as global equity volatility rises.