Japan Macro Daily(Beta Mode)
BoJ Pause Looms as Inflation Accelerates
Market Snapshot
| Asset | Level | Change |
|---|---|---|
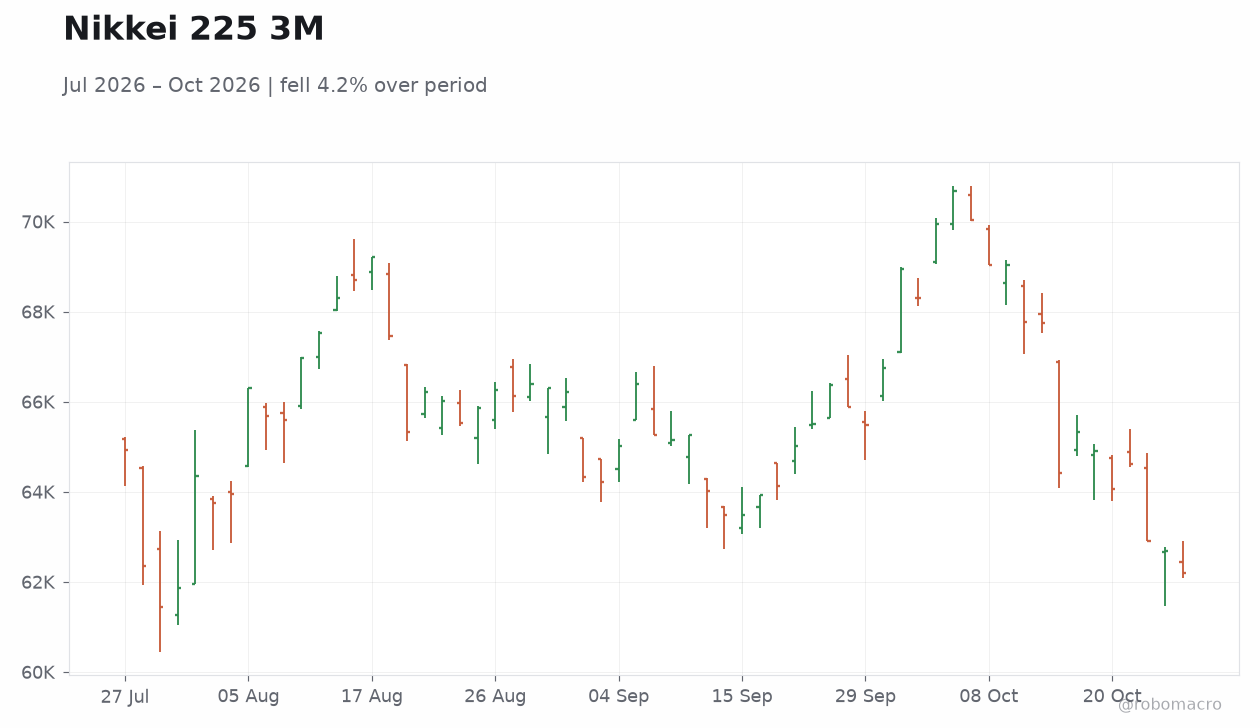
| Nikkei 225 | 62,189.65 | -0.80% |
| USD/JPY | 157.91 | +0.69% |
| EUR/JPY | 175.68 | -0.13% |
| GBP/JPY | 210.10 | +0.15% |
| Gold | 4,074.50 | +0.89% |
| Brent Crude | 109.78 | -5.21% |
| Bitcoin | 80,688.92 | +0.85% |
| Japan 2Y Govt Yield | 1.89% | +2 bp |
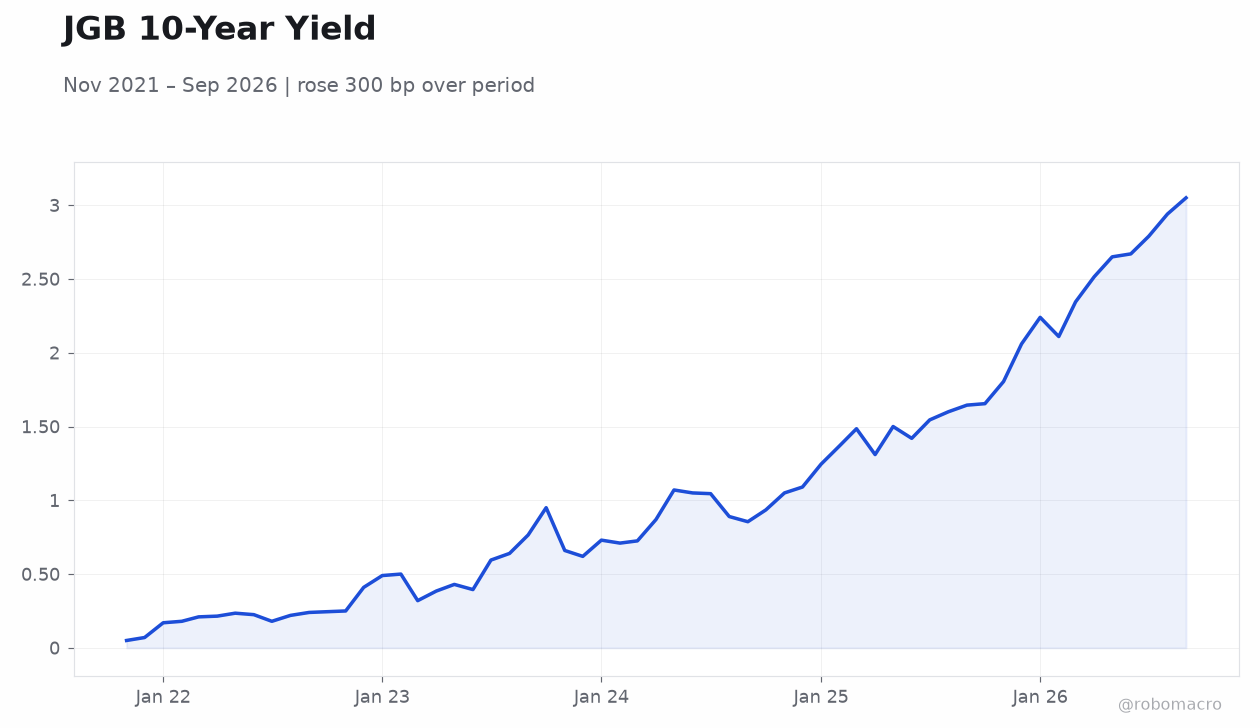
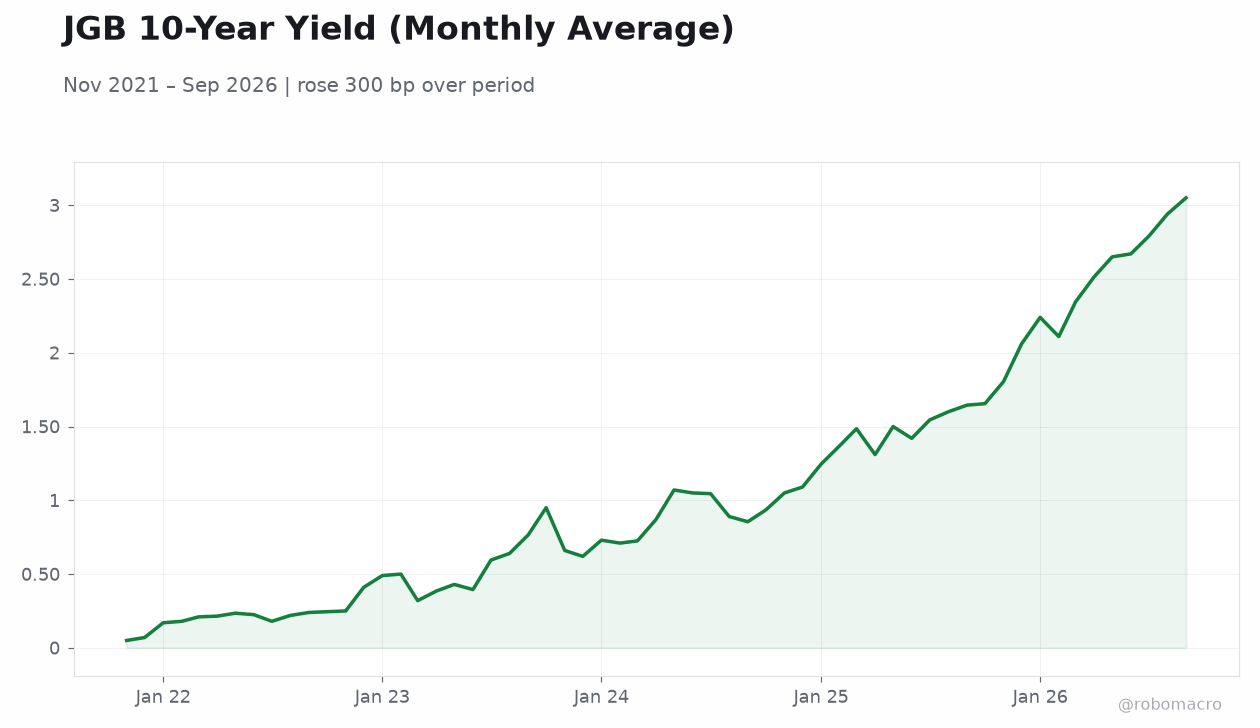
| Japan 10Y Govt Yield | 2.82% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
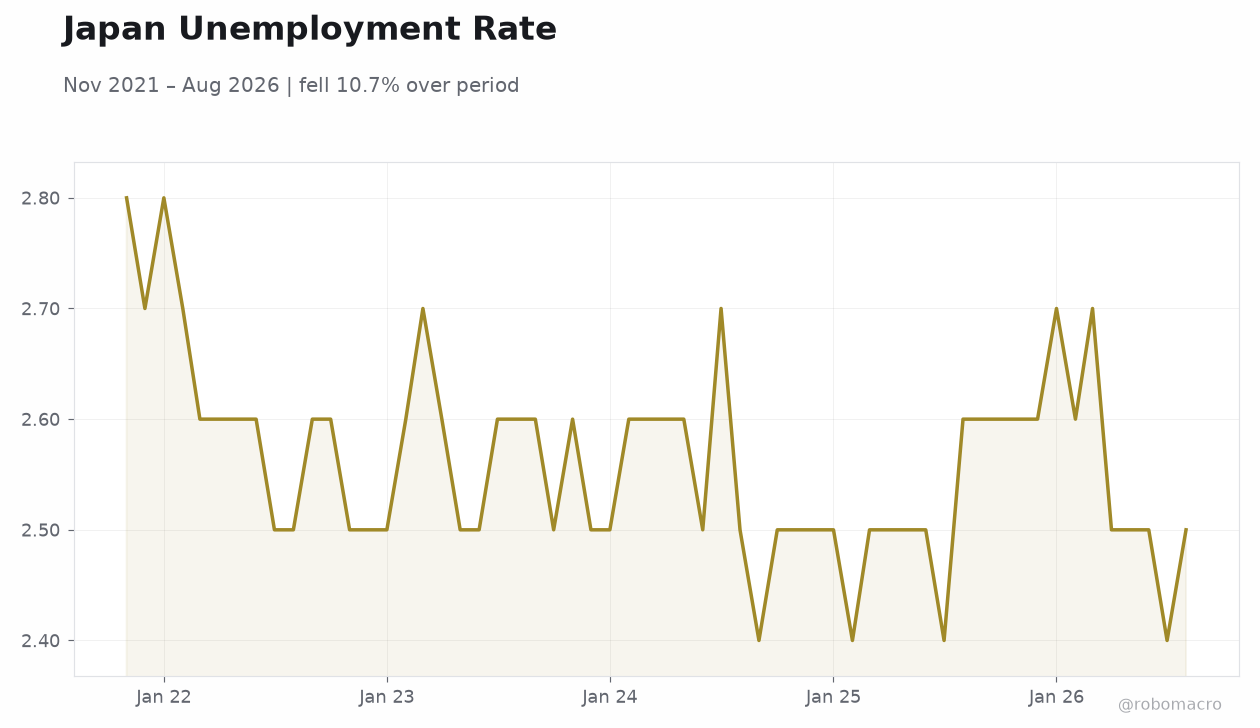 Japan Unemployment Rate | Type: macro_line | Unemployment Rate %: 2.5 (2026-08-01) | Range: 2.4–2.8 | Trend(6pt): 2.8,2.5,2.6,2.5,2.4,2.5
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-29) | |||
| Consumer Confidence Index | 35.40 | 35.10 | 01:00 |
| Headline Unemployment Rate | 2.50 | 2.50 | 19:30 |
| Industrial Production Month-over-Month Preliminary | -2.40 | 1.30 | 19:50 |
| Retail Sales Year-over-Year | 2.70 | 3.30 | 19:50 |
| BoJ Interest Rate Decision | 1.25 | 1.25 | 23:00 |
| BoJ Quarterly Outlook Report | - | - | 23:00 |
| Friday (2026-10-30) | |||
| Housing Starts Year-over-Year | 6.10 | 2.90 | 01:00 |
- Markets price in BoJ hold at 1.25% with December hike odds rising on CPI uptick.
- Yen weakens further as USD/JPY climbs to 157.91 amid global dollar strength.
- JGB curve steepens modestly with 2-year yield at 1.89% and 10-year at 2.82%.
Yesterday's Recap
Equity markets closed lower as the Nikkei 225 fell 0.80% to 62,189.65 while investors positioned ahead of the Bank of Japan meeting. The yen extended losses against the dollar, with USD/JPY rising 0.69% to 157.91 on broad greenback demand. Short-term JGB yields edged higher, lifting the 2-year yield 2 basis points to 1.89%, while the 10-year yield eased 2 basis points to 2.82%.
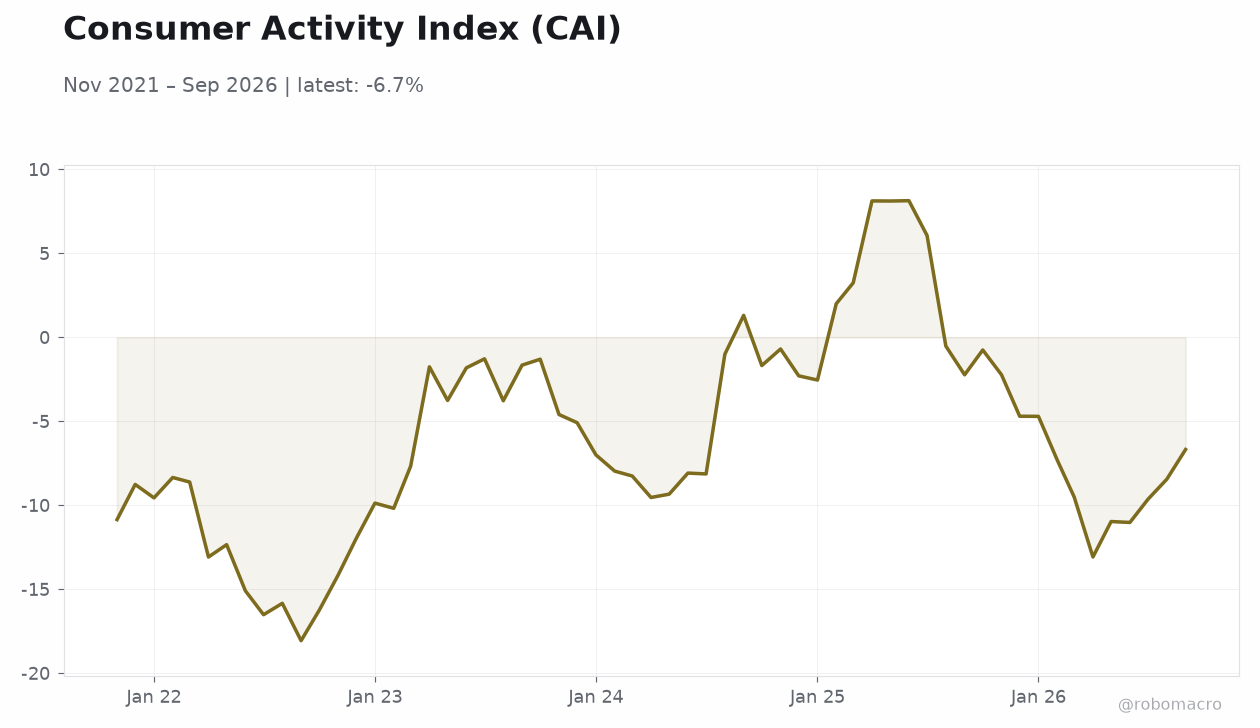
Recent consumer inflation data at 2.10% year-over-year provided fresh evidence of price pressures that support policy normalisation. Retail and industrial sectors showed mixed momentum, with traders focusing on how the BoJ will frame its quarterly outlook. Cross-yen pairs remained largely contained, though GBP/JPY ticked up 0.15% ahead of the UK budget.
Overall risk sentiment stayed cautious as participants awaited fresh signals on the timing of the next rate move.
The Day Ahead
Attention turns to Thursday’s cluster of releases, beginning with the Consumer Confidence Index at 01:00 ET. The unemployment rate is due at 19:30 ET alongside preliminary industrial production and retail sales figures that will clarify momentum in manufacturing and household spending. The Bank of Japan is scheduled to announce its policy decision and release the quarterly outlook report at 23:00 ET on 2026-10-30, with markets expecting the committee to keep the policy rate unchanged at 1.25%.
Friday brings housing starts data that will round out the week’s domestic indicators. Analysts will parse the BoJ statement and projections for any shift in language around the pace of normalisation. Volatility in yen crosses is likely to increase once the decision and accompanying report are published.
Other Economic Notes
Japan’s inflation acceleration continues to shape expectations for gradual rate increases through 2027. Rising living costs have boosted demand for low-price entertainment such as claw machines, illustrating how households adjust spending patterns. Policymakers face a narrow path between supporting growth and anchoring inflation expectations near the 2% target.
↓ p.2