Japan Macro Daily(Beta Mode)
BoJ Hold Looms as Yen Presses 158
Market Snapshot
| Asset | Level | Change |
|---|---|---|
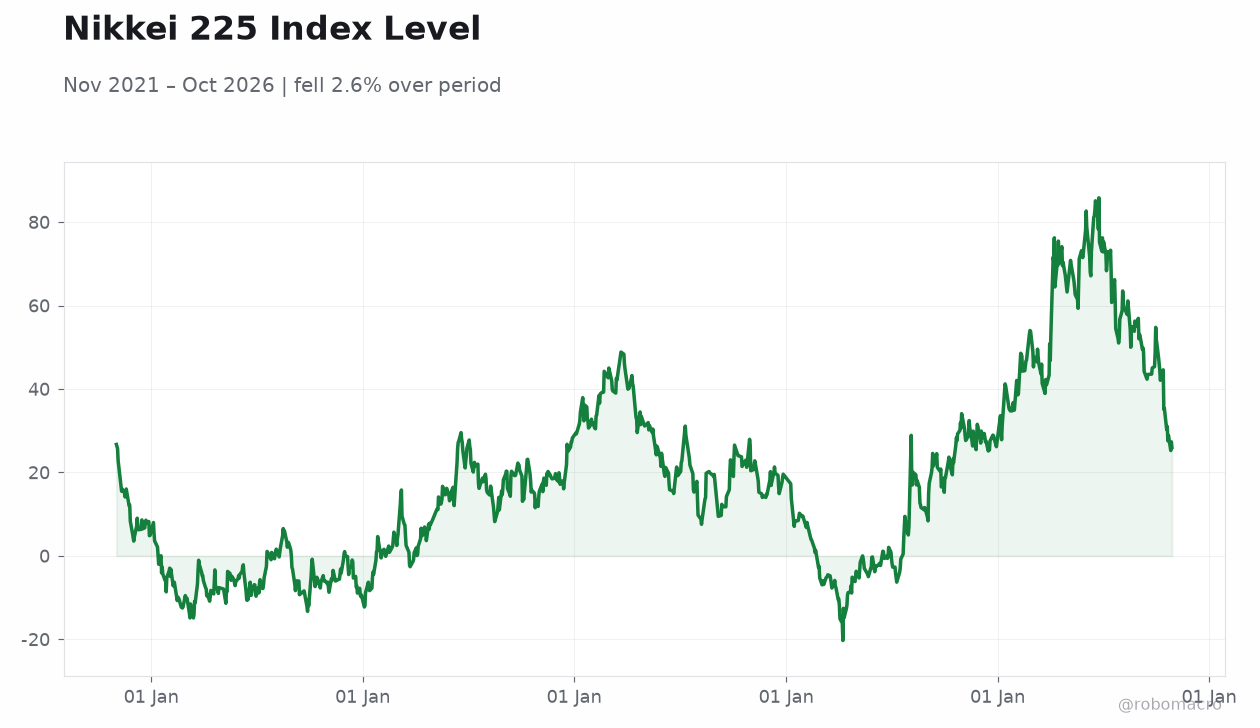
| Nikkei 225 | 63,954.19 | +1.08% |
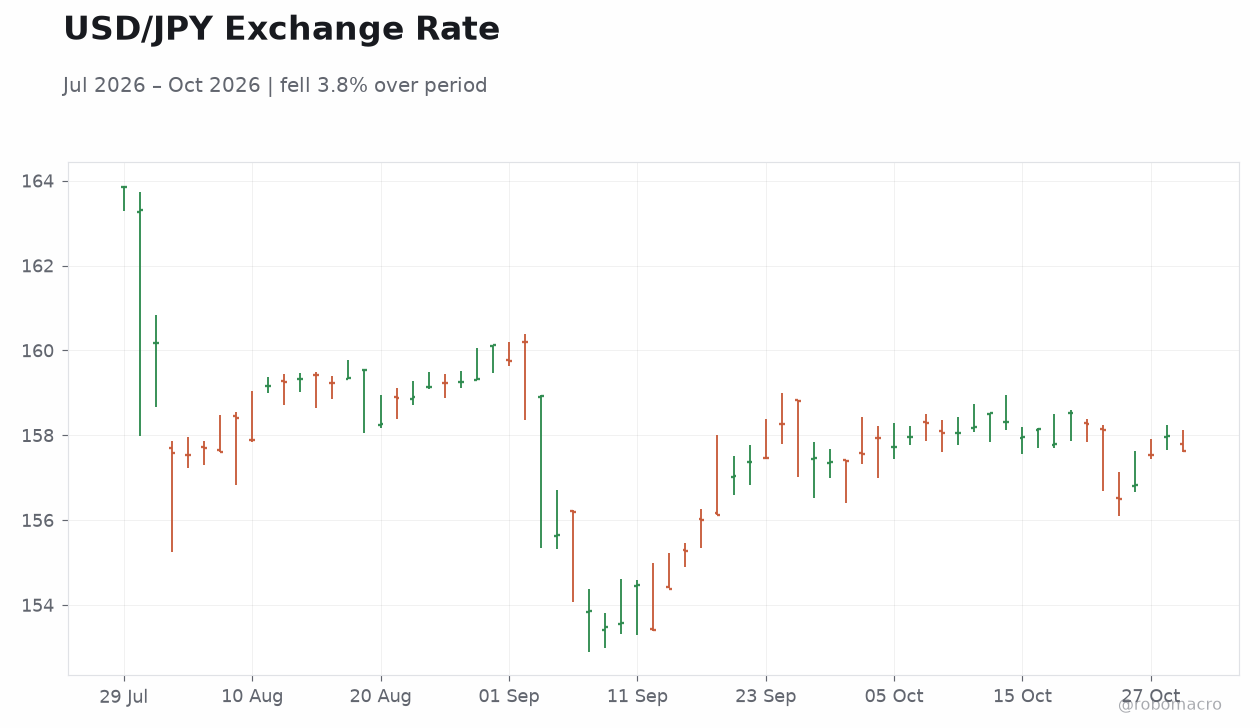
| USD/JPY | 157.63 | -0.23% |
| EUR/JPY | 176.10 | +0.18% |
| GBP/JPY | 210.84 | +0.30% |
| Gold | 4,031.10 | -0.51% |
| Brent Crude | 111.43 | -3.37% |
| Bitcoin | 78,753.04 | -3.09% |
| Japan 2Y Govt Yield | 1.92% | +3 bp |
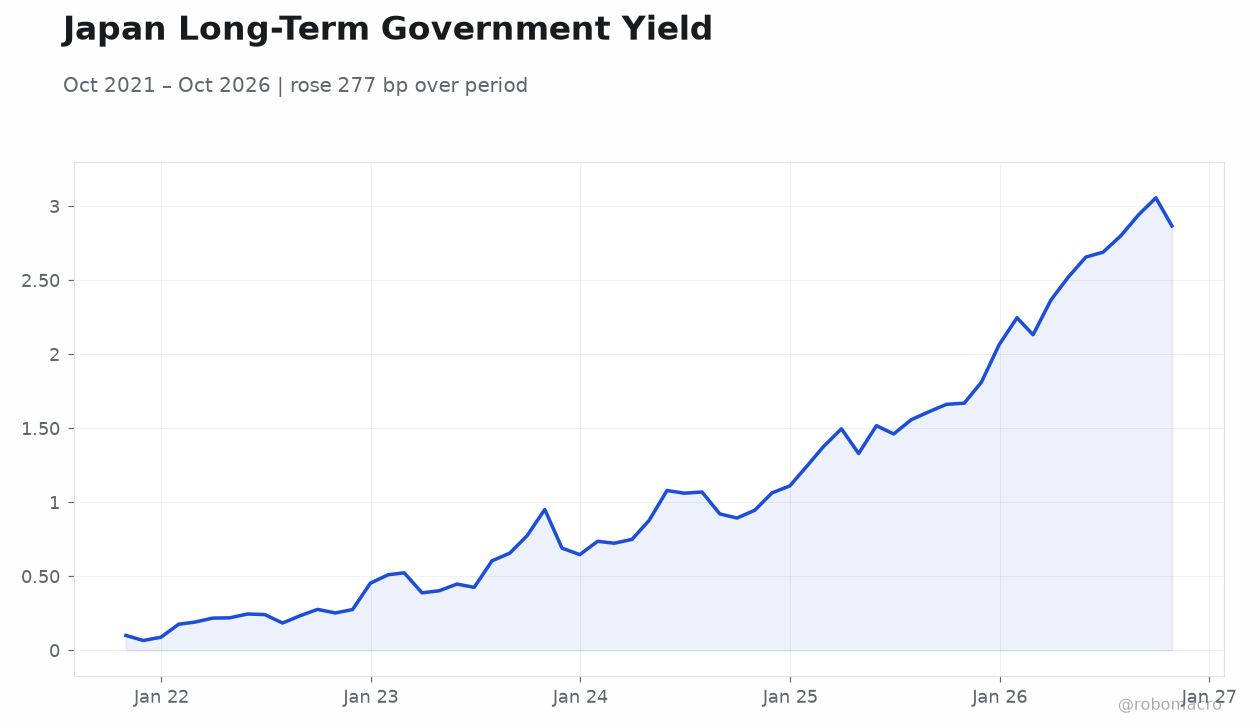
| Japan 10Y Govt Yield | 2.87% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Consumer Confidence Index | 35.40 | 35.10 | 35 |
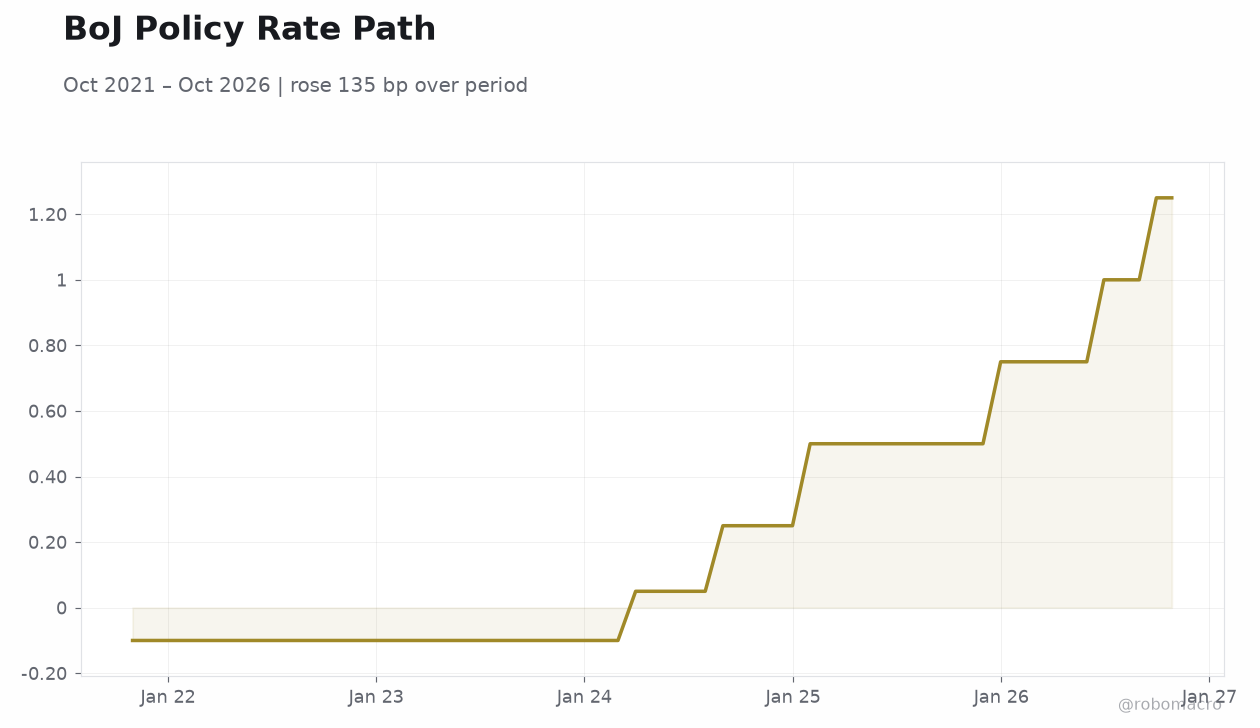 BoJ Policy Rate Path | Type: macro_line | Policy Rate (%): 1.25 (2026-10-27) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Headline Unemployment Rate | 2.50 | 2.50 | 19:30 |
| Industrial Production Month-over-Month Preliminary | -2.40 | 1.30 | 19:50 |
| Retail Sales Year-over-Year | 2.70 | 3.30 | 19:50 |
| BoJ Interest Rate Decision | 1.25 | 1.25 | 23:00 |
| BoJ Monetary Policy Statement | - | - | 23:00 |
| BoJ Quarterly Outlook Report | - | - | 23:00 |
- BoJ widely expected to hold policy rate at 1.25% at today's decision, with the quarterly Outlook Report and Governor's press conference the key event risk for the yen.
- Consumer Confidence Index printed at 35.0, slightly below the 35.1 consensus and down from 35.4 prior, underscoring fragile household sentiment.
- JGB yields pushed higher ahead of the decision — 10Y at 2.87% (+4 bp) and 2Y at 1.92% (+3 bp) — while Nikkei extended its rally above 64,000.
Yesterday's Recap
Japan's Consumer Confidence Index for October printed at 35.0, marginally below the 35.1 consensus and softening from the prior 35.4 reading, a reminder that household sentiment remains subdued despite firm equity markets. Japanese equities extended their run, with the Nikkei 225 rising 1.08% to 63,954.19, reclaiming the 64,000 handle intraday for a third consecutive session of gains. JGBs were steady overall but yields edged higher into the BoJ meeting, with the 10-year yield at 2.87% (+4 bp) and the 2-year at 1.92% (+3 bp); a strong auction lent underlying support to the curve.
In FX, the yen weakened toward 158 per dollar, with USD/JPY at 157.63 (-0.23% on the day) as markets positioned for both the BoJ and the Fed. Cross-JPY flows were mixed, with EUR/JPY at 176.10 (+0.18%) and GBP/JPY at 210.84 (+0.30%). Broader risk sentiment was softer, with Brent crude down 3.37% at $111.43 and Bitcoin off 3.09%.
The Day Ahead
The spotlight is squarely on the Bank of Japan, with the interest rate decision, Monetary Policy Statement and Quarterly Outlook Report all due at 23:00 ET, followed by the Governor's press conference at 02:30 ET on October 30. Consensus points to an unchanged policy rate of 1.25%, but the Outlook Report's inflation projections and any language shift on normalisation will drive JGB and yen reaction. Ahead of that, Japan releases its headline unemployment rate at 19:30 ET, with consensus at 2.5% versus 2.5% prior.
At 19:50 ET, industrial production month-over-month preliminary is due, with consensus at +1.3% following the prior -2.4% contraction, alongside retail sales year-over-year, where consensus sits at 3.3% versus 2.7% prior. Housing starts year-over-year follow on October 30 at 01:00 ET, consensus 2.9% versus 6.1% prior.
Other Economic Notes
The anticipated rebound in industrial production would partially reverse the prior month's 2.4% contraction, but the consensus +1.3% still leaves output well below earlier peaks, highlighting the uneven nature of Japan's manufacturing recovery. ↓ p.2