Japan Macro Daily(Beta Mode)
BoJ Flags 2% Target Achieved, Holds at 1.25%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
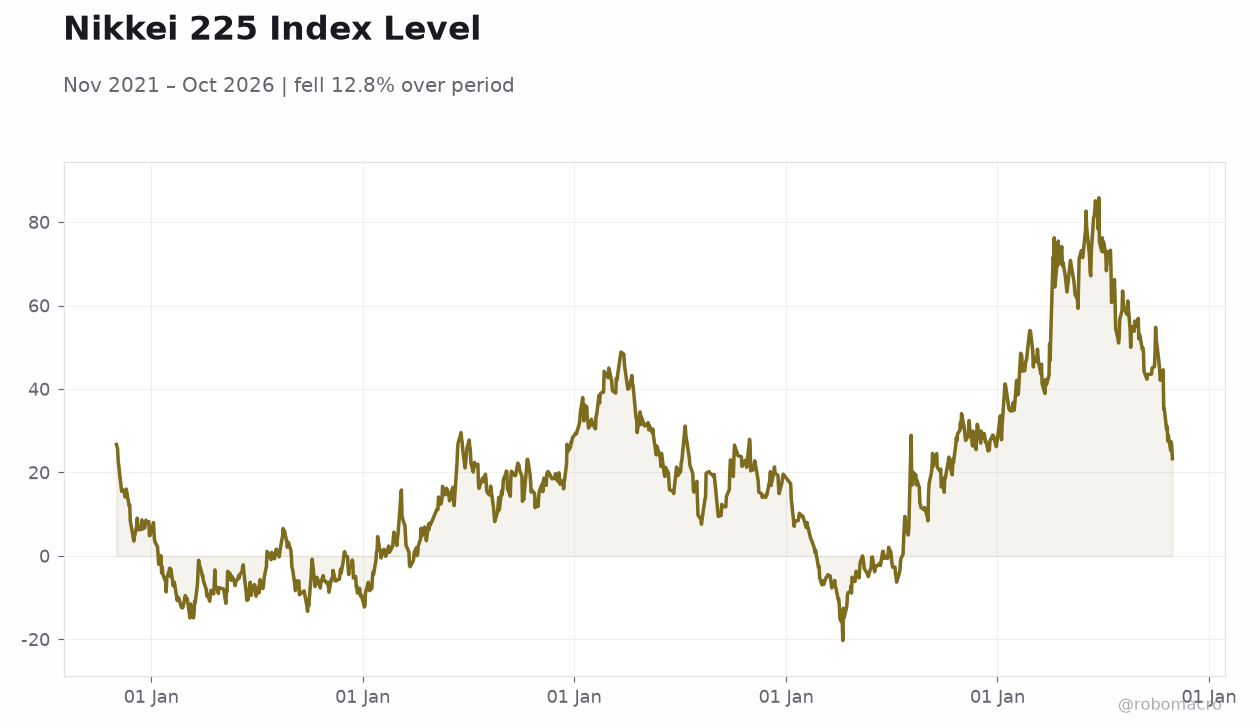
| Nikkei 225 | 63,290.11 | -2.12% |
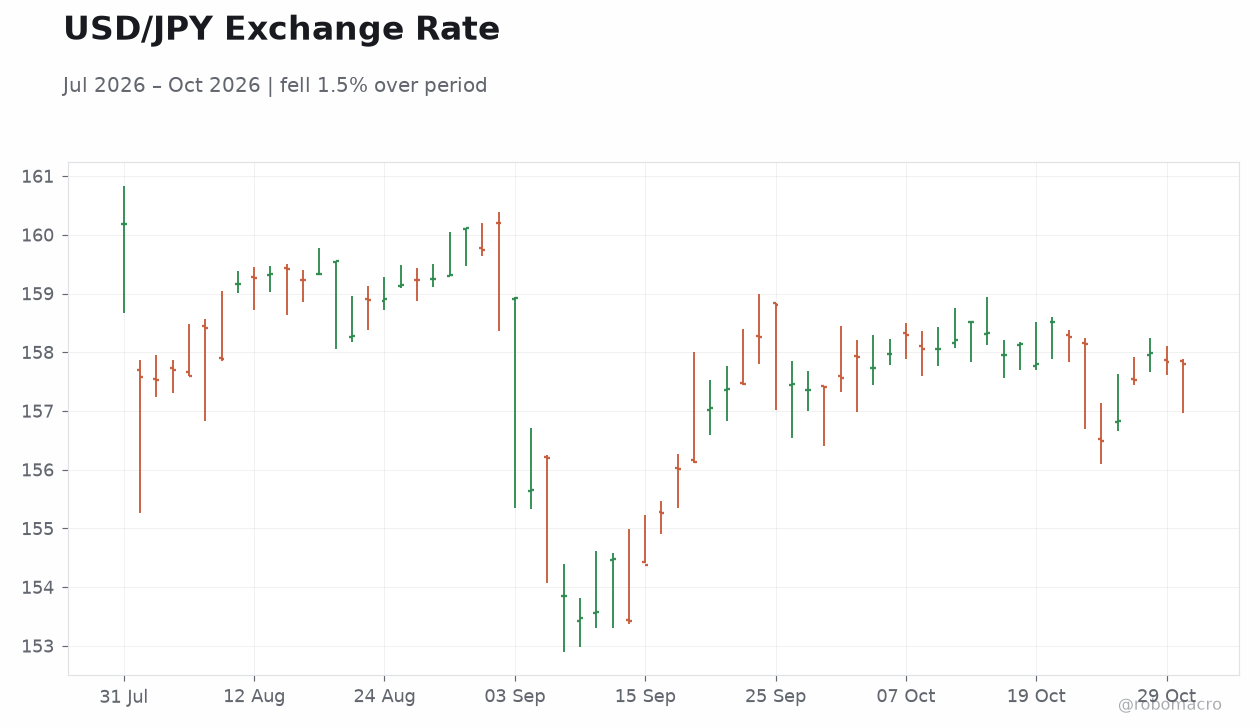
| USD/JPY | 157.80 | -0.02% |
| EUR/JPY | 175.43 | -0.59% |
| GBP/JPY | 210.96 | -0.07% |
| Gold | 3,898.90 | -3.29% |
| Brent Crude | 113.43 | -1.26% |
| Bitcoin | 77,809.37 | +0.48% |
| Japan 2Y Govt Yield | 1.90% | -2 bp |
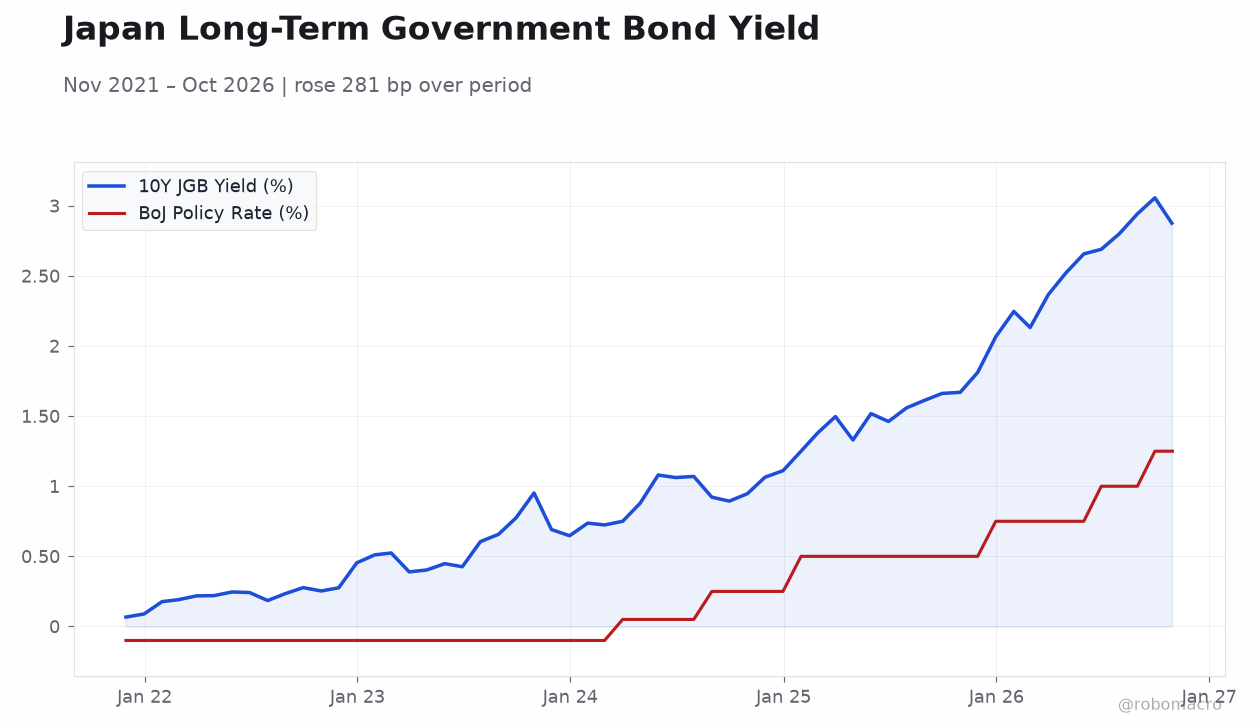
| Japan 10Y Govt Yield | 2.88% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Consumer Confidence Index | 35.40 | 35.10 | 35 |
| Headline Unemployment Rate | 2.50 | 2.50 | 2.40 |
| Industrial Production Month-over-Month Preliminary | -2.40 | 1.30 | 2.20 |
| Retail Sales Year-over-Year | 2.90 | 3.30 | 2.30 |
| BoJ Interest Rate Decision | 1.25 | 1.25 | 1.25 |
| BoJ Monetary Policy Statement | - | - | - |
| BoJ Quarterly Outlook Report | - | - | - |
| Housing Starts Year-over-Year | 6.10 | 2.90 | -2.70 |
| BoJ Press Conference | - | - | - |
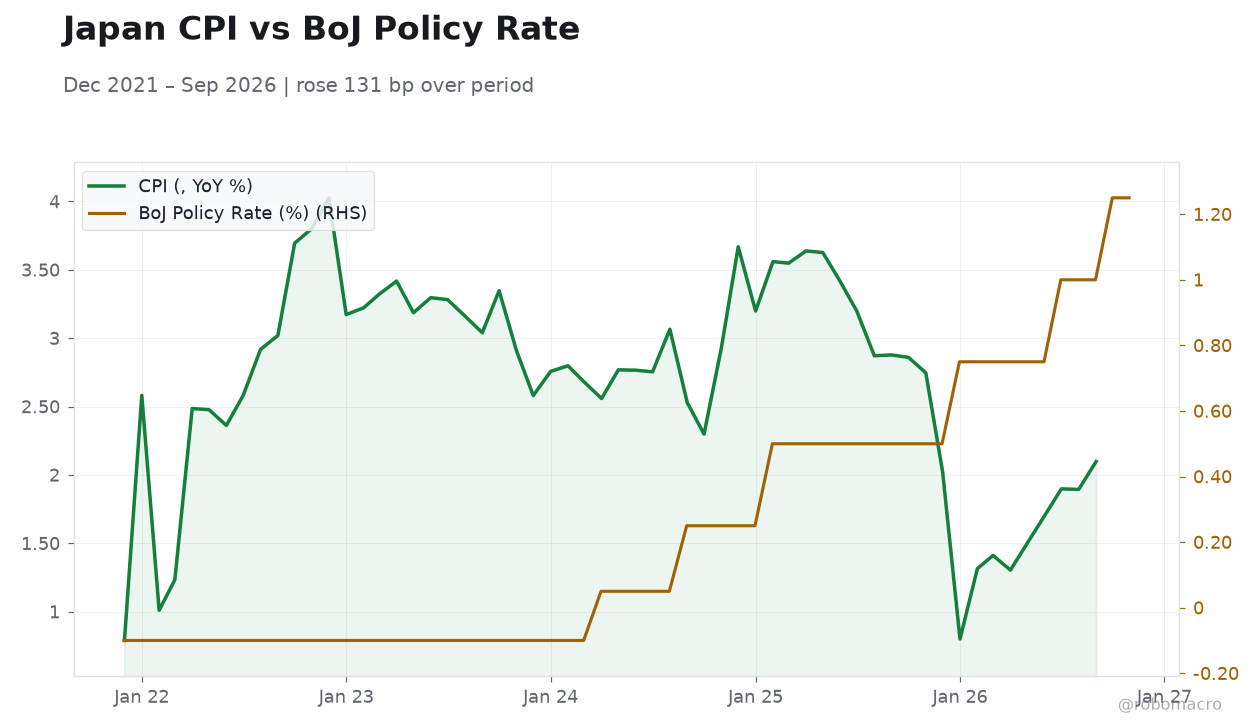
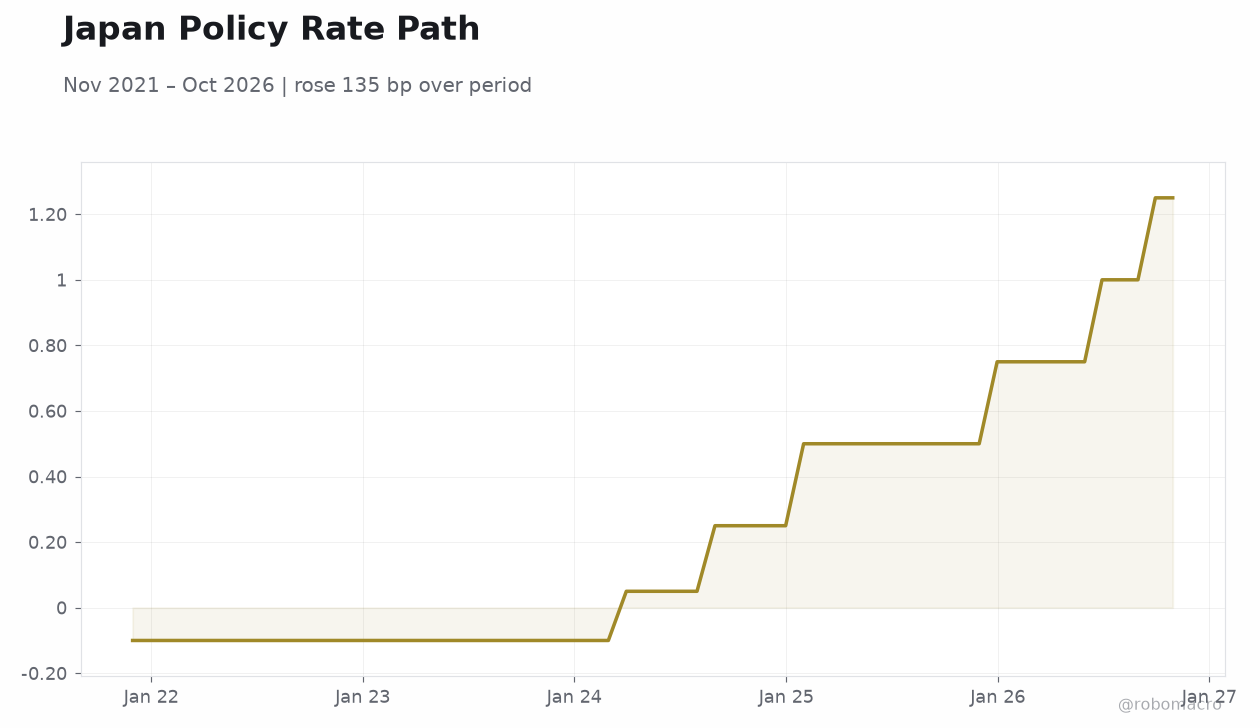 Japan Policy Rate Path | Type: macro_line | BoJ Policy Rate (%): 1.25 (2026-10-30) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BoJ held its policy rate at 1.25% at the 2026-10-30 decision and stated that its 2% price stability target has been "generally achieved," a symbolic milestone that shifts the policy debate toward sustaining inflation rather than generating it.
- The yen firmed modestly on the hawkish framing, with USD/JPY at 157.80 (-0.02%) and EUR/JPY at 175.43 (-0.59%); markets now price a live December hike debate ahead of the 2026-12-18 meeting.
- JGB curve steepened: the 10-year yield rose 1 bp to 2.88% while the 2-year eased 2 bp to 1.90%, and the Nikkei 225 dropped 2.12% to 63,290.11 as risk-off sentiment dominated the session.
Yesterday's Recap
The BoJ's 2026-10-30 decision left the policy rate unchanged at 1.25%, and the accompanying quarterly outlook stated the 2% inflation target has been broadly reached — a landmark framing for Japanese monetary policy. Consumer confidence printed at 35.0, slightly below the 35.1 consensus and down from 35.4 previously. The unemployment rate unexpectedly improved to 2.40% from 2.5%, underscoring a still-tight labour market.
Industrial production rose 2.20% month-over-month, beating the 1.3% consensus and reversing the prior -2.4% contraction. Retail sales disappointed, however, slowing to 2.30% year-over-year versus 3.3% expected and 2.9% prior. Housing starts fell 2.70% year-over-year against a 2.9% consensus gain, a weak spot in an otherwise firm data set.
Markets reacted defensively: the Nikkei 225 fell 2.12% to 63,290.11, USD/JPY held near 157.80, and the 10-year JGB yield edged up 1 bp to 2.88%.
The Day Ahead
No Japanese economic releases are scheduled for 2026-11-01, leaving the session to digest the BoJ's hawkish hold and Governor Ueda's press conference messaging. Trading will focus on whether the yen can extend its modest post-decision firmness and whether JGB yields hold the 2.88% area on the 10-year. With the next policy meeting set for 2026-12-18, market attention turns to December hike pricing and any follow-through in the Summary of Opinions due later in the cycle.
Equity flows will be watched closely after the Nikkei's 2.12% slide, particularly whether the risk-off tone persists into the new month.
Other Economic Notes
The labour market remains tight, with unemployment at 2.40%, supporting the case for gradual policy normalisation even as consumer confidence softens to 35.0. Industrial production's 2.20% rebound suggests manufacturing resilience, but retail sales growth of 2.30% and housing starts at -2.70% point to uneven domestic demand. ↓ p.2