Japan Macro Daily(Beta Mode)
Nikkei Plunges 6% as BoJ Signals December Hike
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 57,434.77 | -5.96% |
| USD/JPY | 158.35 | +0.54% |
| EUR/JPY | 176.25 | -0.32% |
| GBP/JPY | 211.21 | -0.32% |
| Gold | 4,074.90 | -0.94% |
| Brent Crude | 98.32 | +0.03% |
| Bitcoin | 75,672.72 | -0.10% |
| Japan 2Y Govt Yield | 1.86% | -3 bp |
| Japan 10Y Govt Yield | 2.81% | -4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoJ Monetary Policy Meeting Minutes | - | - | - |
| BoJ Gov Ueda Speech | - | - | - |
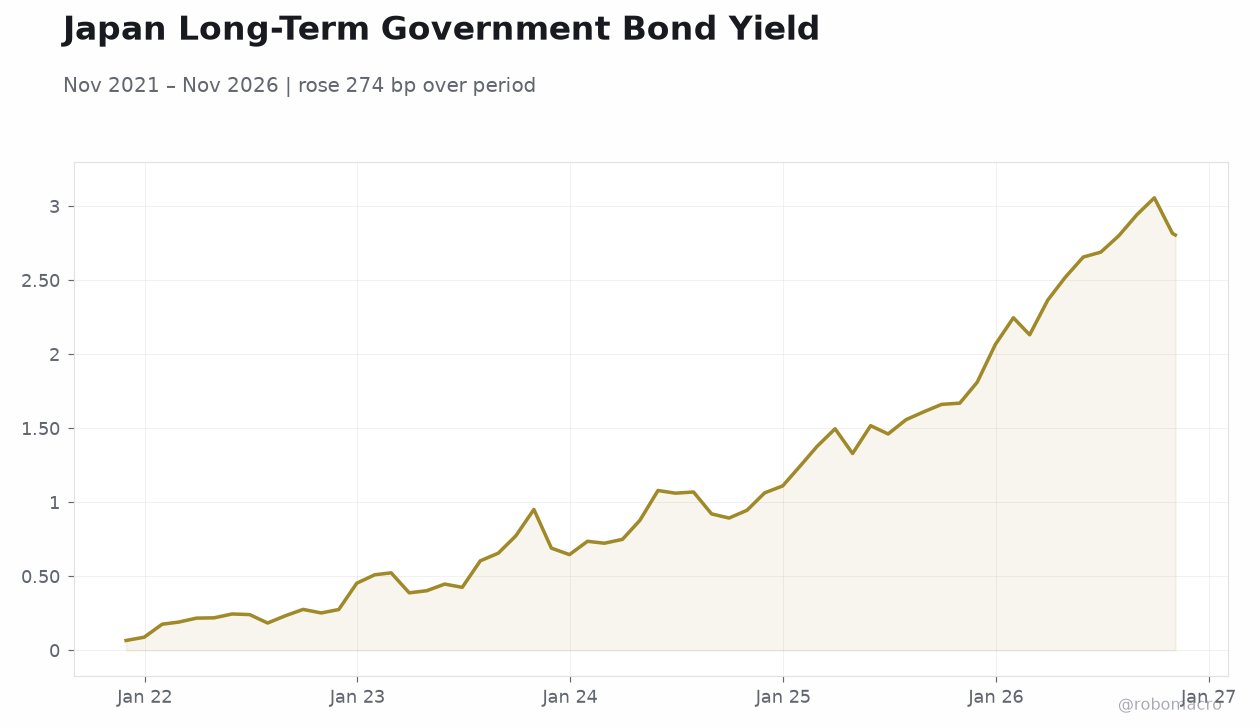 Japan Long-Term Government Bond Yield | Type: macro_line | 10Y JGB Yield (%): 2.806 (2026-11-05) | Range: 0.067–3.057 | Trend(5pt): 0.067,0.524,1.08,1.613,2.806
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
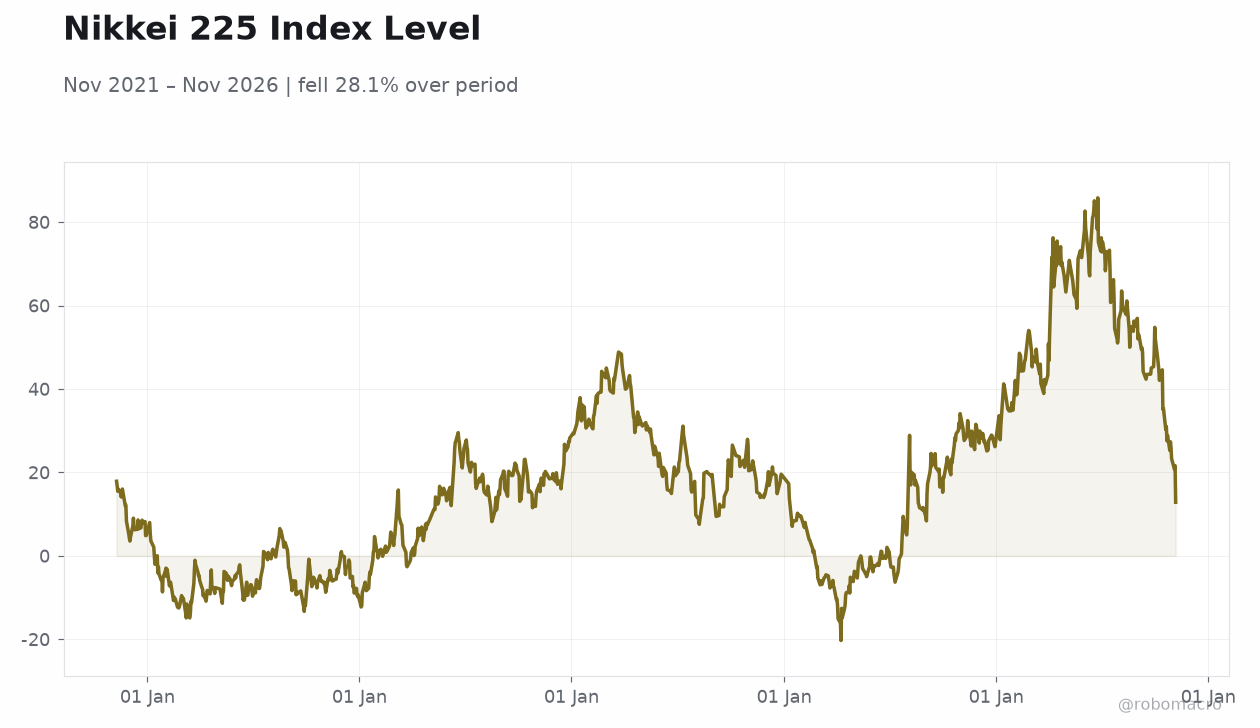
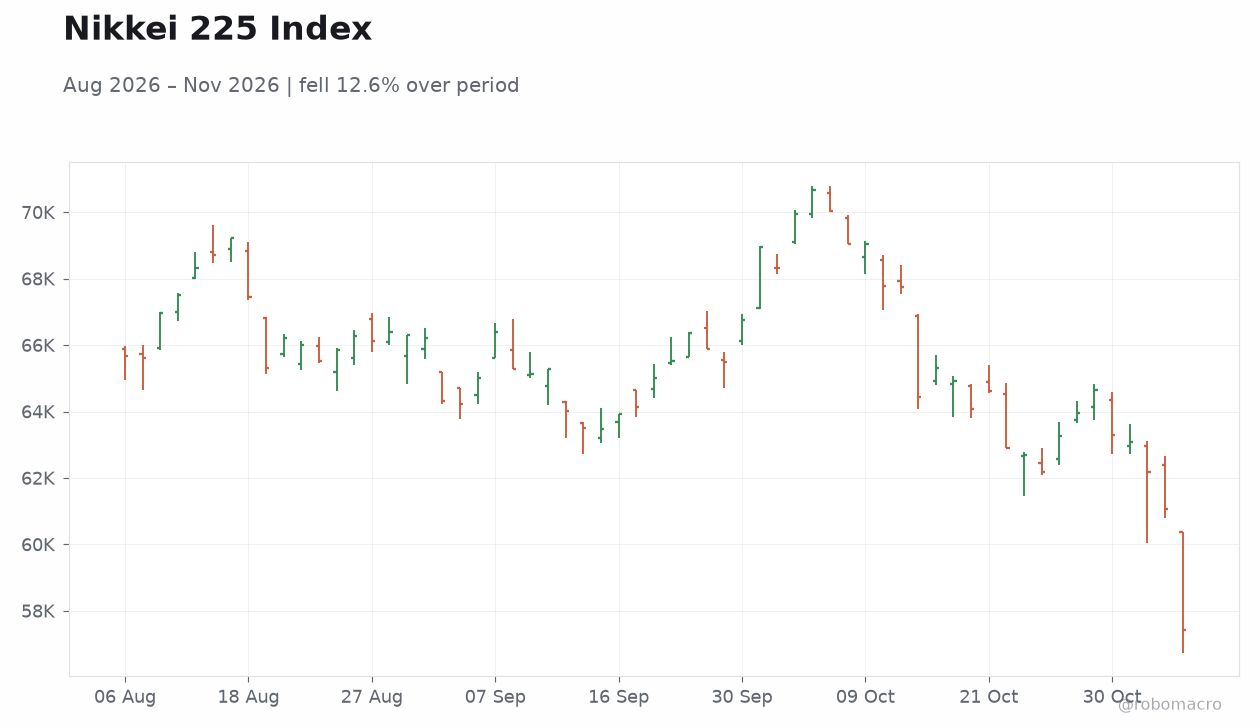
- Nikkei 225 collapses 5.96% to 57,434.77 as BoJ minutes and Ueda remarks cement December rate-hike expectations
- JGB curve bull-steepens; 10Y yield eases 4 bp to 2.81%, 2Y down 3 bp to 1.86% even as hike odds firm
- USD/JPY pushes to 158.35 (+0.54%) despite hawkish BoJ tone, keeping intervention risk elevated
Yesterday's Recap
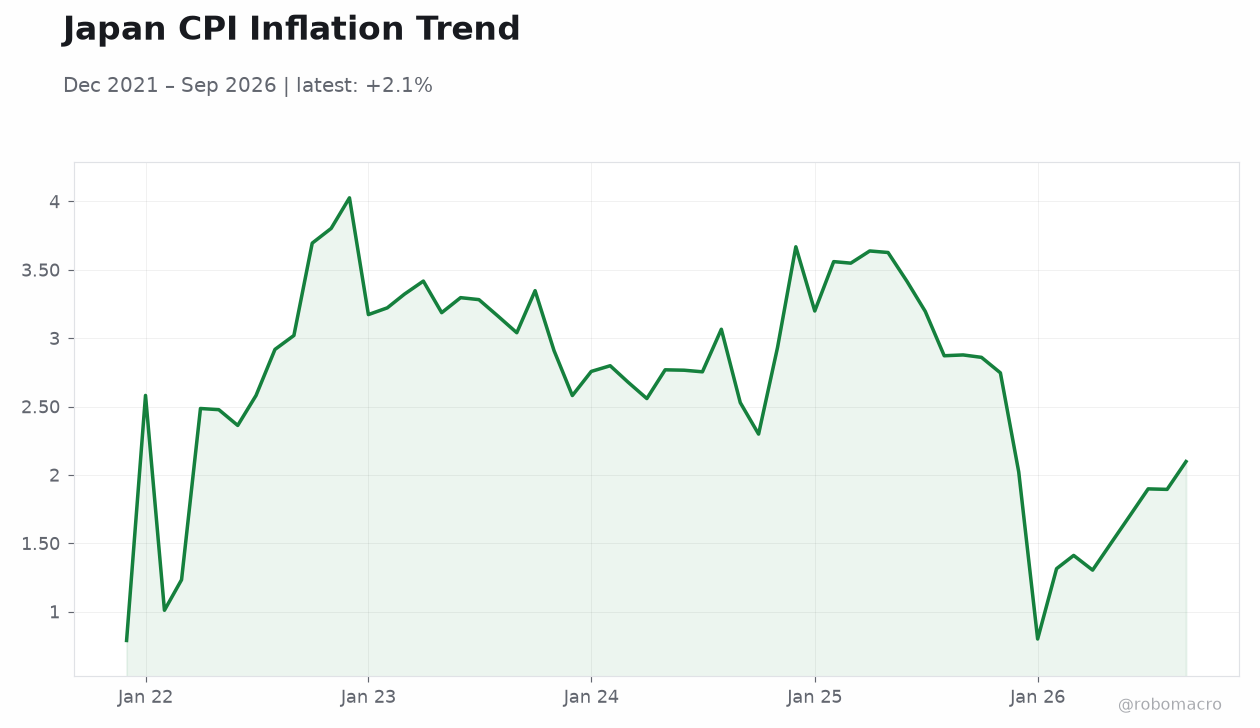
Japan's risk complex sold off violently, with the Nikkei 225 cratering 5.96% to 57,434.77 — its sharpest single-day decline of the cycle — as investors repriced for a December BoJ hike. The trigger was the release of the BoJ Monetary Policy Meeting Minutes from the October 30 hold, which kept further rate increases explicitly in view, reinforced by Governor Ueda's speech. Ueda told an IMF audience that overseas investment income now dominates Japan's current account surplus while labor shortages are reigniting domestic investment, though he cautioned it is unclear how long 2% inflation will persist.
The WSJ framed the communications as the BoJ "declaring inflation win, clearing the way for rate hikes," while the FT cited strong wage growth supporting a December move. Curiously, JGBs rallied against the equity rout: the 10Y yield eased 4 bp to 2.81% and the 2Y slipped 3 bp to 1.86%, a flight-to-quality bid overriding hawkish policy signals. The yen barely benefited, with USD/JPY climbing 0.54% to 158.35 as the dollar held firm, while EUR/JPY and GBP/JPY each eased 0.32%.
Gold fell 0.94% to $4,074.90 and Brent was flat at $98.32.
The Day Ahead
The calendar is empty for Japan on November 8, with no tier-one releases scheduled today or tomorrow, leaving markets to digest the BoJ communications and Friday's equity rout. Trading will be dominated by positioning flows around the 158 yen level and by follow-through in JGBs after the counterintuitive rally. With the next BoJ decision not until December 18, the bulk of near-term direction will come from global rates and risk appetite rather than domestic prints.
Watch for any unscheduled MoF commentary on the yen, given USD/JPY's proximity to intervention-sensitive territory. Domestic data flow resumes later in the week, so today is a pure risk-management session.
Other Economic Notes
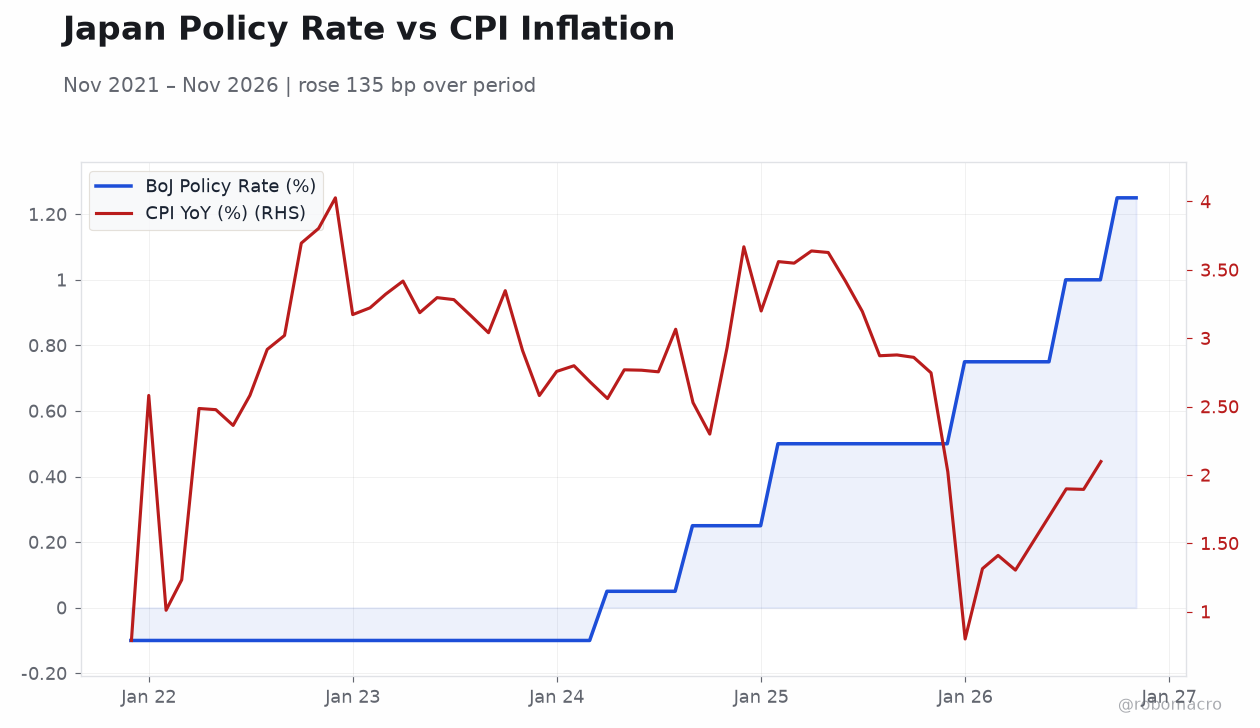
Corporate Japan is quietly benefiting from the weak yen and pricing power — Nikkei Asia reports manufacturers lifting profit outlooks on price hikes and currency tailwinds, a margin story that sits awkwardly against the equity selloff. Household behavior is shifting under higher rates: retail government bonds are selling at a record pace as the 1.25% policy rate pulls money out of deposits, while unprotected deposits have swelled to $890bn on inheritance inflows. ↓ p.2