Japan Macro Daily(Beta Mode)
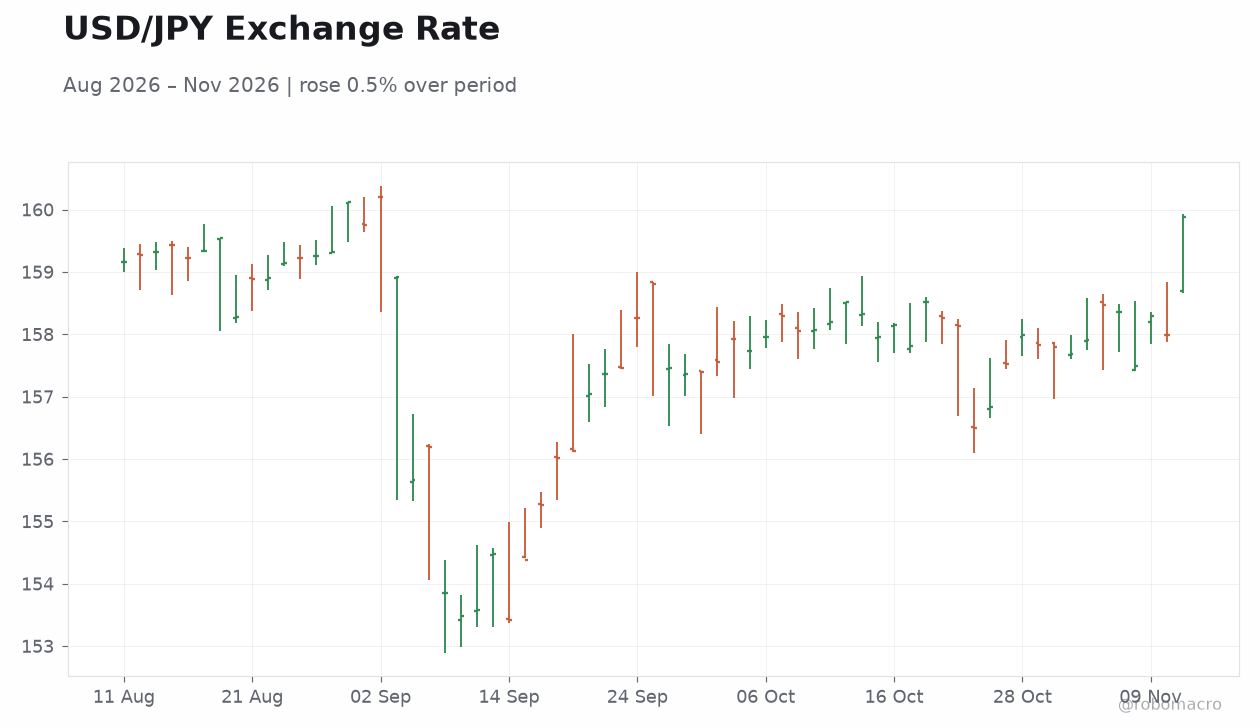
Yen Slides Toward 160 as BoJ Signals Faster Hikes
Market Snapshot
| Asset | Level | Change |
|---|---|---|
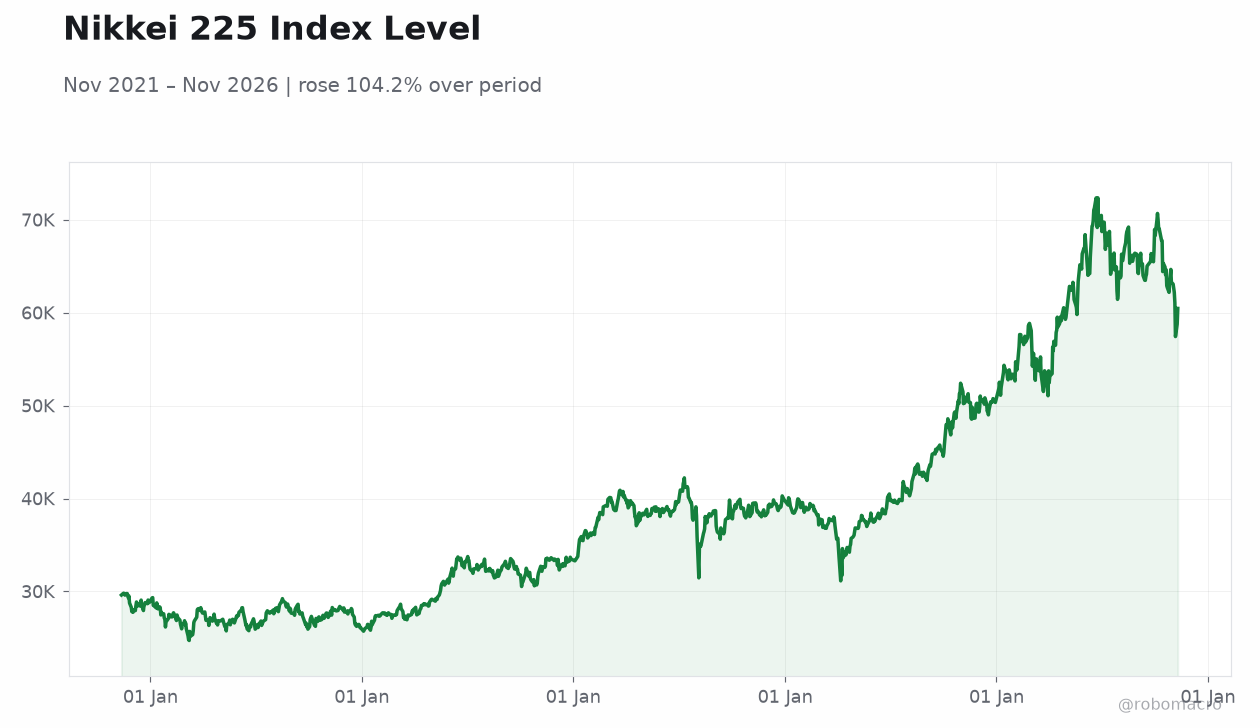
| Nikkei 225 | 60,459.58 | +2.87% |
| USD/JPY | 159.85 | +1.18% |
| EUR/JPY | 177.25 | -0.02% |
| GBP/JPY | 212.20 | -0.07% |
| Gold | 3,994.10 | -0.90% |
| Brent Crude | 92.50 | +1.10% |
| Bitcoin | 74,534.96 | +1.11% |
| Japan 2Y Govt Yield | 1.78% | 0 bp |
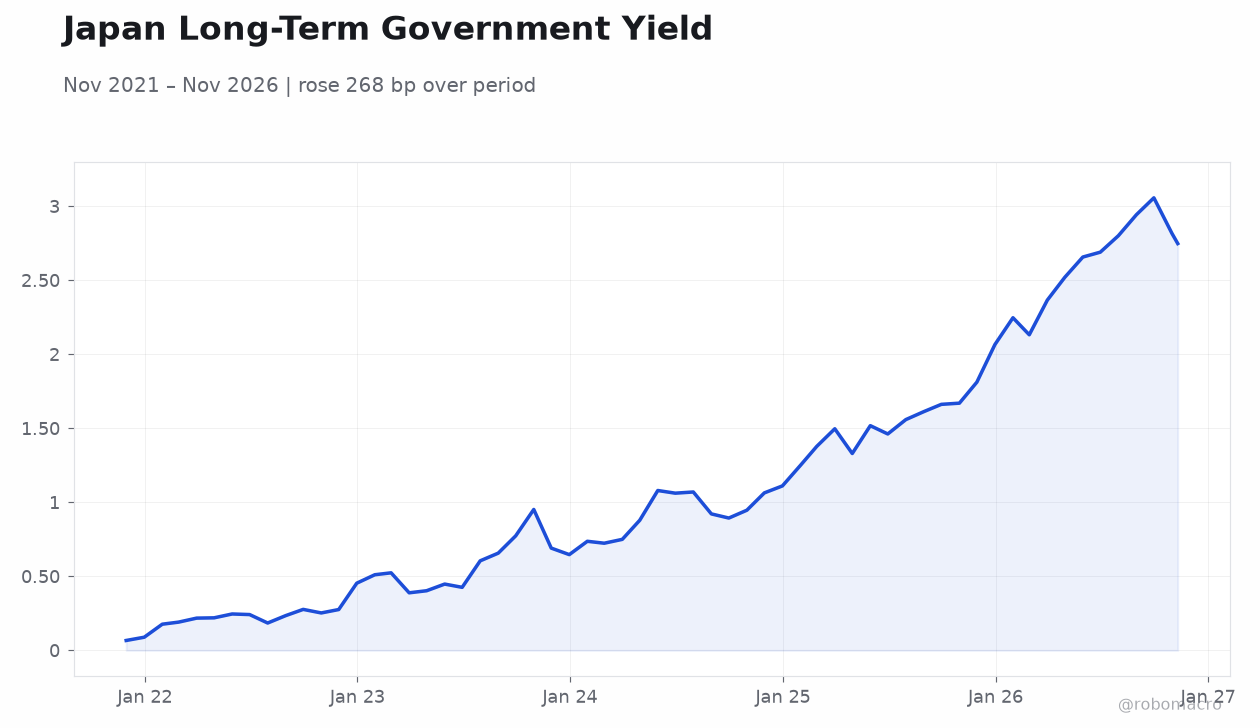
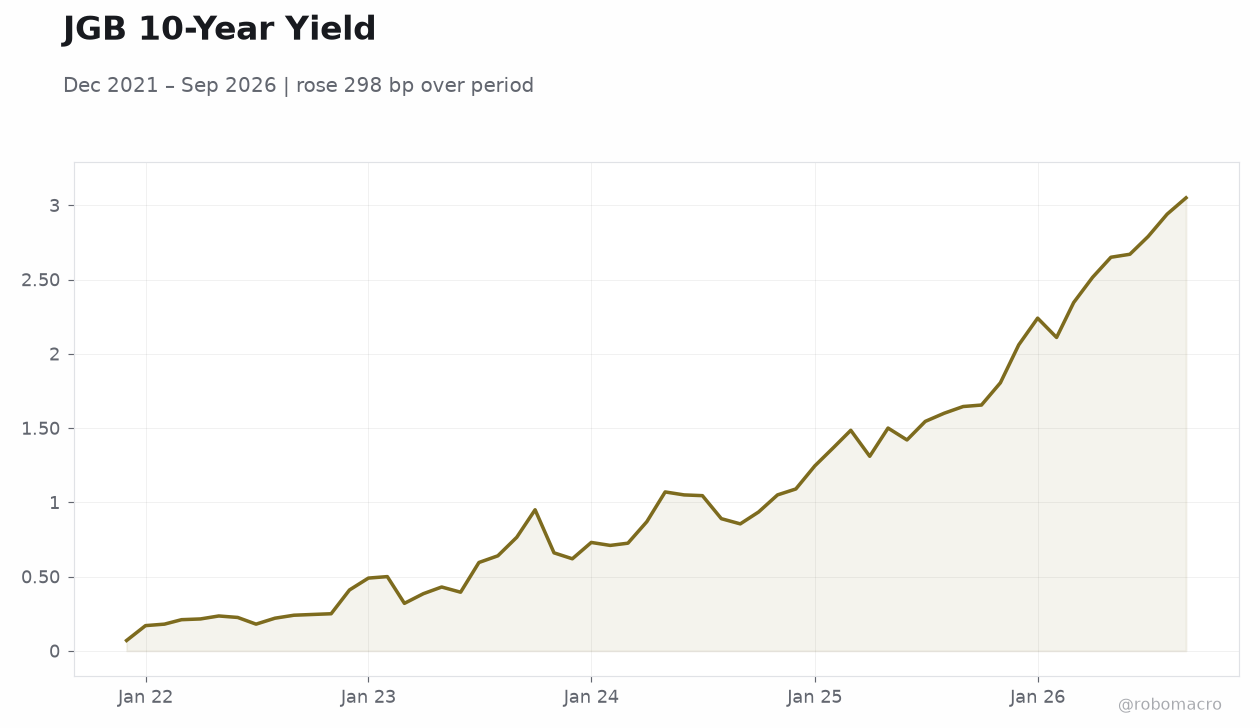
| Japan 10Y Govt Yield | 2.75% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Household Spending Month-over-Month | 0.10 | 0.30 | -2.80 |
| Household Spending Year-over-Year | -3.10 | -3.10 | -6.80 |
| BoJ Summary of Opinions | - | - | - |
| Current Account Balance | 3,993,000m | 3,354,400m | 2,372,000m |
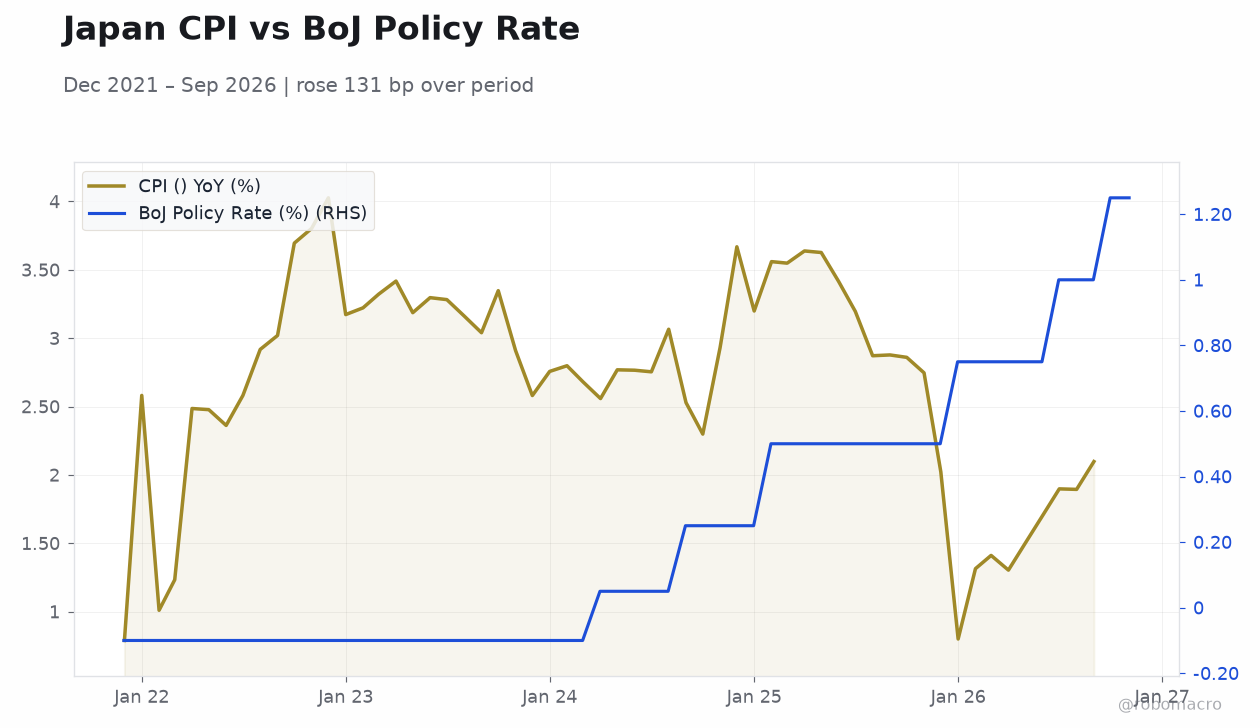 Japan CPI vs BoJ Policy Rate | Type: macro_line | CPI () YoY (%): 2.098 (2026-09-01) | Range: 0.7892–4.027 | Trend(6pt): 0.7892,3.222,2.559,3.416,1.894,2.098 | BoJ Policy Rate (%): 1.25 (2026-11-03) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BOJ Asada Speech | - | - | 20:30 |
| Sunday (2026-11-15) | |||
| GDP Growth Quarter-over-Quarter Preliminary | 0.40 | 0.10 | 18:50 |
| GDP Growth Annualized Prel | 1.40 | 0.30 | 18:50 |
- Household spending collapsed 6.8% y/y in September, far below the -3.1% consensus, underscoring fragile domestic demand even as inflation holds above target.
- The October BoJ Summary of Opinions revealed members pushing for faster rate hikes, sharpening expectations ahead of the December 18 decision.
- USD/JPY pushed to 159.85 (+1.18%) despite a record single-day $50bn FX intervention, while the Nikkei surged 2.87% to 60,459.58 and the 10-year JGB yield rose 3 bp to 2.75%.
Yesterday's Recap
Japan's household spending data printed sharply weaker than expected, with the month-over-month figure at -2.8% versus a 0.3% consensus and the year-over-year reading at -6.8% against expectations of -3.1%, a dramatic deterioration from the prior -3.1% print. The current account balance also came in well below consensus at ¥2.372trn versus a ¥3.354trn forecast, down from the prior ¥3.993trn. The BoJ's October Summary of Opinions was released, revealing a committee increasingly divided on the pace of normalisation, with several members advocating faster rate hikes.
Markets shrugged off the weak data: the Nikkei 225 rallied 2.87% to 60,459.58, the 10-year JGB yield added 3 bp to 2.75%, and the 2-year held at 1.78%. USD/JPY climbed 1.18% to 159.85, pressing against the 160 level despite intervention efforts, while EUR/JPY and GBP/JPY were essentially flat.
The Day Ahead
The calendar is light, with the sole scheduled event being BoJ board member Asada's speech at 20:30 ET, which will be scrutinised for any steer on the December 18 policy decision following the hawkish Summary of Opinions. Attention then shifts to Sunday's preliminary Q3 GDP release, where quarter-over-quarter growth is expected at 0.1% versus the prior 0.4%, and the annualised figure is seen at 0.3% against 1.4% previously. A downside surprise would complicate the case for a near-term hike, while a resilient print would reinforce the normalisation narrative.
With USD/JPY hovering just below 160, intervention risk remains elevated and Asada's tone could be the marginal catalyst for yen direction into the weekend.
Other Economic Notes
The gap between firming inflation and collapsing household spending is the central tension in Japan's macro picture. CPI at 2.10% y/y keeps the BoJ's price goal in view, yet the -6.8% y/y spending contraction signals that real incomes remain squeezed. Government advisors have urged a focus on sustaining growth now that inflation has reached the BoJ's target, hinting at caution about over-tightening.
↓ p.2