Japan Macro Daily(Beta Mode)
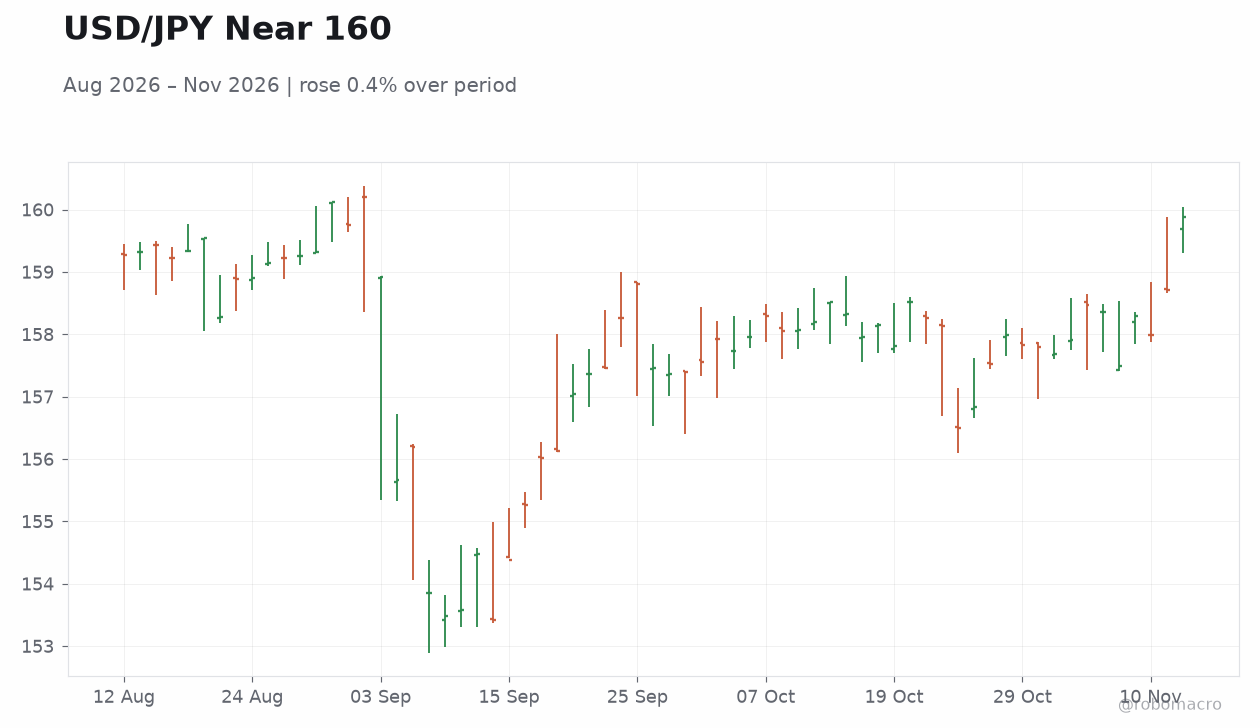
Yen Nears 160 as BoJ Split Widens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
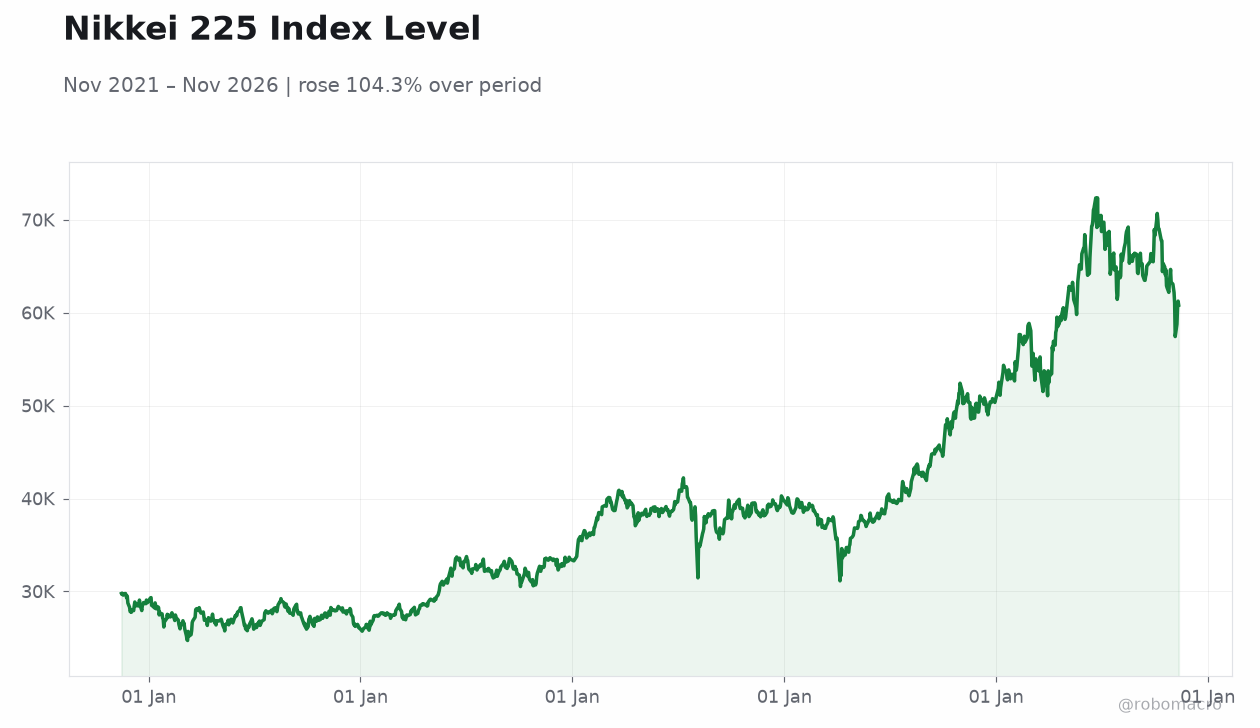
| Nikkei 225 | 61,248.59 | +1.31% |
| USD/JPY | 159.89 | +0.75% |
| EUR/JPY | 176.78 | -0.27% |
| GBP/JPY | 211.66 | -0.09% |
| Gold | 3,882.00 | -2.96% |
| Brent Crude | 96.02 | +3.51% |
| Bitcoin | 71,387.31 | -3.48% |
| Japan 2Y Govt Yield | 1.86% | +8 bp |
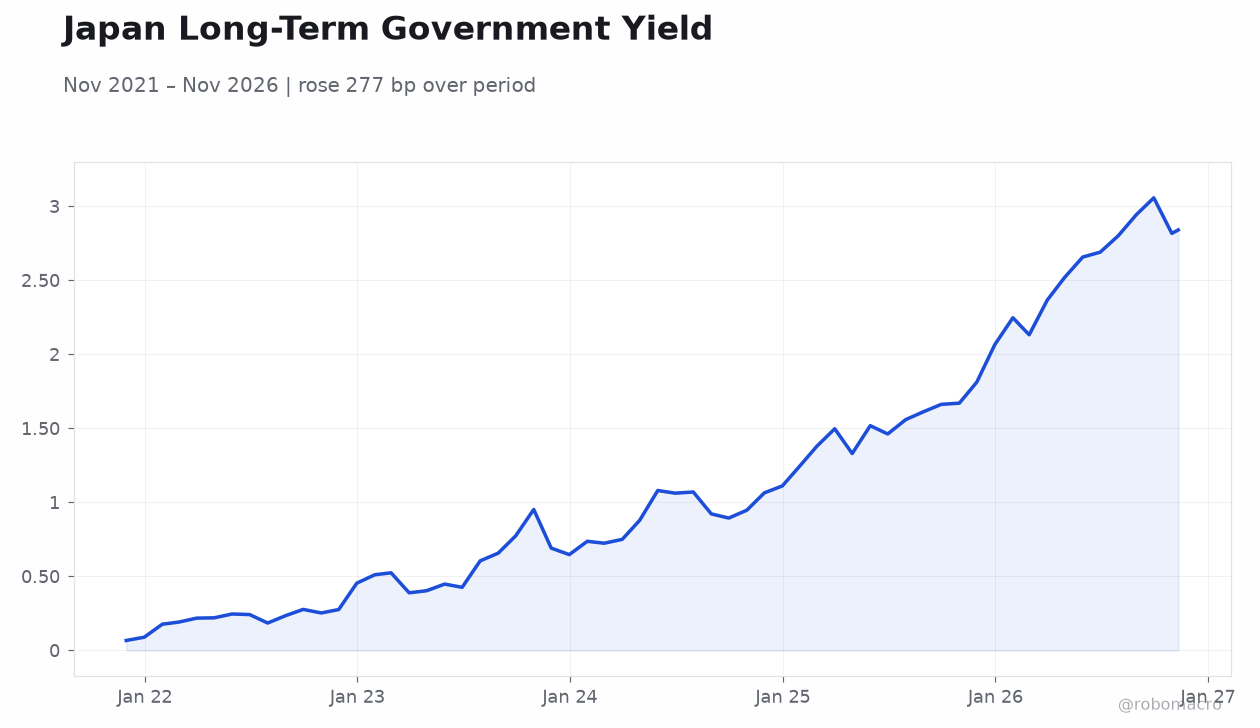
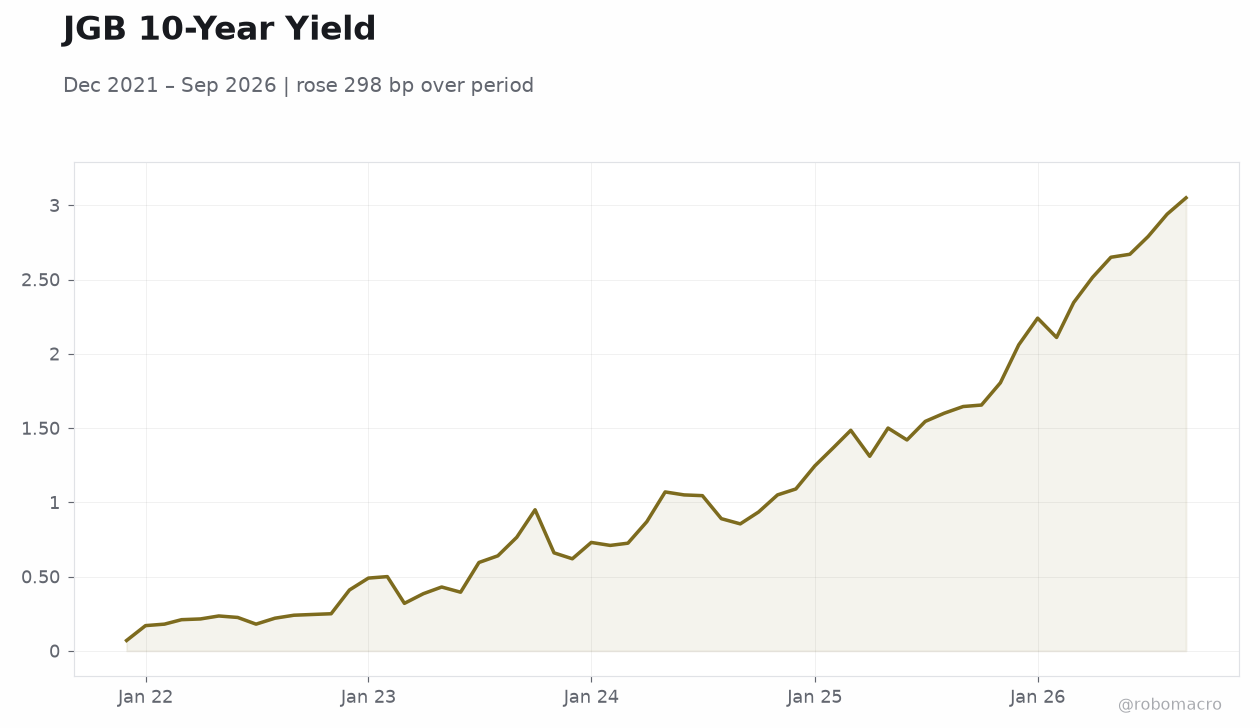
| Japan 10Y Govt Yield | 2.84% | +9 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Household Spending Month-over-Month | 0.10 | 0.30 | -2.80 |
| Household Spending Year-over-Year | -3.10 | -3.10 | -6.80 |
| BoJ Summary of Opinions | - | - | - |
| Current Account Balance | 3,993,000m | 3,354,400m | 2,372,000m |
| BOJ Asada Speech | - | - | - |
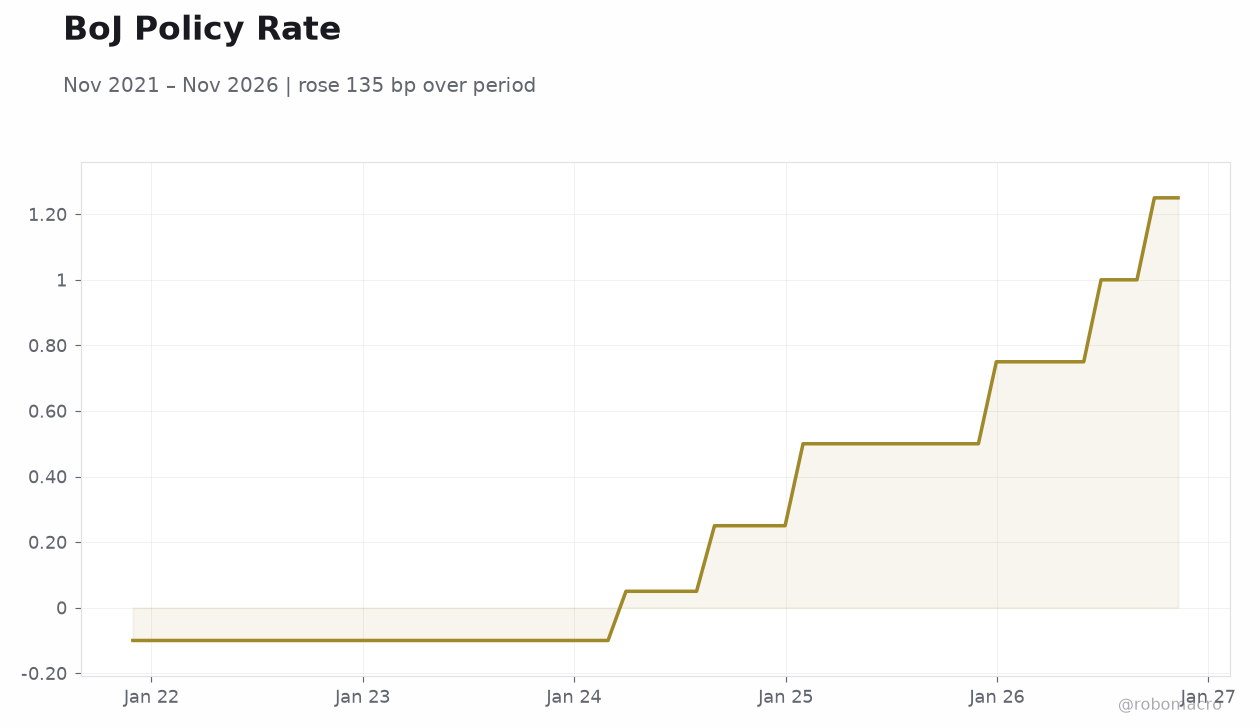 BoJ Policy Rate | Type: macro_line | Policy Rate (%): 1.25 (2026-11-10) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Sunday (2026-11-15) | |||
| GDP Growth Quarter-over-Quarter Preliminary | 0.40 | 0.10 | 18:50 |
| GDP Growth Annualized Prel | 1.40 | 0.30 | 18:50 |
- USD/JPY at 159.89 (+0.75%) stalls just shy of the 160 intervention line as the top currency diplomat warns the fall is "too rapid"
- JGB curve bear-steepened: 10Y at 2.84% (+9bp), 2Y at 1.86% (+8bp) on hawkish repricing despite dovish Asada remarks
- Household spending collapsed -6.8% y/y and -2.8% m/m, far below consensus, underscoring fragile domestic demand
Yesterday's Recap
Japan's household spending printed sharply weaker than expected, falling 6.8% y/y versus consensus of -3.1% and -2.8% m/m against a +0.3% forecast, a stark signal that consumption is buckling under persistent price pressure. The current account surplus narrowed to ¥2.37trn, well below the ¥3.35trn consensus and prior ¥3.99trn. The BoJ Summary of Opinions was released, and dovish board member Asada delivered a high-impact speech urging caution on the pace of rate hikes, arguing inflation is not demand-driven.
Despite that dovish tone, JGBs sold off, with the 10-year yield rising 9bp to 2.84% and the 2-year up 8bp to 1.86%. The Nikkei 225 rallied 1.31% to 61,248.59, helped by a weaker yen. USD/JPY climbed 0.75% to 159.89, halting a few pips shy of the psychologically important 160 level, while EUR/JPY slipped 0.27% to 176.78.
The Day Ahead
The calendar is empty for Thursday, with attention shifting to Sunday's (Nov 15) Q3 GDP preliminary release at 18:50 ET. Consensus looks for just 0.1% q/q growth, a sharp deceleration from the prior 0.4%, with the annualized print expected at 0.3% versus 1.4% previously. That GDP release will be the key test of whether Japan's recovery can absorb further policy normalisation.
With no domestic data Thursday, yen price action and intervention rhetoric will dominate the session. Traders will also watch for any follow-through from Asada's dovish comments ahead of the December 18 BoJ decision.
Other Economic Notes
Producer inflation accelerated to 7.1% in October, while import prices jumped 24.8%, keeping cost-push pressure intense and complicating the BoJ's December calculus. Household spending's -6.8% y/y collapse signals real incomes remain squeezed even as headline CPI sits at 2.10%. A government economic panel argued 2% inflation "isn't the finish line," and advisors urged focus on sustaining growth once the BoJ target is met.
The tension between weak consumption and sticky inflation defines the policy dilemma into year-end.