Japan Macro Daily(Beta Mode)
Yen Breaches 160 as GDP, Inflation Tests Loom
Market Snapshot
| Asset | Level | Change |
|---|---|---|
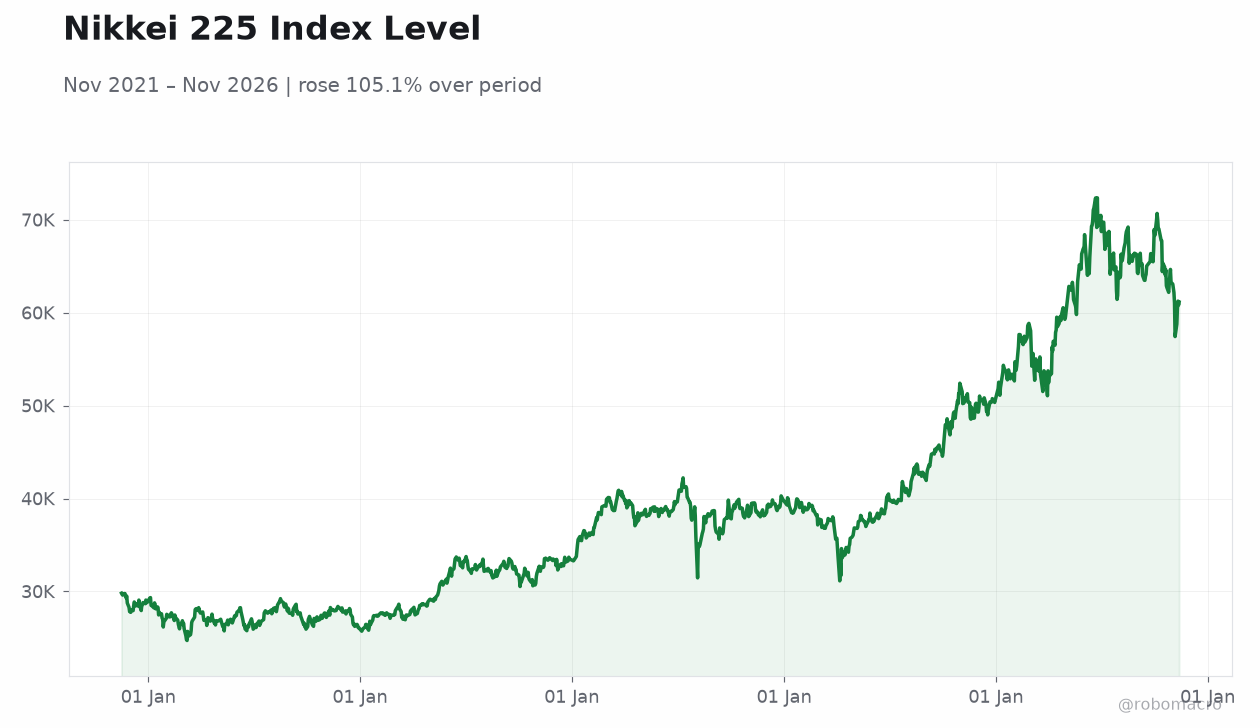
| Nikkei 225 | 61,142.35 | +0.53% |
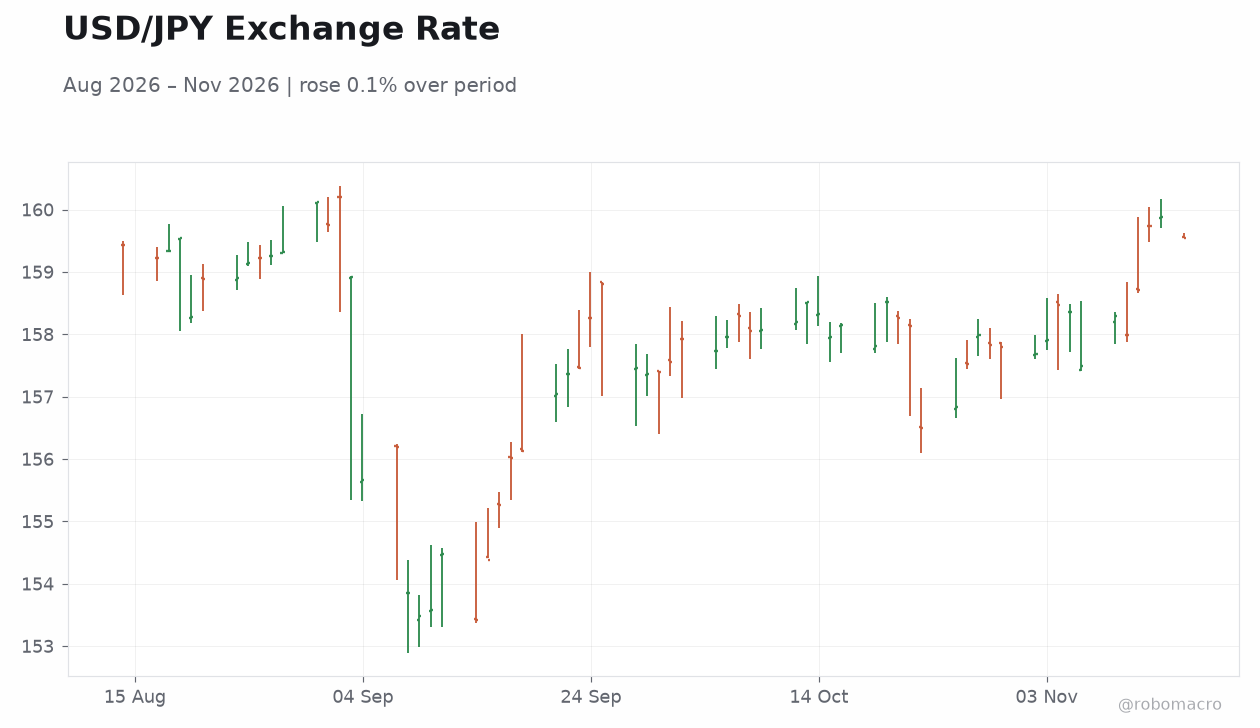
| USD/JPY | 159.54 | -0.21% |
| EUR/JPY | 176.07 | -0.33% |
| GBP/JPY | 210.84 | -0.33% |
| Gold | 3,886.30 | +0.03% |
| Brent Crude | 95.84 | +0.02% |
| Bitcoin | 65,055.99 | +1.45% |
| Japan 2Y Govt Yield | 1.86% | 0 bp |
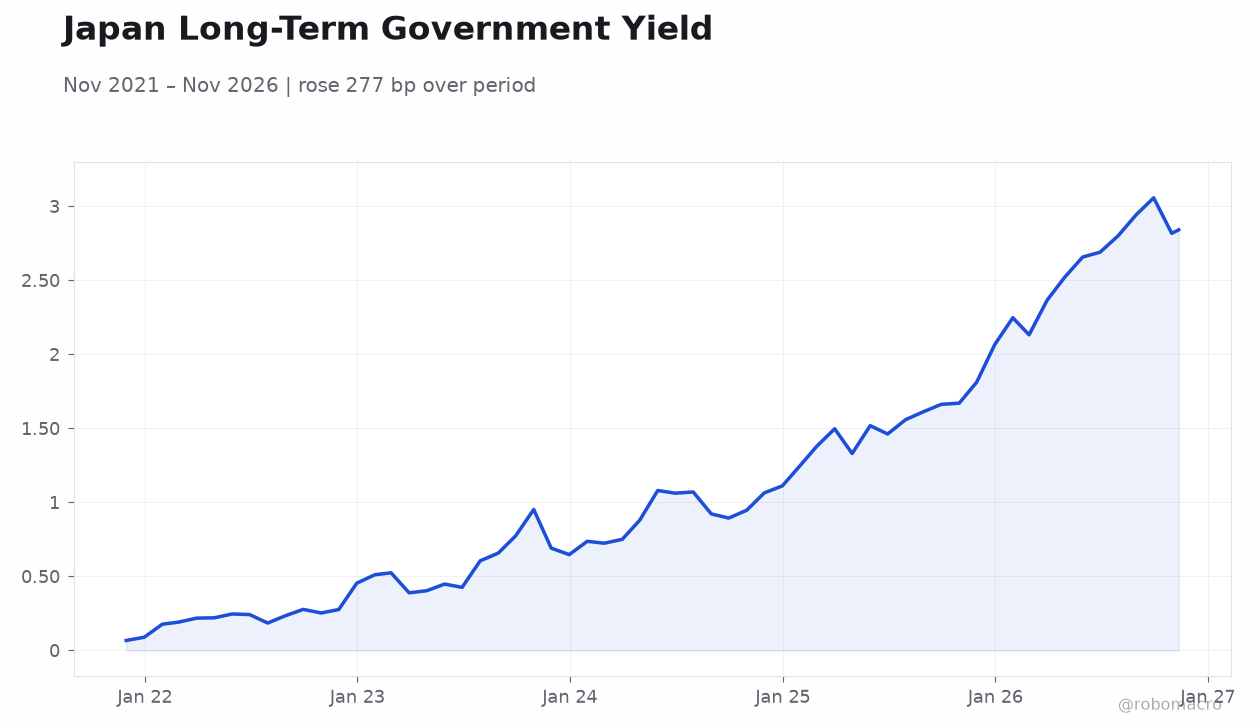
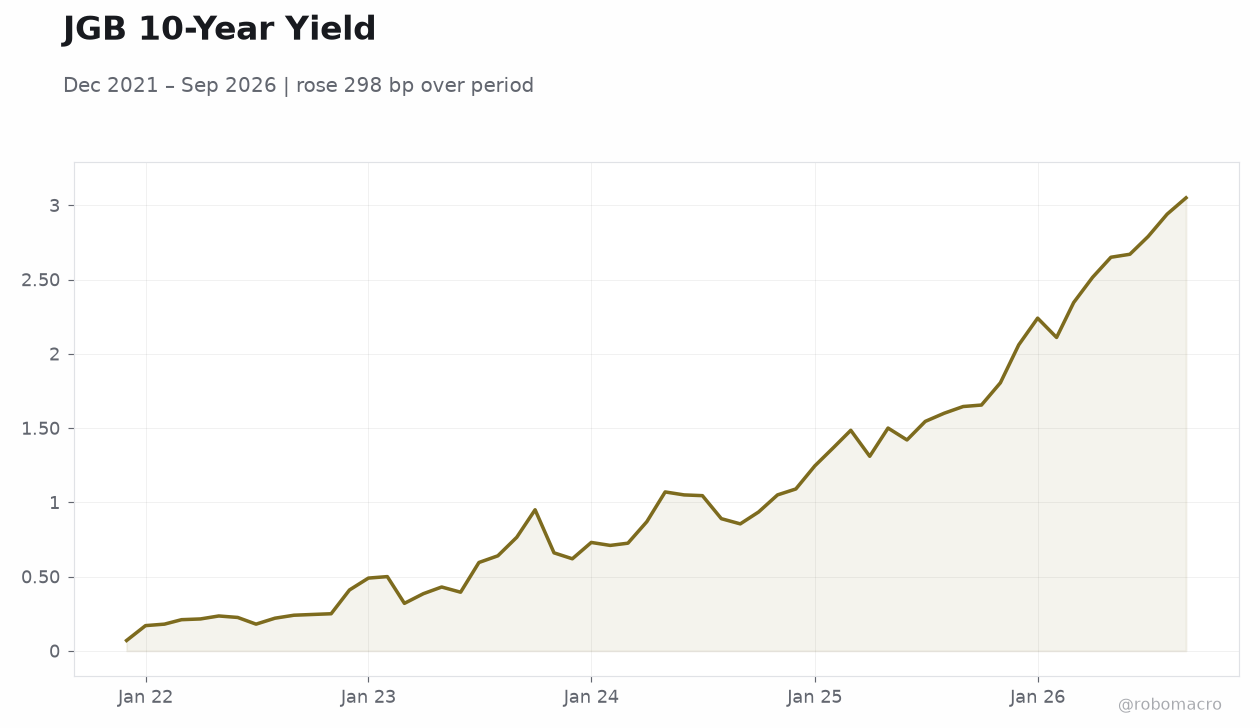
| Japan 10Y Govt Yield | 2.84% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Household Spending Month-over-Month | 0.10 | 0.30 | -2.80 |
| Household Spending Year-over-Year | -3.10 | -3.10 | -6.80 |
| BoJ Summary of Opinions | - | - | - |
| Current Account Balance | 3,993,000m | 3,354,400m | 2,372,000m |
| BOJ Asada Speech | - | - | - |
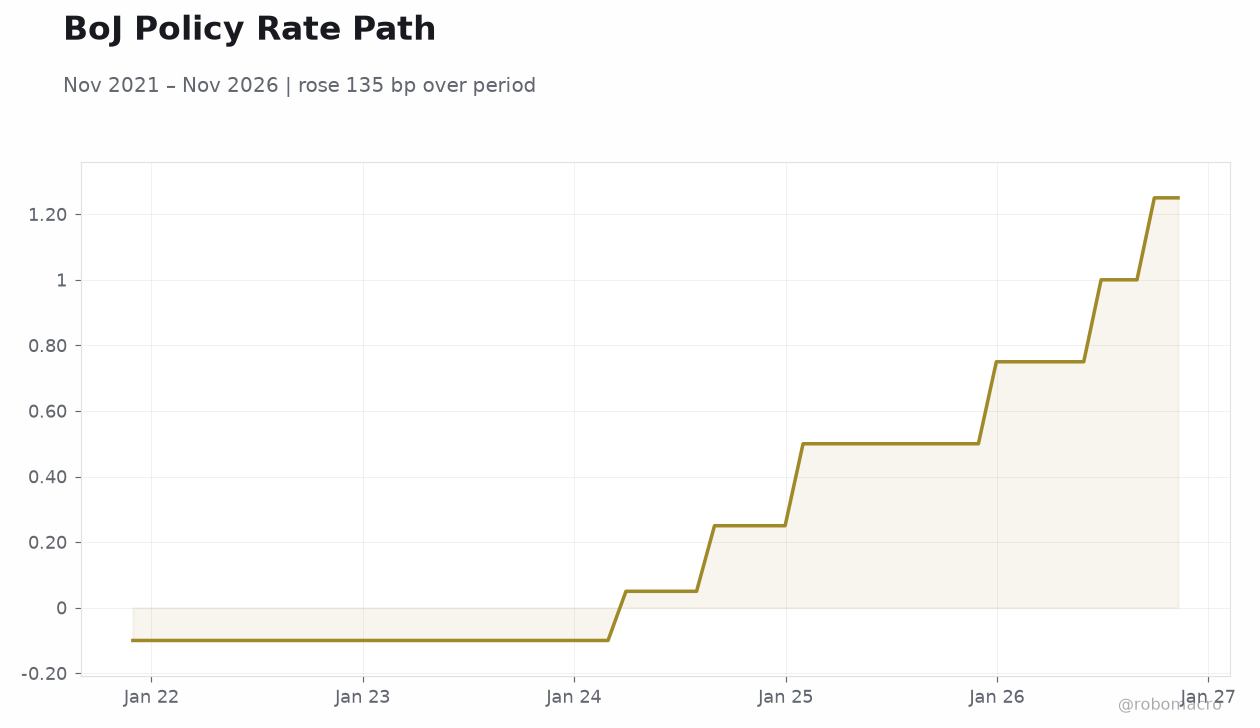 BoJ Policy Rate Path | Type: macro_line | Policy Rate (%): 1.25 (2026-11-10) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| GDP Growth Quarter-over-Quarter Preliminary | 0.40 | 0.10 | 18:50 |
| GDP Growth Annualized Prel | 1.40 | 0.30 | 18:50 |
- USD/JPY pushed through the 160 threshold, triggering verbal intervention from the finance minister and keeping December BoJ hike bets alive.
- Household spending collapsed 6.8% y/y in the November 9 print, far below consensus, underscoring fragile domestic demand even as wholesale inflation accelerates.
- Q3 GDP preliminary lands today at 18:50 ET with consensus at just 0.1% q/q, a sharp deceleration from the prior 0.4%.
Yesterday's Recap
Japan's data calendar delivered a stark warning on the consumer. Household spending fell 6.8% y/y against consensus of -3.1%, and -2.8% m/m versus an expected +0.3% — a severe miss that suggests real incomes remain squeezed despite nominal wage gains. The current account balance printed at ¥2.372trn, well below the ¥3.354trn consensus and the prior ¥3.993trn, reflecting a deteriorating trade position.
The BoJ Summary of Opinions from the October 30 hold drew attention for signals on the December path. BoJ board member Asada's speech on November 11 was flagged high-impact and reinforced the normalisation bias. Markets were mixed: the Nikkei 225 rose 0.53% to 61,142.35, while USD/JPY eased 0.21% to 159.54 after touching 160.
JGB yields were unchanged, with the 10-year at 2.84% and the 2-year at 1.86%.
The Day Ahead
The Q3 GDP preliminary release at 18:50 ET is the dominant event, with consensus at 0.1% q/q versus the prior 0.4% — a near-stall that would complicate the BoJ's December calculus. The annualised figure is expected at 0.3% versus 1.4% previously. A downside surprise would sharpen the tension between a weakening real economy and accelerating cost-push inflation.
No Japanese releases are scheduled for November 16. Traders will watch whether USD/JPY holds above 160 into the GDP print, with intervention risk elevated.
Other Economic Notes
Japan's wholesale inflation is accelerating, keeping the BoJ's rate-hike view intact even as household demand crumbles — a classic stagflationary squeeze. The top three banking groups lifted profit outlooks on the back of higher policy rates, illustrating how normalisation is reshaping sector earnings. The yen's slide to 160 and beyond is now the central macro variable, feeding imported inflation and pressuring the BoJ toward faster action.
The divergence between firm-level pricing power and household purchasing power is the key vulnerability in the outlook.