Japan Macro Daily(Beta Mode)
Yen Falls Despite GDP Contraction; BoJ Hike Bets Hold
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| Nikkei 225 | 59,662.02 | -2.42% |
| USD/JPY | 159.35 | -0.27% |
| EUR/JPY | 175.37 | -0.45% |
| GBP/JPY | 210.47 | -0.33% |
| Gold | 3,848.50 | -0.12% |
| Brent Crude | 92.83 | +0.42% |
| Bitcoin | 64,006.02 | -1.31% |
| Japan 2Y Govt Yield | 1.88% | 0 bp |
| Japan 10Y Govt Yield | 2.93% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
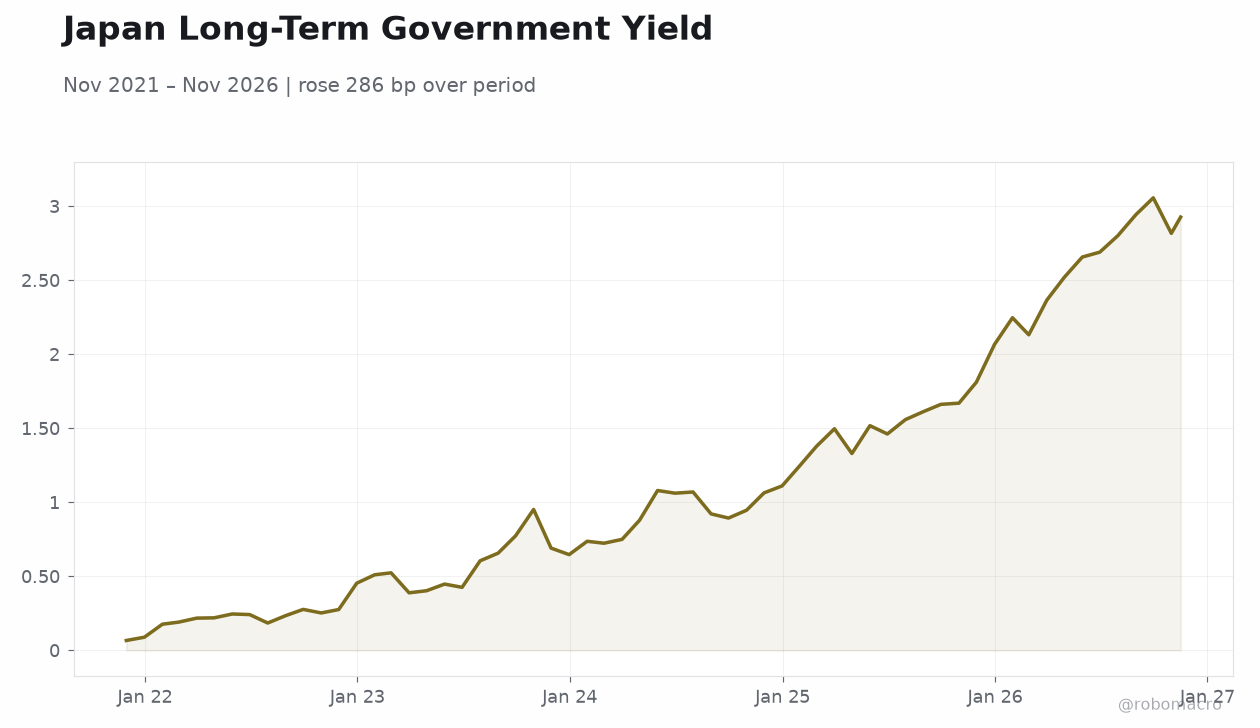
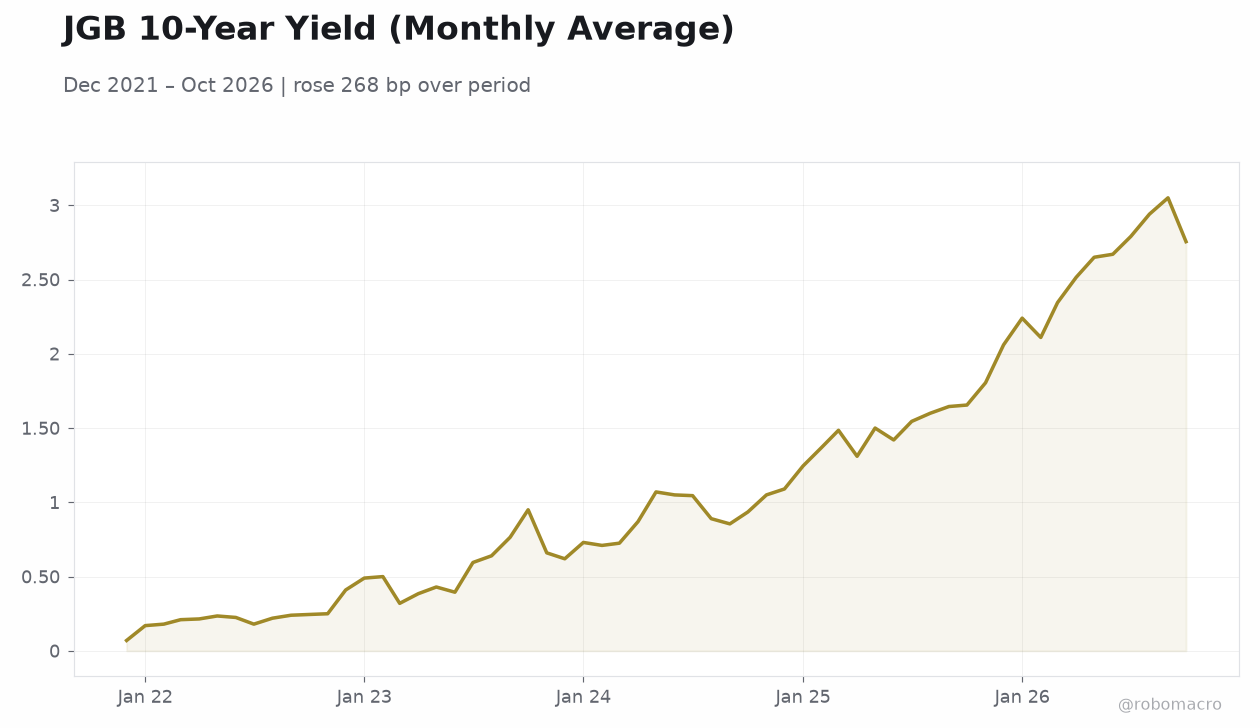 JGB 10-Year Yield (Monthly Average) | Type: macro_line | JGB 10-Year Yield (Monthly Average): 2.93 (2026-11-16) | Range: 0.07–3.05 | Trend(6pt): 0.07,0.5,0.87,1.42,2.94,2.755
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | -536,600m | -956,000m | 18:50 |
| Exports Year-over-Year | 16.70 | 20 | 18:50 |
| Wednesday (2026-11-18) | |||
| Machinery Orders Month-over-Month | 5.20 | -0.50 | 18:50 |
| Machinery Orders Year-over-Year | 18.60 | 13.70 | 18:50 |
| Thursday (2026-11-19) | |||
| Inflation Rate Year-over-Year | 2.10 | - | 18:30 |
| Core Inflation Rate Year-over-Year | 2.10 | 2.30 | 18:30 |
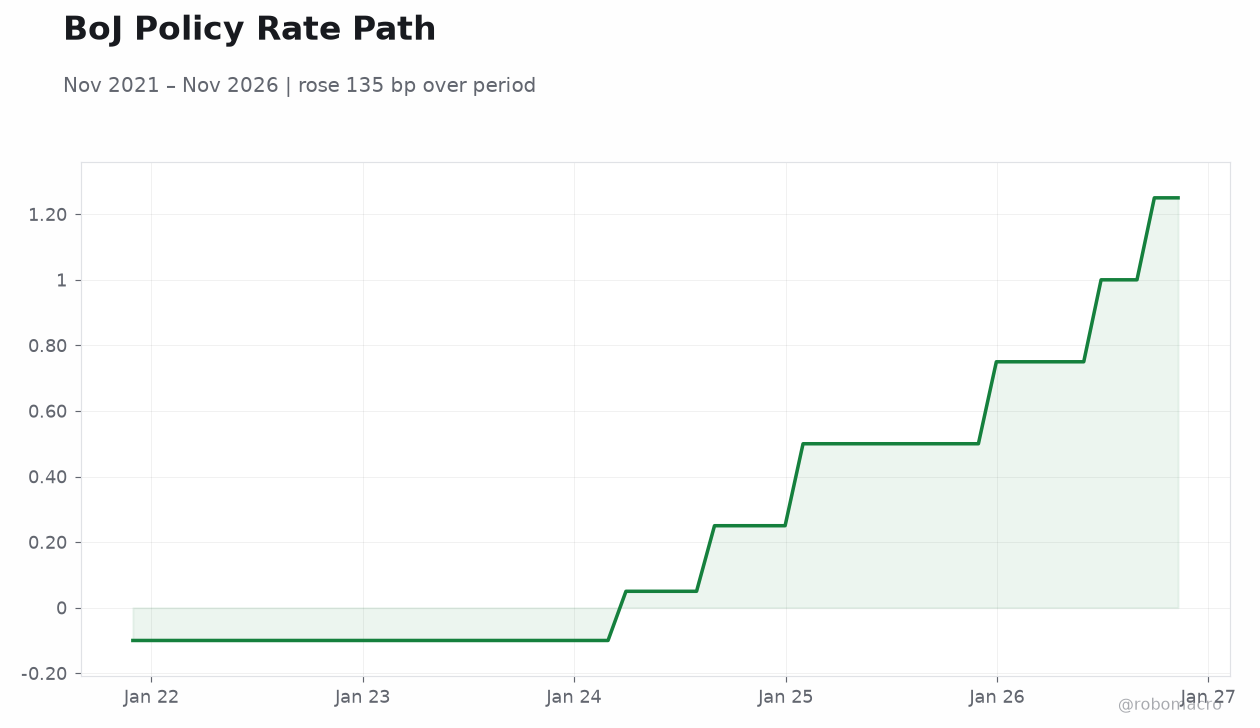
- Japan's Q3 GDP unexpectedly contracted an annualized 0.1%, missing expectations and complicating the BoJ's December rate-hike path
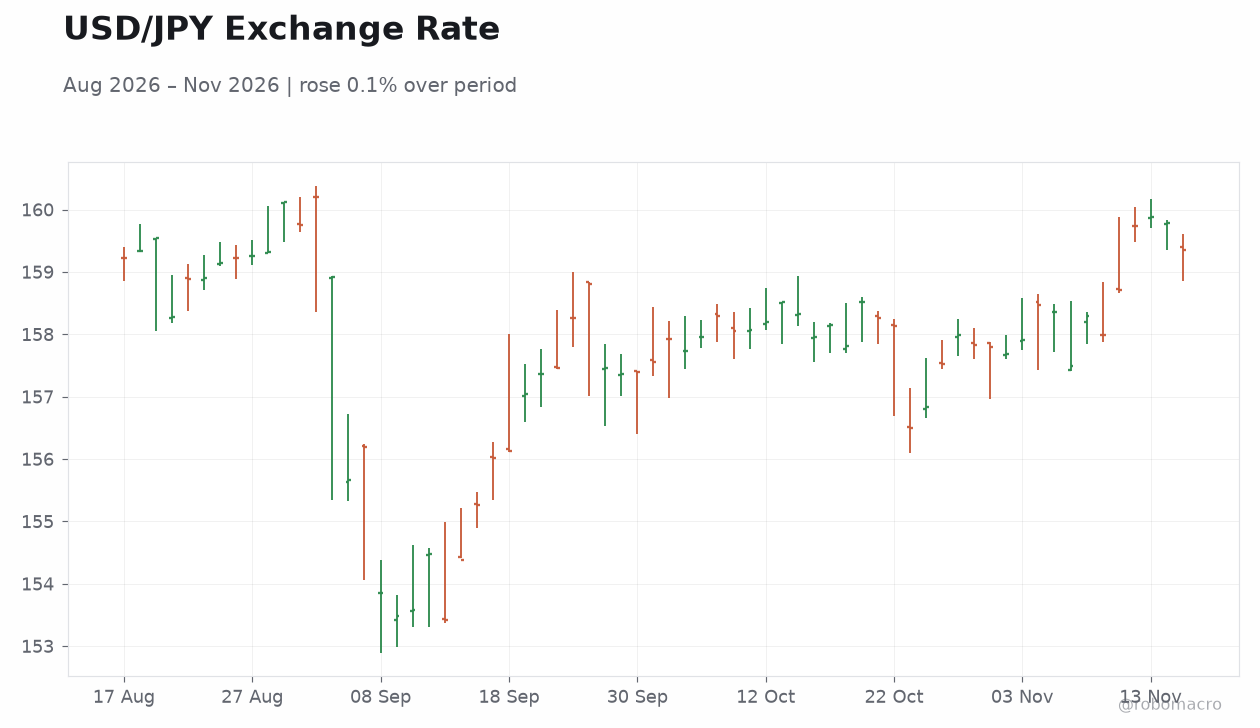
- USD/JPY holds near 159.35 despite soft growth data, with intervention risk rising as the pair hovers near two-month lows
- October CPI due Thursday; consensus sees core inflation accelerating to 2.3% from 2.1%, keeping normalization pressure alive
Yesterday's Recap
Japan's economy unexpectedly shrank in Q3, with GDP contracting an annualized 0.1% versus market expectations for modest growth, as inflation continued to squeeze household spending. The weak print initially lifted the yen on intervention-risk hedging, but the currency gave back gains as traders looked past the soft data toward the BoJ's December meeting. The Nikkei 225 fell 2.42% to 59,662.02, reflecting broad risk-off sentiment and disappointment over the growth outlook.
USD/JPY eased 0.27% to 159.35, while EUR/JPY slipped 0.45% to 175.37 and GBP/JPY fell 0.33% to 210.47. JGB yields were mixed: the 10-year rose 3 bp to 2.93% while the 2-year held at 1.88%, steepening the curve slightly. Gold dipped 0.12% to 3,848.50, and Brent crude gained 0.42% to 92.83.
The Day Ahead
Japan's October trade balance is due at 18:50 ET today, with consensus forecasting a wider deficit of ¥956 billion versus the prior ¥536.6 billion shortfall. October exports year-over-year are expected to accelerate to 20% from 16.7%, suggesting external demand remains a rare bright spot. Wednesday brings September machinery orders, where consensus points to a 0.5% month-over-month decline following August's 5.2% gain, with the year-over-year figure seen slowing to 13.7% from 18.6%.
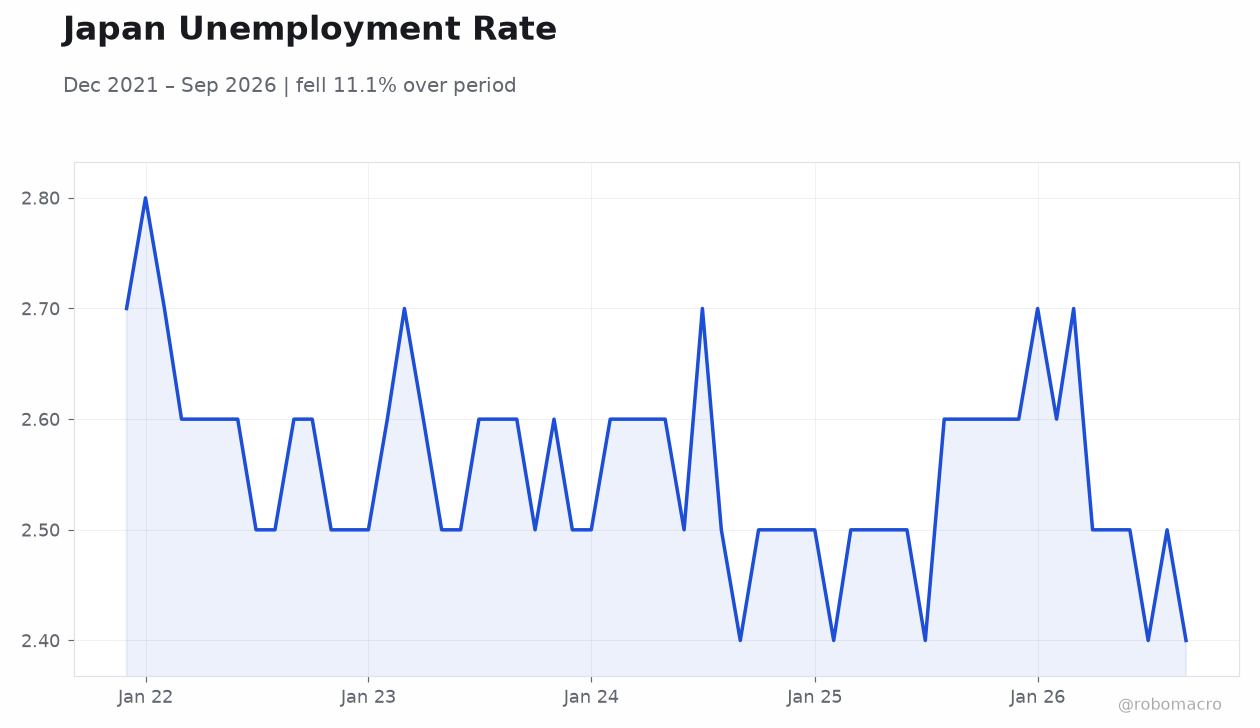
Thursday's October CPI release is the week's key event: core inflation is expected to rise to 2.3% from 2.1%, a print that would reinforce the case for a December BoJ hike.
Other Economic Notes
The Q3 contraction underscores the fragility of Japan's domestic recovery, with consumption weakening as real incomes remain pressured by inflation above the BoJ's 2% target. Economy Minister Minoru Kiuchi distanced himself from calling for a near-term rate hike, citing the GDP slowdown and deferring the decision to the BoJ. Machinery orders will be watched for capex momentum after August's strong gain, though consensus anticipates a pullback.
The trade data will clarify whether export strength can offset import costs driven by elevated energy prices. Overall, the growth-inflation mix remains uncomfortable: stagflationary dynamics complicate the normalization path.