Japan Macro Daily(Beta Mode)
BoJ Governor Urges More Hikes as Yen Nears 160
Market Snapshot
| Asset | Level | Change |
|---|---|---|
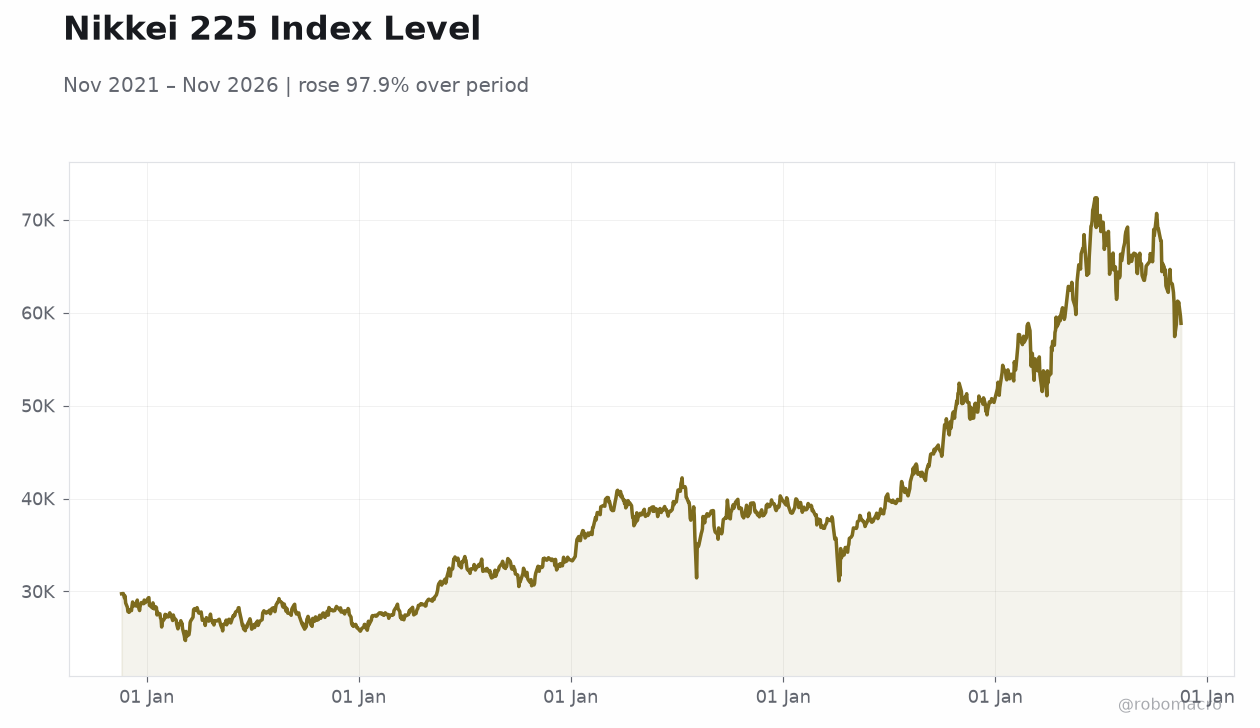
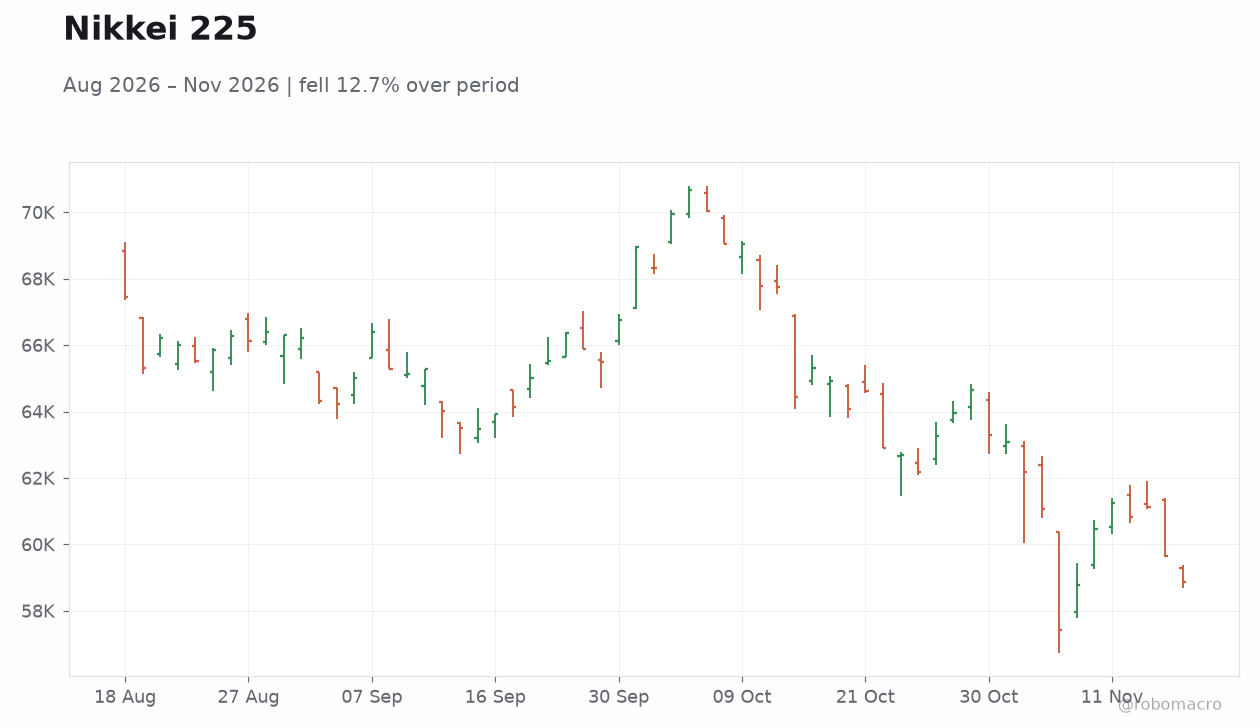
| Nikkei 225 | 58,860.43 | -1.34% |
| USD/JPY | 159.36 | -0.10% |
| EUR/JPY | 174.88 | -0.32% |
| GBP/JPY | 209.51 | -0.38% |
| Gold | 3,731.60 | -3.43% |
| Brent Crude | 88.68 | -4.79% |
| Bitcoin | 62,487.39 | -3.71% |
| Japan 2Y Govt Yield | 1.88% | 0 bp |
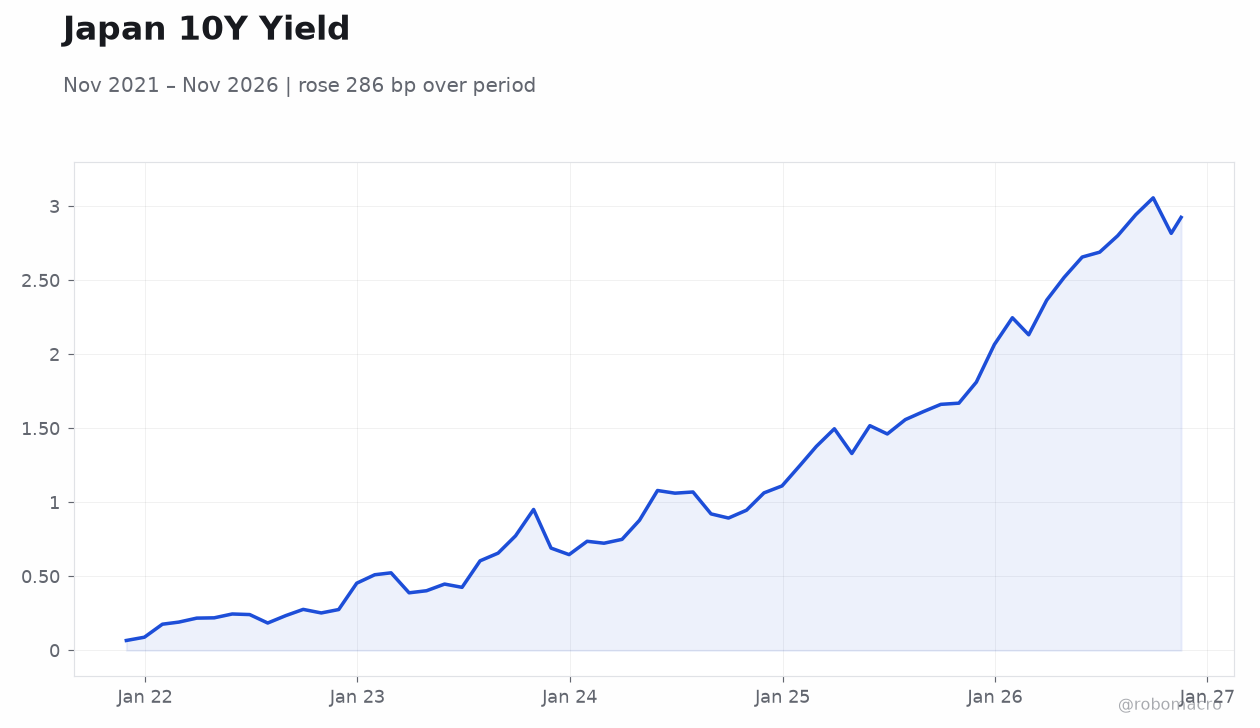
| Japan 10Y Govt Yield | 2.92% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | -536.6m | -956,000m | -476.5m |
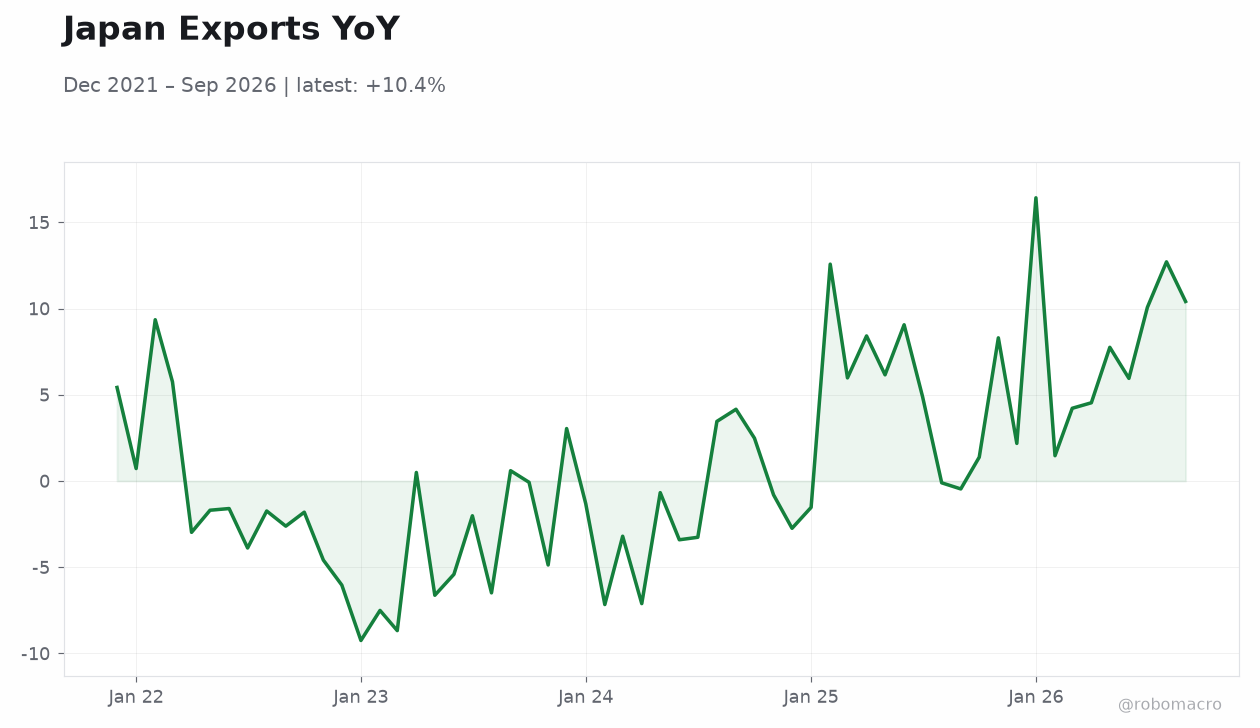
| Exports Year-over-Year | 16.70 | 20 | 20.50 |
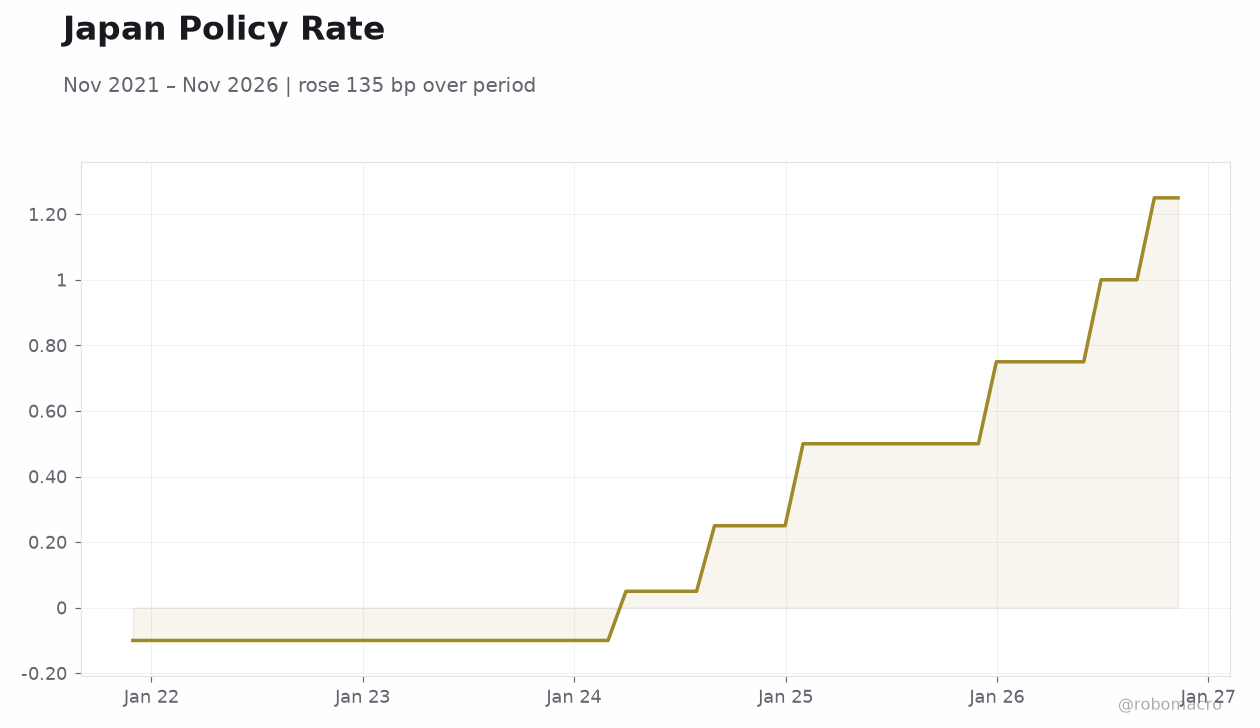 Japan Policy Rate | Type: macro_line | Policy Rate %: 1.25 (2026-11-10) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Machinery Orders Month-over-Month | 5.20 | -0.50 | 18:50 |
| Machinery Orders Year-over-Year | 18.60 | 13.70 | 18:50 |
| Thursday (2026-11-19) | |||
| Inflation Rate Year-over-Year | 2.10 | - | 18:30 |
| Core Inflation Rate Year-over-Year | 2.10 | 2.30 | 18:30 |
- Exports beat forecasts while trade deficit narrowed sharply, supporting external demand resilience.
- Nikkei 225 fell 1.34% to 58,860.43 as AI-driven gains cooled and yen held near intervention thresholds.
- BoJ Governor Ueda reiterated the need for further rate increases, keeping December normalisation in play.
Yesterday's Recap
Japan reported a narrower trade deficit of -476,500,000 yen on 17 November, beating the -956,000,000,000 consensus, while exports rose 20.5% year-over-year against 20% expected. The data underscored continued strength in external shipments despite global headwinds. Equities sold off, with the Nikkei 225 declining 1.34% to close at 58,860.43 amid fading AI momentum.
The 10-year JGB yield eased 1 basis point to 2.92% while the 2-year held steady at 1.88%. USD/JPY traded around 159.36, down 0.10%, as verbal warnings from officials kept intervention risk elevated. Cross rates also softened, with EUR/JPY falling 0.32% and GBP/JPY dropping 0.38%.
Markets digested the mixed signals ahead of fresh inflation prints.
The Day Ahead
Machinery orders for October are due at 18:50 JST today, with month-over-month expected to contract 0.5% after September’s 5.2% rise. The year-over-year reading is forecast at 13.7% versus 18.6% previously. Attention then shifts to 19 November for October CPI, where the headline rate and core measure will clarify whether price pressures are reaccelerating.
Core inflation is projected at 2.3% year-over-year. Any upside surprise could reinforce the case for a December policy adjustment. Traders will also monitor yen volatility for signs of official intervention.
Other Economic Notes
Recent GDP slowdown in the July-September quarter has prompted Economy Minister Kiuchi to distance himself from immediate rate-hike calls, leaving timing to the BoJ. Persistent yen weakness near 160 continues to stoke imported inflation risks and intervention alerts from Tokyo. Equity markets remain vulnerable as the Nikkei hovers near bear-market territory after the AI rally cooled.
Bond markets show limited movement, with the curve holding a steep profile consistent with gradual policy normalisation. Broader sentiment hinges on whether upcoming inflation data confirm the BoJ’s view that price stability is within reach.