Japan Macro Daily(Beta Mode)
Yen Presses 160 as Ueda Signals December Hike
Market Snapshot
| Asset | Level | Change |
|---|---|---|
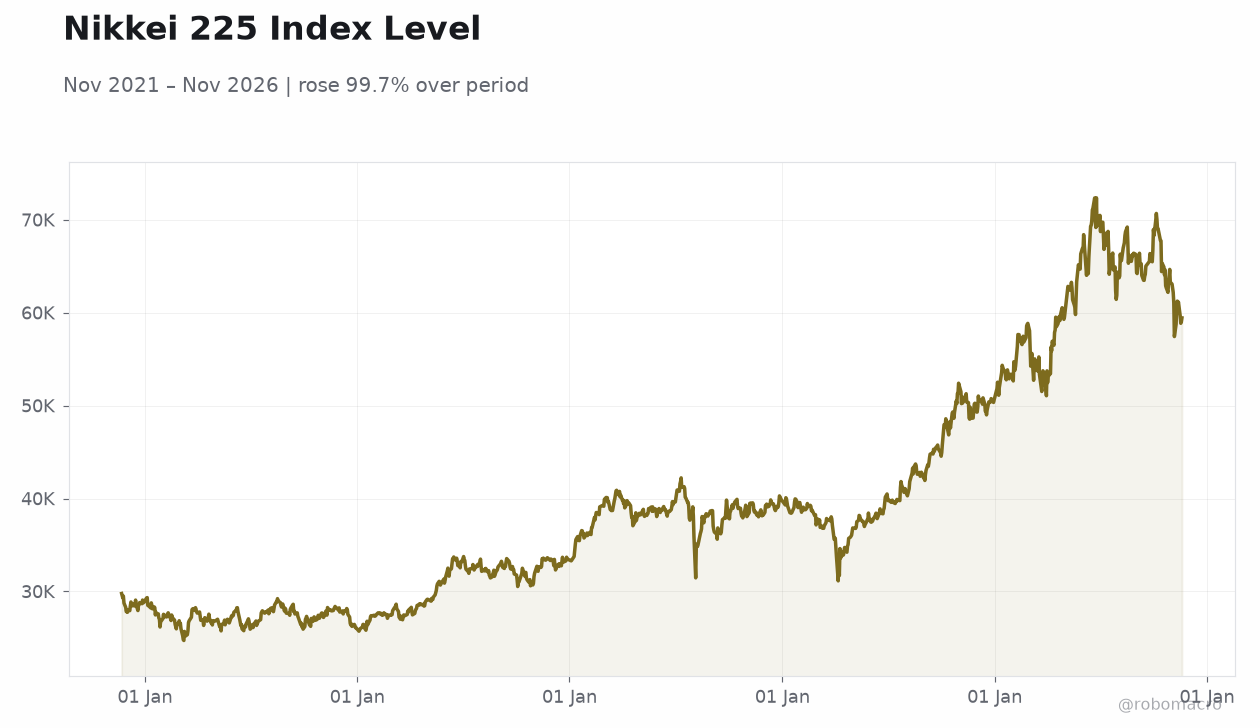
| Nikkei 225 | 59,024.28 | +0.28% |
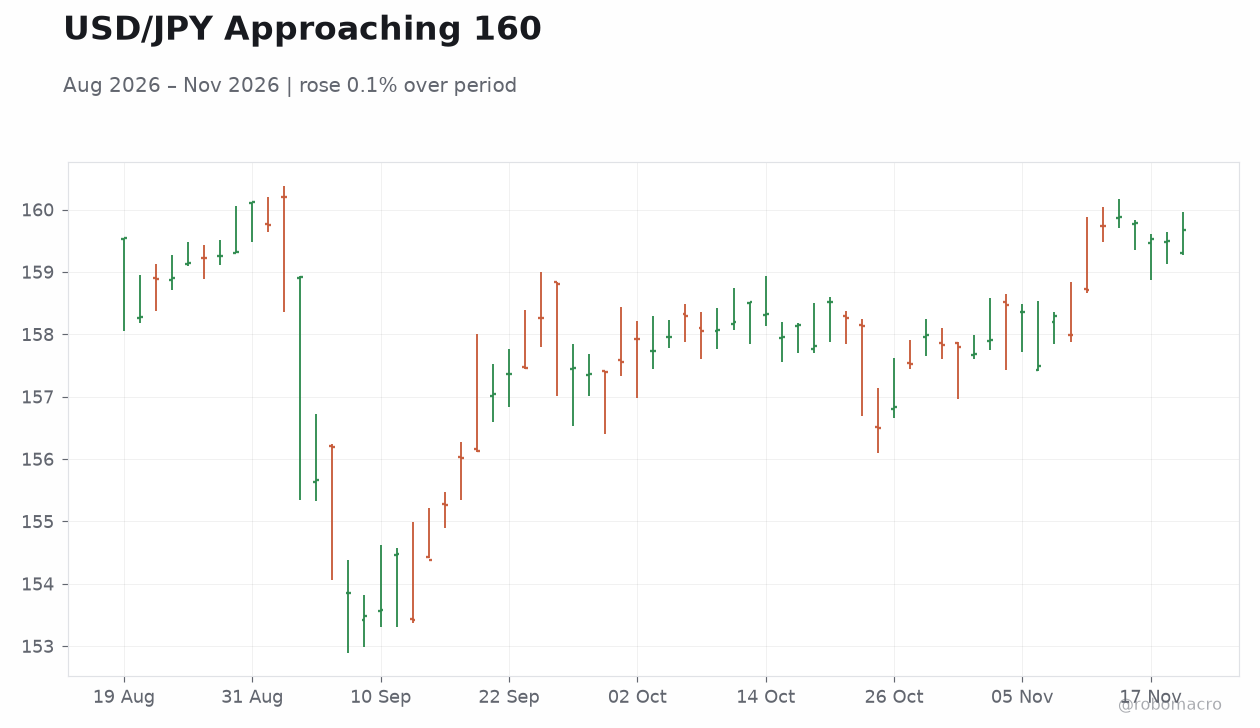
| USD/JPY | 159.66 | +0.10% |
| EUR/JPY | 175.24 | -0.06% |
| GBP/JPY | 209.11 | -0.71% |
| Gold | 3,667.00 | -2.00% |
| Brent Crude | 90.06 | -2.06% |
| Bitcoin | 61,957.46 | -1.63% |
| Japan 2Y Govt Yield | 1.87% | -1 bp |
| Japan 10Y Govt Yield | 2.92% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | -536.6m | -956,000m | -476.5m |
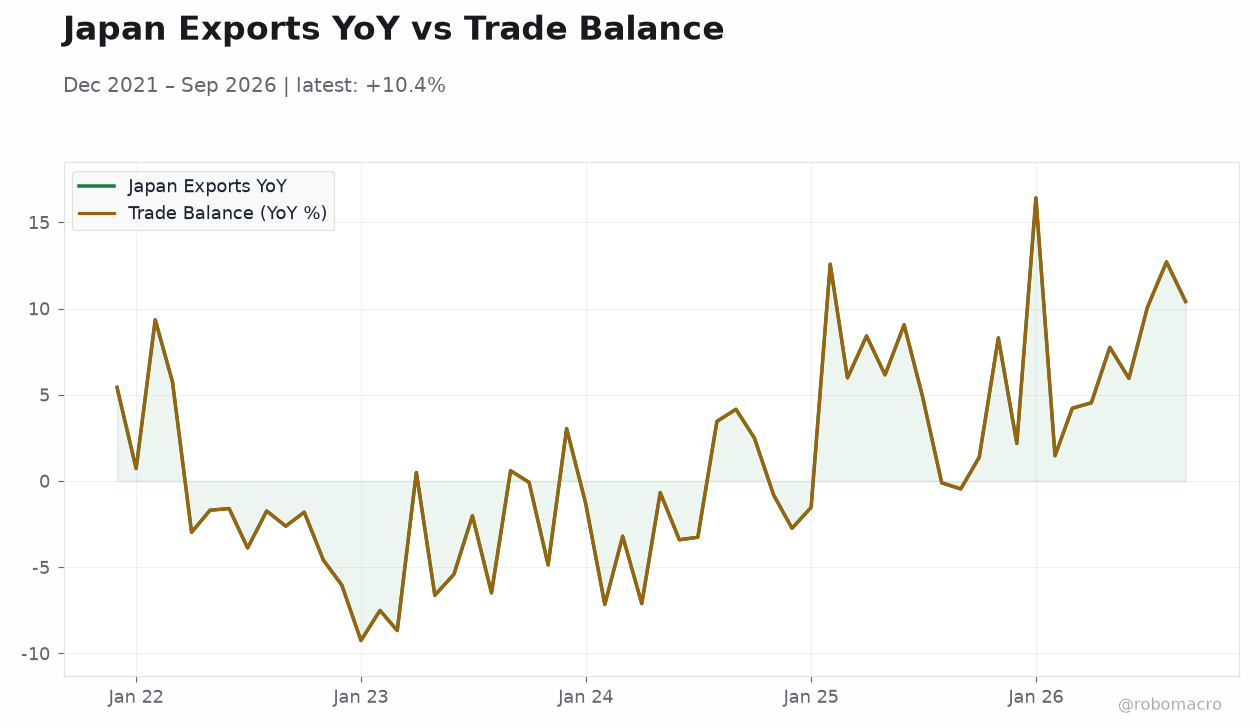
| Exports Year-over-Year | 16.70 | 20 | 20.50 |
| Machinery Orders Month-over-Month | 5.20 | -0.50 | -0.30 |
| Machinery Orders Year-over-Year | 18.60 | 13.70 | 13.40 |
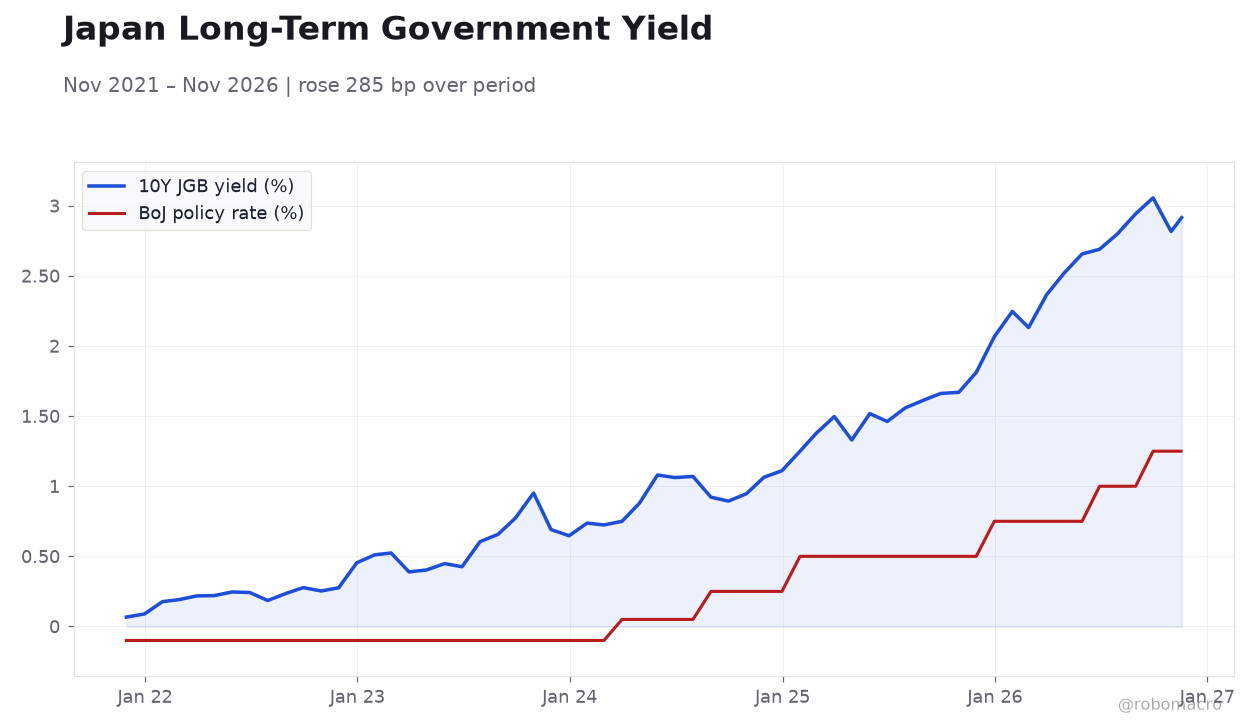
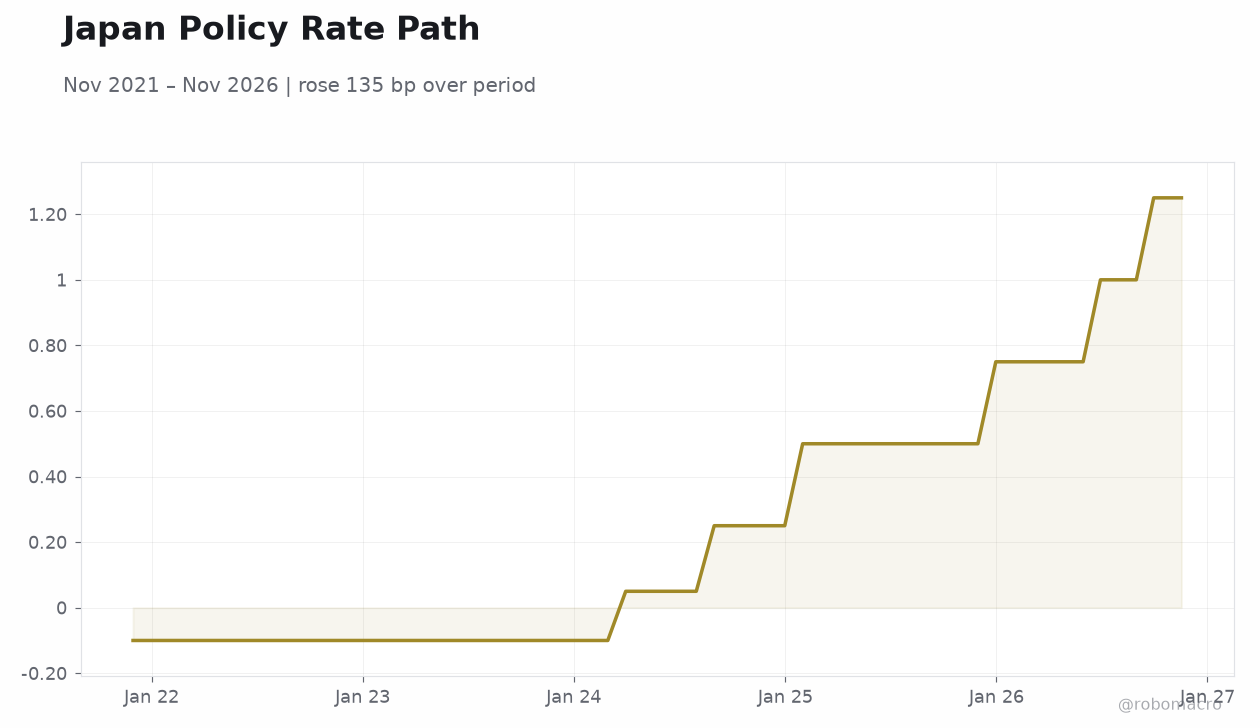 Japan Policy Rate Path | Type: macro_line | BoJ policy rate (%): 1.25 (2026-11-17) | Range: -0.1–1.25 | Trend(5pt): -0.1,-0.1,0.05,0.5,1.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Inflation Rate Year-over-Year | 2.10 | - | 18:30 |
| Core Inflation Rate Year-over-Year | 2.10 | 2.30 | 18:30 |
- BoJ Governor Ueda reaffirms plans to keep raising rates, keeping a December hike live and lifting JGB front-end support.
- October core inflation due today with consensus at 2.3% versus 2.1% prior, a key input for the December 18 decision.
- Yen pinned just below 160.00 despite hawkish BoJ signals, with MoF verbal warnings raising intervention risk.
Yesterday's Recap
Japan's October trade data showed exports rising 20.5% y/y, beating consensus of 20% and accelerating from 16.7% prior, while the trade balance printed at -¥476.5mn on the calendar series. October machinery orders fell 0.3% m/m, better than the -0.5% consensus but a sharp deceleration from 5.2% prior, with the y/y series at 13.4% versus 13.7% expected. Markets were quiet: the Nikkei 225 added 0.28% to 59,024.28, the 10-year JGB yield held at 2.92% and the 2-year eased 1 bp to 1.87%, a modest front-end bid consistent with hawkish BoJ rhetoric.
USD/JPY edged up 0.10% to 159.66, still capped below the 160.00 line, while GBP/JPY fell 0.71% to 209.11 as sterling softened. Commodities retreated, with Brent down 2.06% to $90.06 and gold off 2.00% at $3,667, while bitcoin slipped 1.63%.
The Day Ahead
The focus is tonight's October inflation release at 18:30 ET, with core CPI consensus at 2.3% y/y versus 2.1% prior and headline prior at 2.1%. A print at or above consensus would reinforce the case for a December 18 hike and could finally give the yen a foothold below 160. A softer core reading would undercut Ueda's normalization messaging and likely push USD/JPY toward the intervention zone.
No other Japanese releases are scheduled for tomorrow, so positioning into the CPI print and the subsequent MoF/BoJ reaction function will dominate the session. Liquidity may thin ahead of the weekend, amplifying moves on any surprise.
Other Economic Notes
The export strength is flattered by AI-related demand and semiconductor pricing, which Ueda himself flagged as both an export tailwind and an inflation driver. Machinery orders decelerating to -0.3% m/m suggests capex momentum is cooling after a strong prior quarter, a cautionary signal for domestic demand. The trade balance remains in deficit, leaving Japan exposed to energy prices; Ueda warned that rising oil and a weak yen could hit the economy.
With the policy rate at 1.25% after the September hike, real rates remain deeply negative against 2.1% CPI, keeping financial conditions accommodative by the BoJ's own framing.