Korea Macro Daily(Beta Mode)
KOSPI Slides on AI Worries as Won Strengthens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| KOSPI | 6,684.37 | -3.26% |
| KOSDAQ | 806.79 | -1.69% |
| USD/KRW | 1,363.60 | +1.41% |
| Samsung | 248,500.00 | -0.20% |
| SK Hynix | 1,690,000.00 | -0.41% |
| Brent Crude | 108.48 | +2.65% |
| Gold | 4,333.40 | -0.43% |
| Bitcoin | 75,677.99 | -3.18% |
| Korea 3Y Govt Yield | 4.03% | +2 bp |
| Korea 10Y Govt Yield | 4.54% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
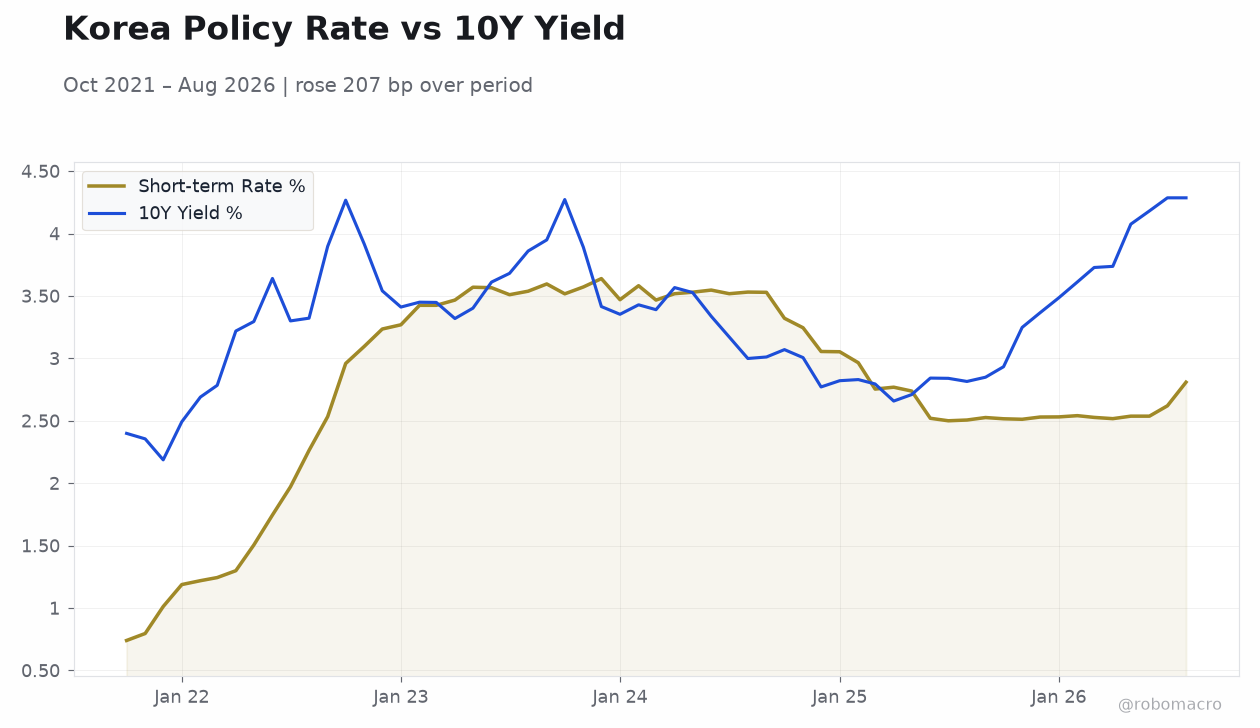 Korea Policy Rate vs 10Y Yield | Type: macro_line | Short-term Rate %: 2.809 (2026-08-01) | Range: 0.74–3.639 | Trend(6pt): 0.74,3.235,3.582,2.769,2.537,2.809 | 10Y Yield %: 4.286 (2026-08-01) | Range: 2.187–4.286 | Trend(6pt): 2.399,3.541,3.429,2.658,4.181,4.286
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
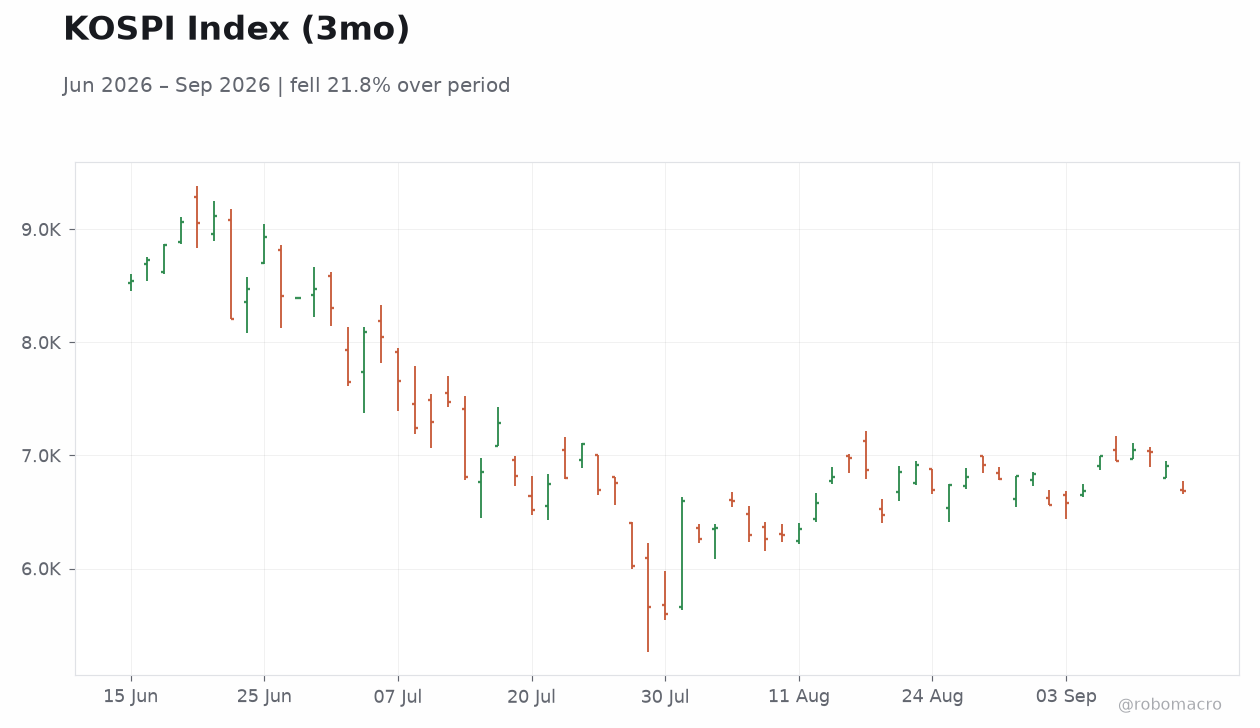
- KOSPI fell 3.26% to 6,684.37 while KOSDAQ dropped 1.69% to 806.79 on AI concerns.
- USD/KRW rose 1.41% to 1,363.60, strengthening the won and pressuring export prices.
- BoK minutes highlighted a split August rate decision and caution on further hikes.
Yesterday's Recap
South Korean equities declined sharply on September 14 as AI-related concerns weighed on sentiment, with the KOSPI closing down 3.26% at 6,684.37 and the KOSDAQ falling 1.69% to 806.79. Samsung ended at 248,500, off 0.20%, while SK Hynix slipped 0.41% to 1,690,000. The won strengthened notably, lifting USD/KRW by 1.41% to 1,363.60.
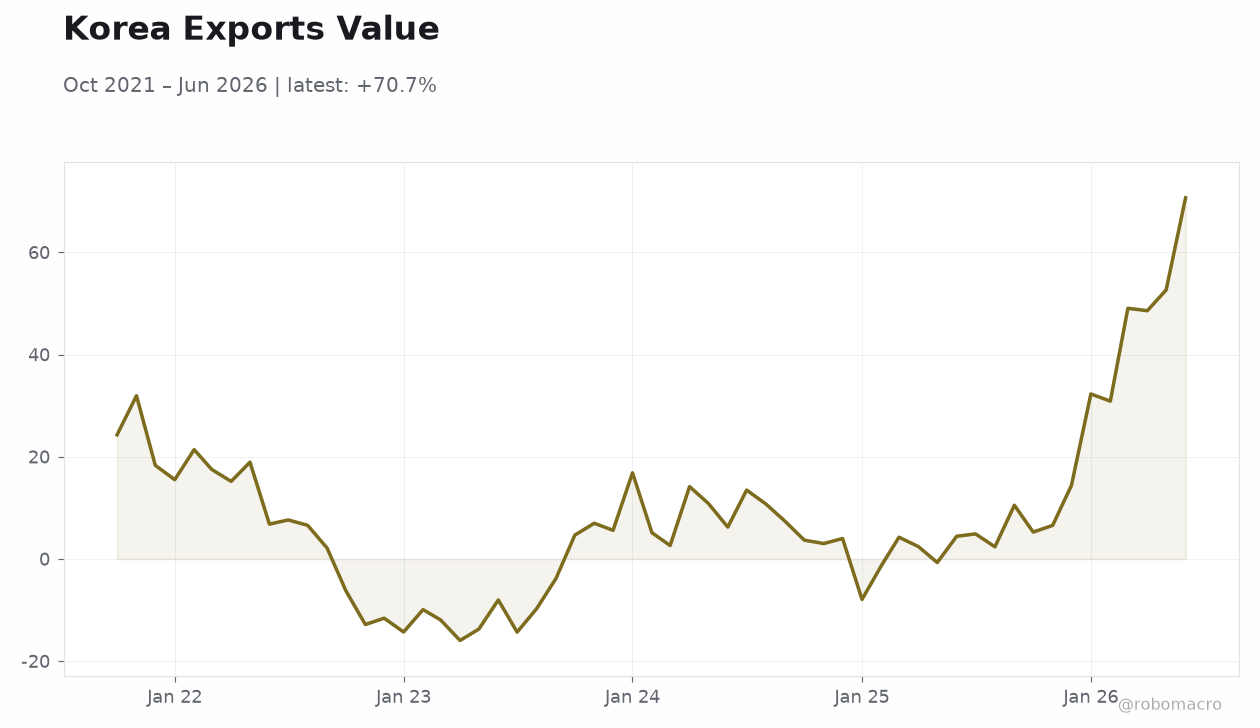
August export prices fell 3.7% on the currency move, prompting Korean firms to redraw business plans and revise earnings forecasts. No economic data releases occurred. Korea’s 3-year government yield rose 2 bp to 4.03% while the 10-year yield held steady at 4.54%.
Brent crude gained 2.65% to 108.48, gold eased 0.43% to 4,333.40, and Bitcoin dropped 3.18% to 75,677.99. Money supply expanded by 12.7 trillion won in July, supported by semiconductor-driven corporate inflows. The financial sector supplied 272 trillion won in productive finance.
The Day Ahead
No major data releases or Bank of Korea events are scheduled for September 15. Markets will continue to digest the stronger won’s impact on export competitiveness and corporate margins. Attention remains on how firms adjust supply chains and pricing amid the currency shift.
Rising oil prices may influence local sentiment. Investors will monitor any follow-up commentary from officials on inflation and recovery priorities. The absence of fresh indicators leaves focus on ongoing won dynamics and semiconductor sector performance.
Other Economic Notes
Korea’s financial sector extended 272 trillion won in productive finance, channeling liquidity toward key industries. The finance-minister nominee emphasized measures to contain inflation while supporting economic recovery. Housing-related political pressures on President Lee add domestic policy complexity.
Export price weakness from the stronger won underscores risks to the trade-driven growth model. Corporate liquidity inflows tied to semiconductors highlight sector concentration in overall money supply trends.