Korea Macro Daily(Beta Mode)
Chip Gains Lift KOSPI as Won Firms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| KOSPI | 7,080.92 | +0.90% |
| KOSDAQ | 844.48 | +1.21% |
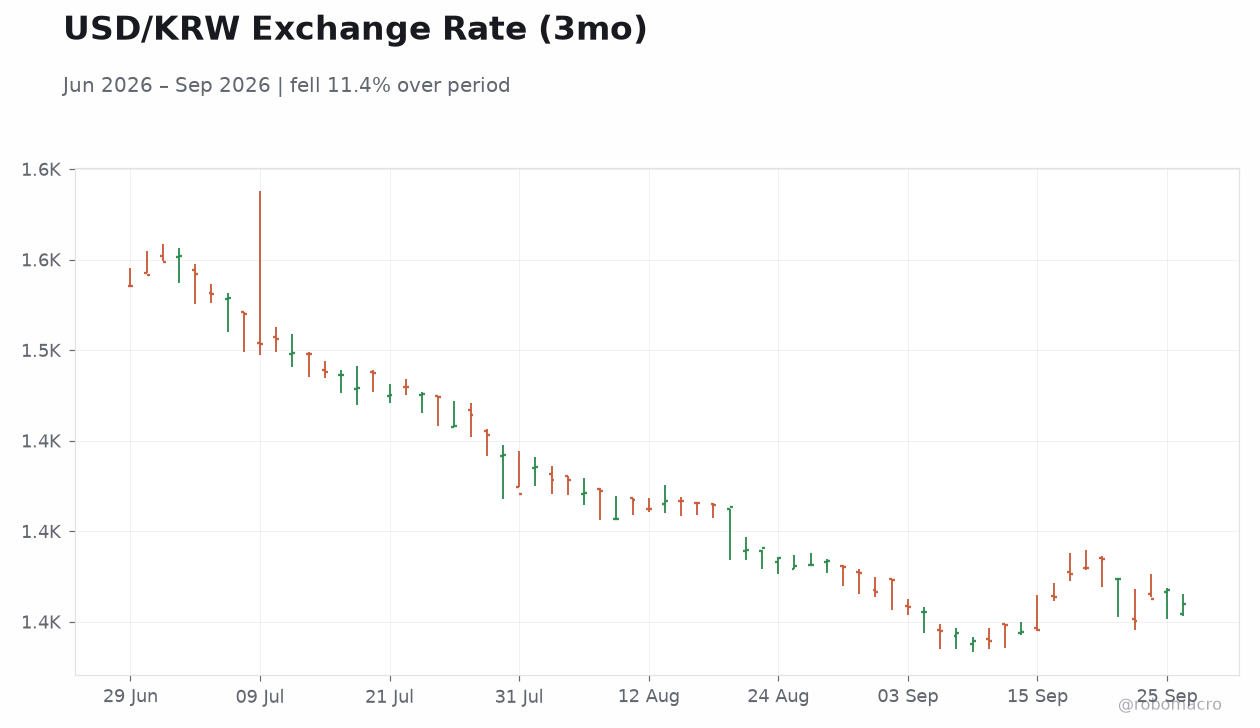
| USD/KRW | 1,359.68 | -0.56% |
| Samsung | 285,500.00 | +3.25% |
| SK Hynix | 1,862,000.00 | +1.20% |
| Brent Crude | 98.55 | -5.53% |
| Gold | 4,147.60 | -4.02% |
| Bitcoin | 83,588.52 | -1.03% |
| Korea 3Y Govt Yield | 4.01% | -3 bp |
| Korea 10Y Govt Yield | 4.39% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Business Confidence Index | 81 | - | - |
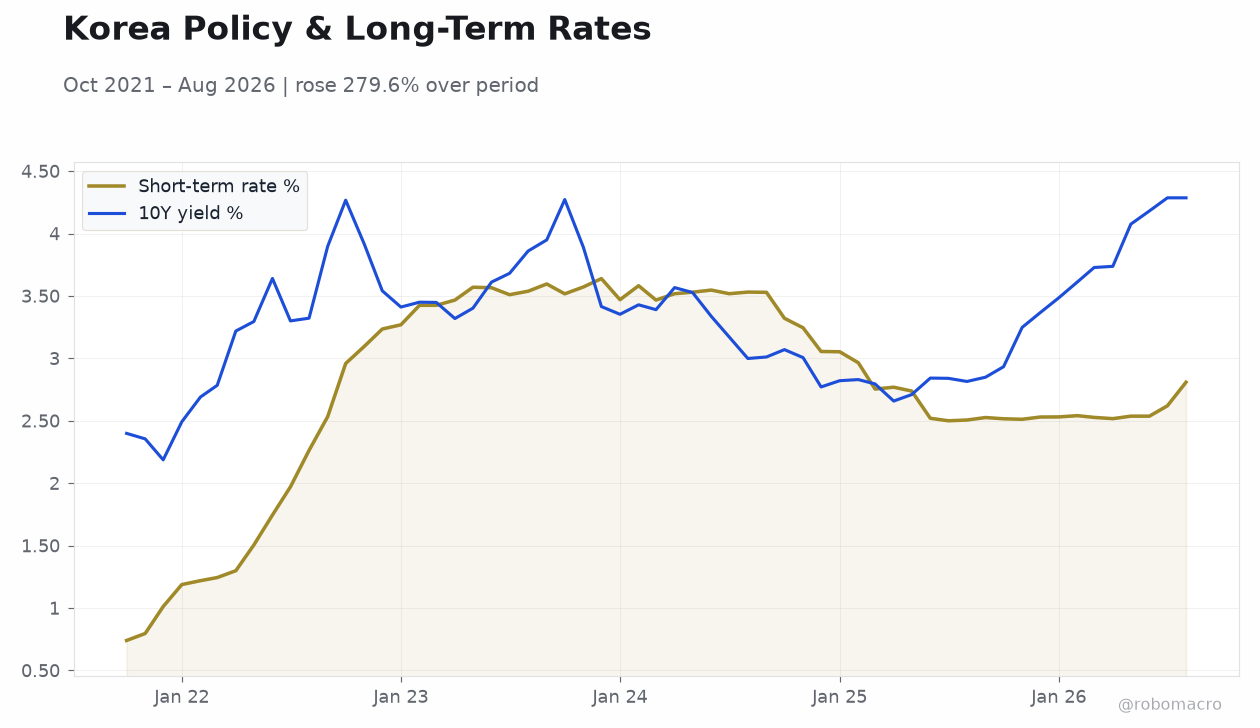 Korea Policy & Long-Term Rates | Type: macro_line | Short-term rate %: 2.809 (2026-08-01) | Range: 0.74–3.639 | Trend(6pt): 0.74,3.235,3.582,2.769,2.537,2.809 | 10Y yield %: 4.286 (2026-08-01) | Range: 2.187–4.286 | Trend(6pt): 2.399,3.541,3.429,2.658,4.181,4.286
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-30) | |||
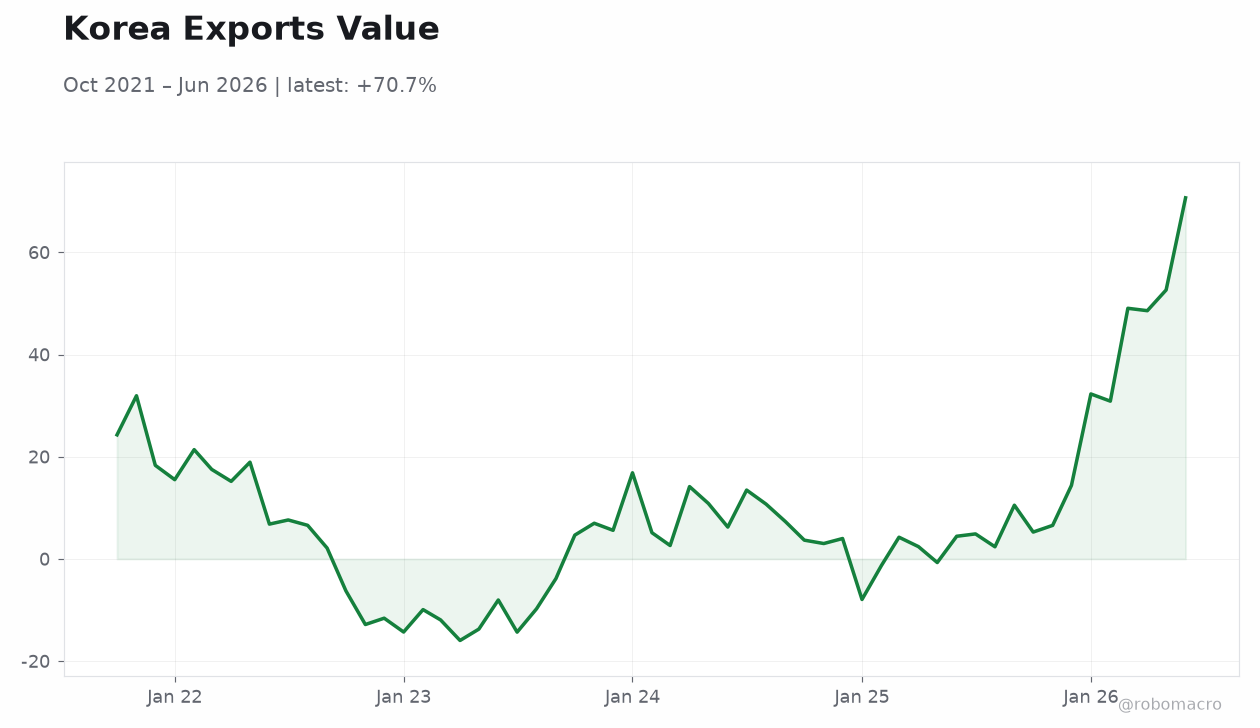
| Exports Year-over-Year | 68.70 | 60.60 | 16:00 |
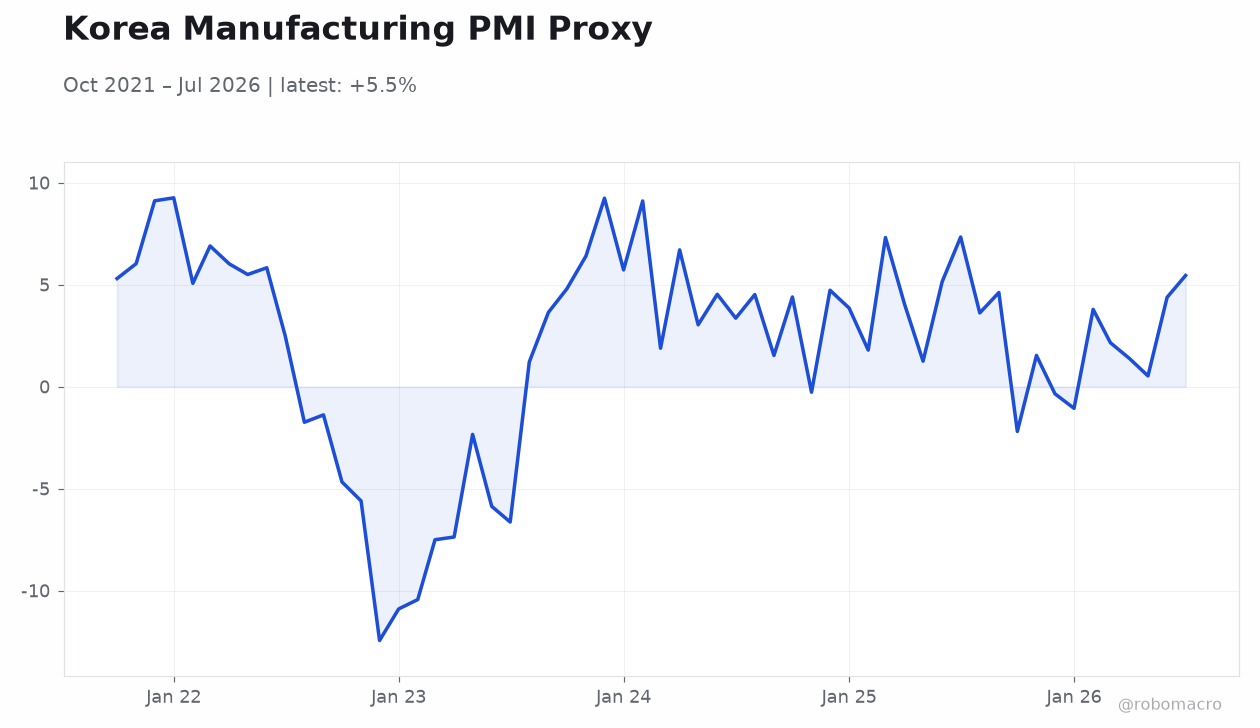
| S&P Global Manufacturing PMI Index | 52.30 | - | 16:30 |
| Thursday (2026-10-01) | |||
| Inflation Rate Year-over-Year | 3.10 | - | 15:00 |
- KOSPI advanced 0.90% to 7,080.92 while Samsung rose 3.25% on semiconductor momentum.
- USD/KRW declined 0.56% to 1,359.68 as Korea 10Y yield eased 7 bp to 4.39%.
- Exports YoY and inflation prints due this week will test export resilience and price pressures.
Yesterday's Recap
Equity markets closed higher on 27 September with KOSPI at 7,080.92 and KOSDAQ at 844.48, supported by Samsung at 285,500 and SK Hynix at 1,862,000. The Business Confidence Index release was absent, leaving no fresh domestic data prints. The won strengthened to 1,359.68 against the dollar while Korea 3Y and 10Y government yields fell 3 bp and 7 bp to 4.01% and 4.39%.
Brent crude dropped 5.53% to 98.55 and gold fell 4.02% to 4,147.60, reflecting softer commodity sentiment. Overall market moves aligned with steady external demand for Korean technology names despite global uncertainty signals. BOK commentary noted heightened external risks yet described domestic fundamentals as sound, supporting the firmer won and lower yields.
The Day Ahead
Exports Year-over-Year data are scheduled for 30 September with consensus at 60.6 versus prior 68.7, followed by S&P Global Manufacturing PMI at 16:30. Inflation Rate Year-over-Year prints on 1 October against the prior 3.1 reading. These releases will shape views on trade momentum and price stability ahead of the next MPC meeting.
Markets will monitor USD/KRW and KTB yields for any repricing of external demand risks. Equity sentiment, particularly in semiconductors, remains sensitive to the export outcome. The absence of data today keeps focus on the upcoming prints and their potential to influence policy expectations.
Other Economic Notes
Reports indicate a potential 50 trillion won tax windfall from the chip boom, boosting fiscal revenue above forecasts. Housing expectations and mortgage demand have shown limited response to prior rate adjustments, keeping property-related credit growth elevated. South Korea is advancing won internationalization through 24-hour FX trading and RFI access to deepen currency usage.
Property finance exposure has reached 4,300 trillion won, underscoring ongoing balance-sheet linkages between banks and real estate. These dynamics support domestic liquidity while highlighting concentration risks in the housing sector. The combination sustains resilience in fiscal and external accounts.