Korea Macro Daily(Beta Mode)
Business Confidence Falls, Yields Jump on CPI Worries
Market Snapshot
| Asset | Level | Change |
|---|---|---|
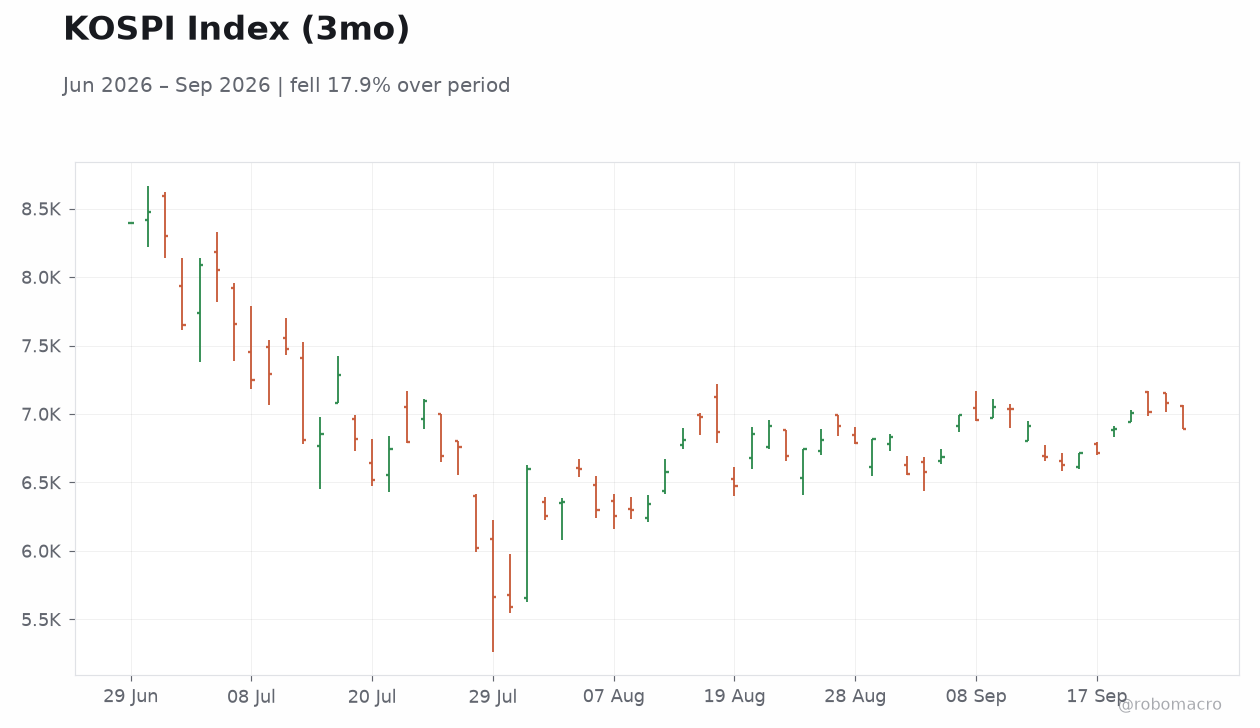
| KOSPI | 6,889.74 | -2.70% |
| KOSDAQ | 846.58 | +0.25% |
| USD/KRW | 1,352.36 | -0.16% |
| Samsung | 272,500.00 | +0.93% |
| SK Hynix | 1,765,000.00 | -0.17% |
| Brent Crude | 95.70 | -9.10% |
| Gold | 4,214.00 | +1.09% |
| Bitcoin | 83,512.97 | +0.01% |
| Korea 3Y Govt Yield | 4.12% | +11 bp |
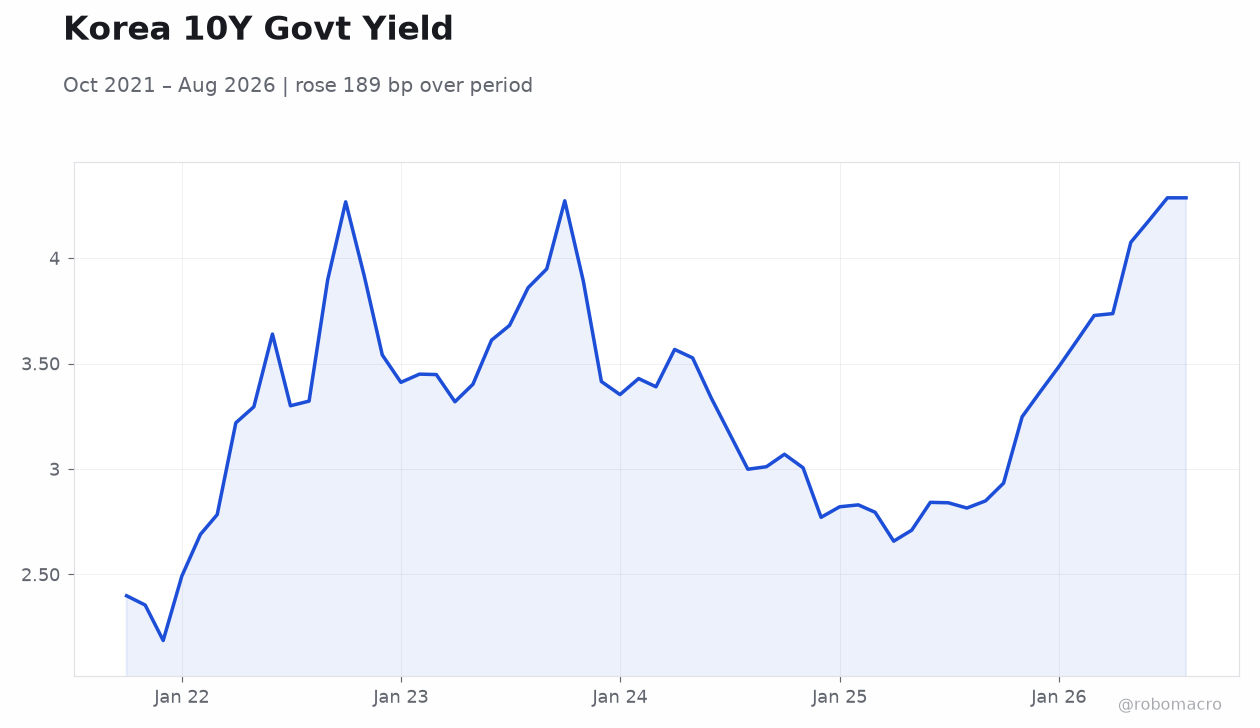
| Korea 10Y Govt Yield | 4.39% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Business Confidence Index | 81 | - | 79 |
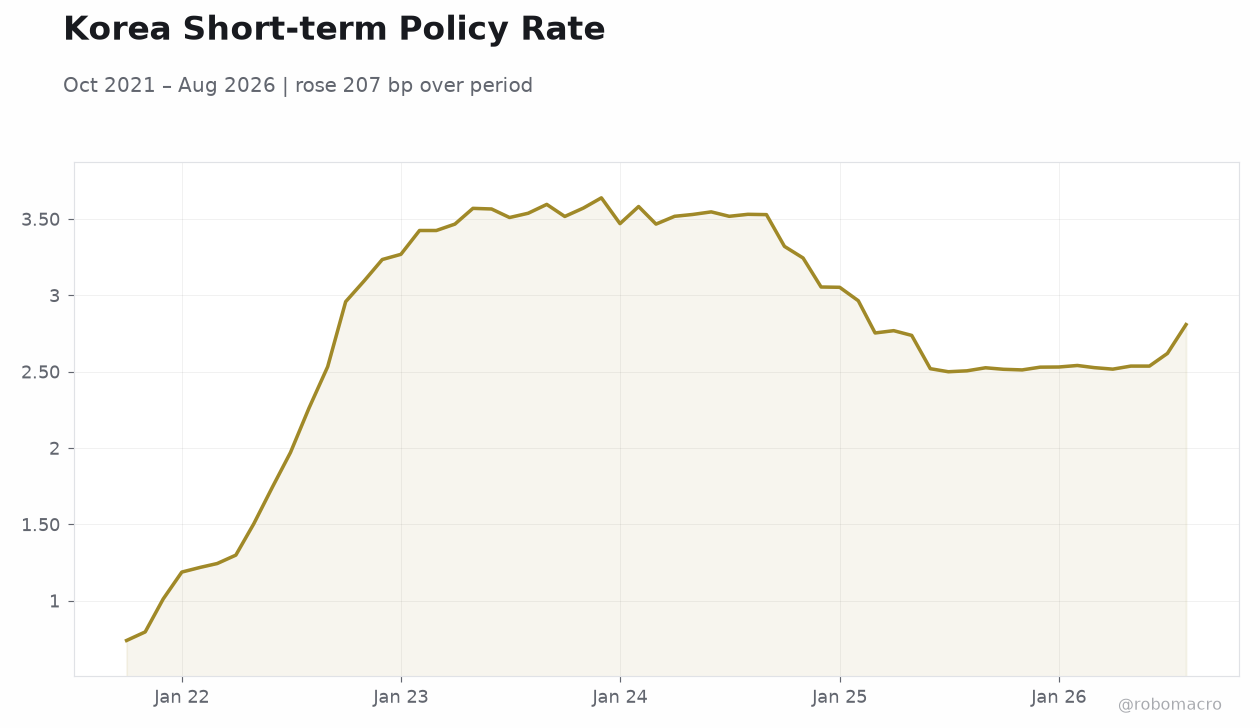 Korea Short-term Policy Rate | Type: macro_line | Rate %: 2.809 (2026-08-01) | Range: 0.74–3.639 | Trend(6pt): 0.74,3.235,3.582,2.769,2.537,2.809
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-30) | |||
| Exports Year-over-Year | 68.70 | 60.60 | 16:00 |
| S&P Global Manufacturing PMI Index | 52.30 | - | 16:30 |
| Thursday (2026-10-01) | |||
| Inflation Rate Year-over-Year | 3.10 | - | 15:00 |
- Business Confidence Index dropped to 79 in September as costs rose.
- KOSPI fell 2.70% while the won strengthened on dollar selling.
- Korea 3-year yield rose 11 bp to 4.12%, highest since November 2022.
Yesterday's Recap
South Korea’s Business Confidence Index declined to 79 from 81, reflecting weaker corporate sentiment amid higher input costs. KOSPI closed at 6,889.74, down 2.70%, while KOSDAQ edged up 0.25% to 846.58. Samsung rose 0.93% to 272,500 but SK Hynix slipped 0.17%.
The won strengthened 0.16% to 1,352.36 against the dollar on export optimism and dollar selling. Korea’s 3-year government yield climbed 11 bp to 4.12%, the highest level since November 2022, as the bond market reopened after holidays and joined a global selloff. The 10-year yield eased 7 bp to 4.39%.
Brent crude fell sharply 9.10% to 95.70 while gold advanced 1.09%. The Bank of Korea noted that global financial-market uncertainty has heightened while South Korea’s fundamentals remain sound.
The Day Ahead
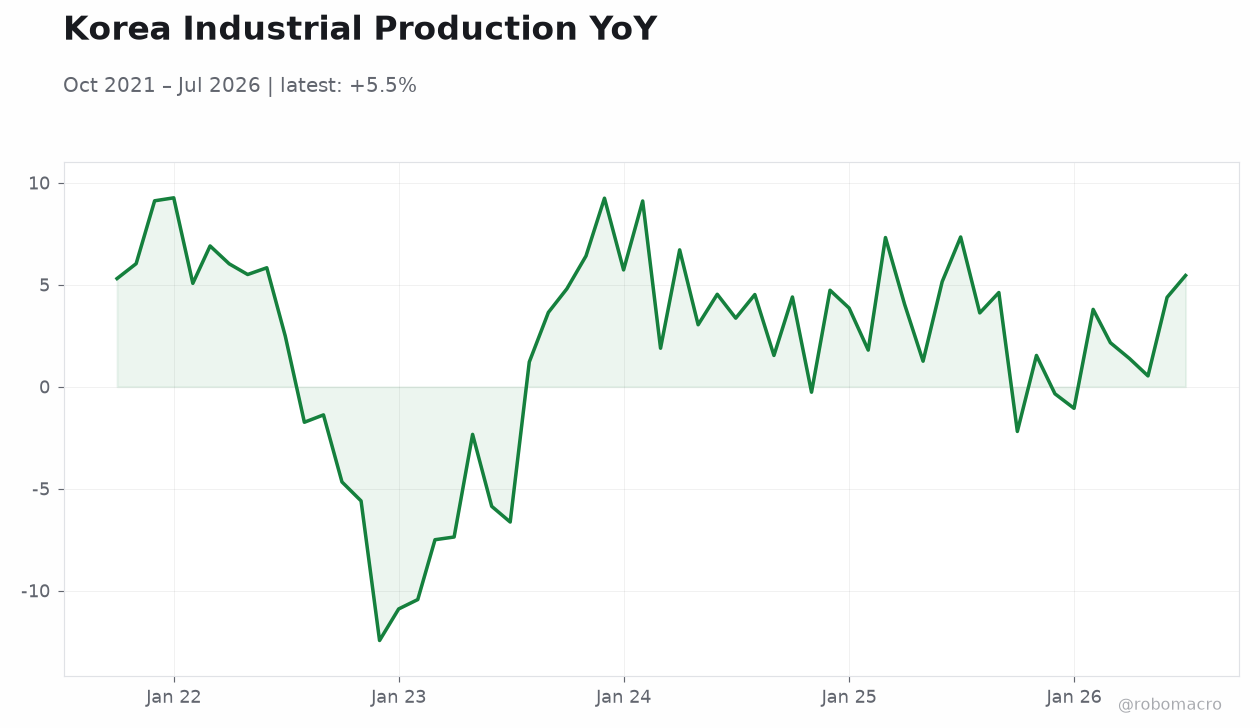
Exports year-over-year data are due September 30 with consensus at 60.6 after 68.7 previously, providing a direct read on semiconductor and export momentum. S&P Global Manufacturing PMI follows the same day. October 1 brings the inflation rate year-over-year print after 3.1% in the prior month.
Markets will watch whether softening exports and persistent price pressures shift BoK rate expectations. The releases are expected to influence USD/KRW, Korea Treasury bond yields, and equity flows into Samsung and SK Hynix. Any surprise in inflation could reinforce the recent 3-year yield spike.
Other Economic Notes
The Financial Services Commission plans to include the Bank of Korea in an interagency body shaping won stablecoin legislation, signaling closer coordination on digital-asset rules. Rate hikes have yet to dampen housing price expectations or mortgage demand, keeping financial-stability concerns elevated. Seoul equities opened lower on inflation worries even as the won held firm on export prospects.
Korea Development Bank continues to extend large fossil-fuel loans without calculating associated carbon emissions. These themes underscore the tension between growth support and price-stability objectives.
Global Macro News
Global bond markets sold off after the holiday break, pushing Korea’s 3-year yield higher in tandem with overseas peers. ↓ p.2