Korea Macro Daily(Beta Mode)
KOSPI Reclaims 7,000 as Won Strengthens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| KOSPI | 7,003.74 | +0.46% |
| KOSDAQ | 893.29 | -0.11% |
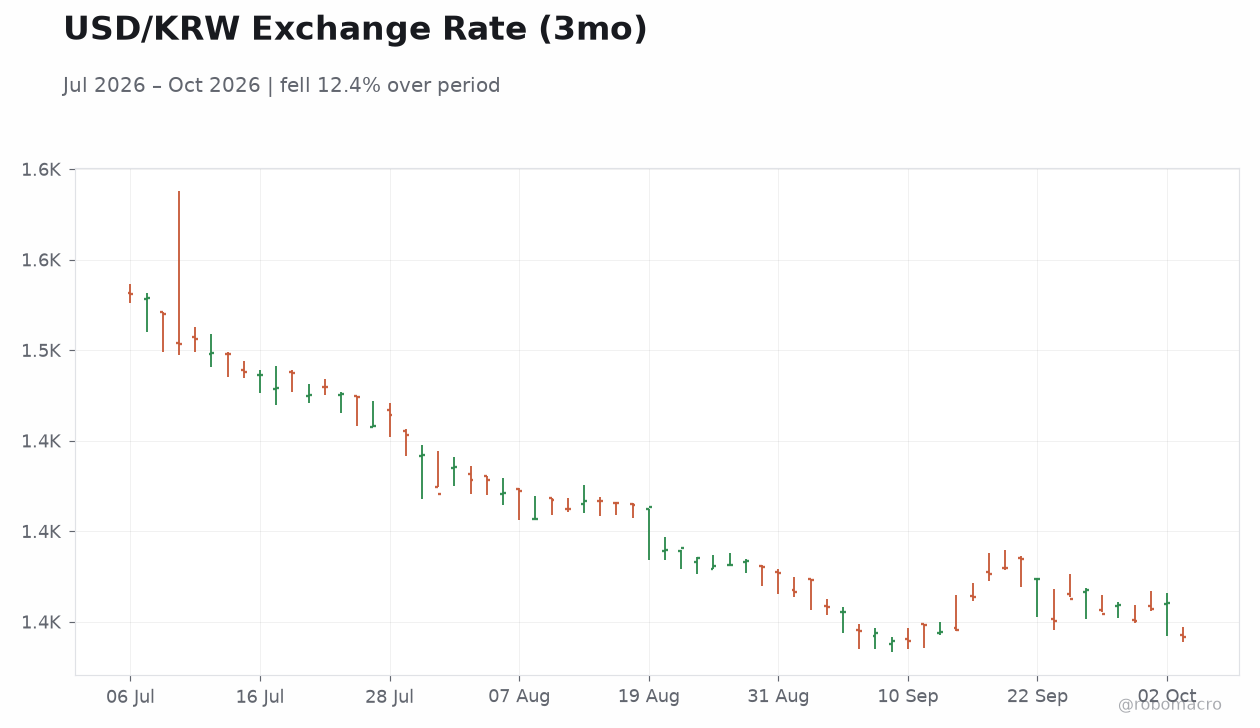
| USD/KRW | 1,341.59 | -1.40% |
| Samsung | 276,000.00 | +0.00% |
| SK Hynix | 1,841,000.00 | +0.44% |
| Brent Crude | 100.21 | -2.00% |
| Gold | 4,169.10 | +0.16% |
| Bitcoin | 85,770.45 | -0.82% |
| Korea 3Y Govt Yield | 4.01% | 0 bp |
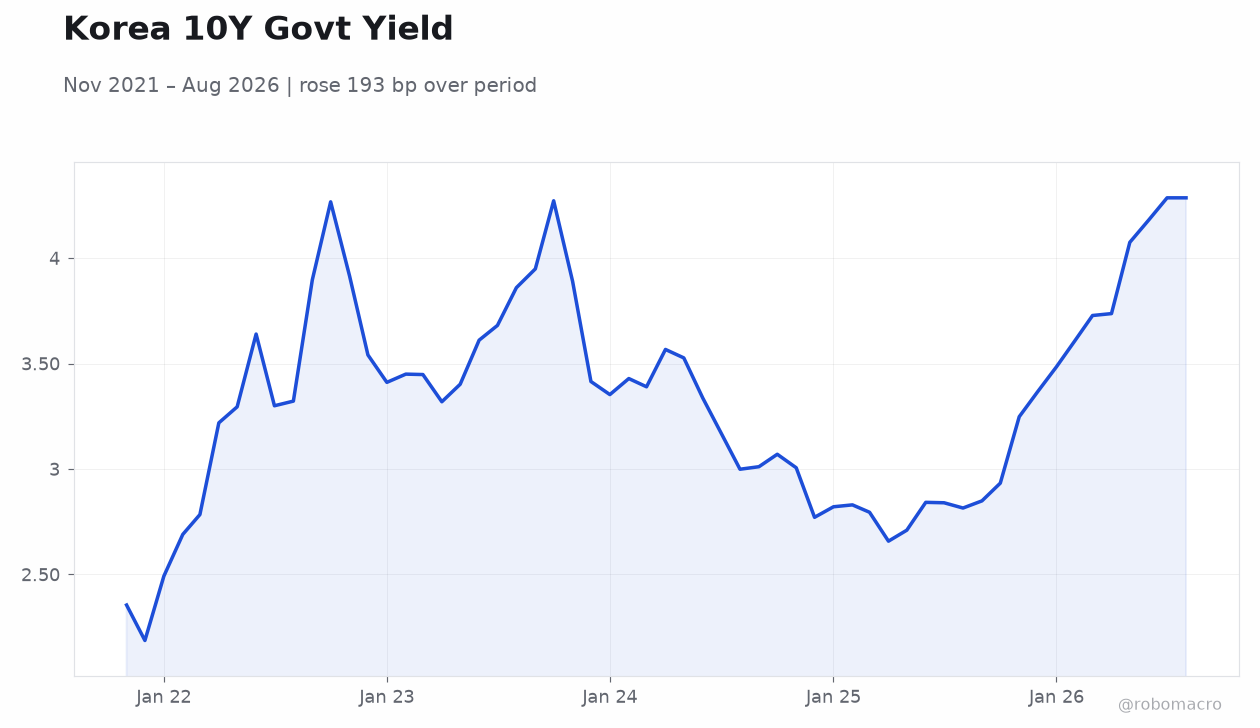
| Korea 10Y Govt Yield | 4.44% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
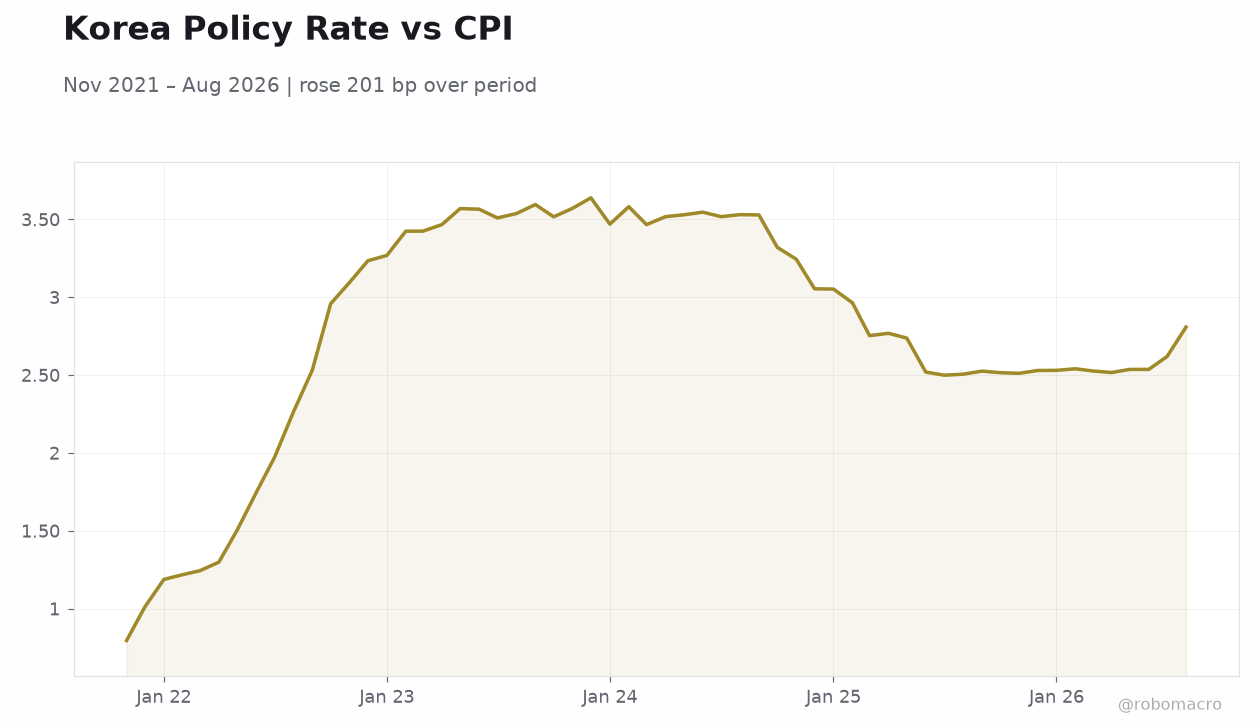 Korea Policy Rate vs CPI | Type: macro_line | Policy Rate %: 2.809 (2026-08-01) | Range: 0.796–3.639 | Trend(6pt): 0.796,3.269,3.467,2.738,2.62,2.809
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- September CPI slowed to 2.9% with underlying pressures building, keeping BoK on hold.
- KOSPI rose 0.46% to 7,003.74 on tech buying while USD/KRW fell 1.40% to 1,341.59.
- M&A volume hit 62 trillion won in nine months, exceeding full-year 2025 total.
Yesterday's Recap
Seoul equities closed higher on bargain hunting in technology stocks, with KOSPI advancing 0.46% to 7,003.74 and reclaiming the 7,000 level. KOSDAQ slipped 0.11% to 893.29 while Samsung ended flat at 276,000 and SK Hynix gained 0.44% to 1,841,000. The won strengthened sharply as USD/KRW dropped 1.40% to 1,341.59.
September CPI printed at 2.9%, returning to that level, and the Bank of Korea stated that underlying price pressures are building with October inflation expected to stay around 3%. Korea 3-year government bond yields held at 4.01% while the 10-year yield rose 3 bp to 4.44%. No other data releases occurred.
Strong export performance continued to support the currency according to Commerzbank analysis. The absence of fresh domestic data left markets focused on the inflation print and its implications for the policy outlook.
The Day Ahead
No economic releases, Bank of Korea speeches or MPC events are scheduled for today or tomorrow. Markets will monitor external drivers including US Treasury yields and any follow-through from the September inflation print. Focus remains on won dynamics and semiconductor sector performance.
Investors will watch for any corporate earnings updates or global risk sentiment shifts that could influence export-oriented equities. The absence of domestic catalysts leaves KOSPI and KOSDAQ sensitive to overseas developments. Attention may also turn to any updates on mortgage lending trends or M&A activity that could affect sentiment toward financial and corporate sectors.
Other Economic Notes
South Korea’s M&A market reached 62 trillion won in the first nine months, already surpassing the full-year 2025 total and signaling robust corporate activity. The share of high-rate mortgages at the five largest banks has risen sharply over eight months, raising household debt concerns. Bank-led won stablecoins could limit innovation according to regulatory commentary.
Fifty-two minors now hold more than 1 billion won each in bank deposits, highlighting wealth concentration. These developments underscore ongoing structural shifts in the domestic financial landscape amid a stronger currency environment.