RoboMacro ResearchAlso todaySee the Equities Daily

Korea Macro Daily(Beta Mode)

October 20, 2026 robomacro.com

Won Surges to Two-Year High as Chips Slump

KOSPI5,768.01+1.76%
KOSDAQ808.89+1.78%
USD/KRW1,326.19-0.54%
Samsung211,500.00-2.98%

Market Snapshot

AssetLevelChange
KOSPI5,768.01+1.76%
KOSDAQ808.89+1.78%
USD/KRW1,326.19-0.54%
Samsung211,500.00-2.98%
SK Hynix1,223,000.00-4.23%
Brent Crude109.12-0.39%
Gold4,142.50-0.42%
Bitcoin82,793.45+1.15%
Korea 3Y Govt Yield3.88%+3 bp
Korea 10Y Govt Yield4.21%+3 bp

Prior Economic Events

Data Prior Cons Actual
No events available
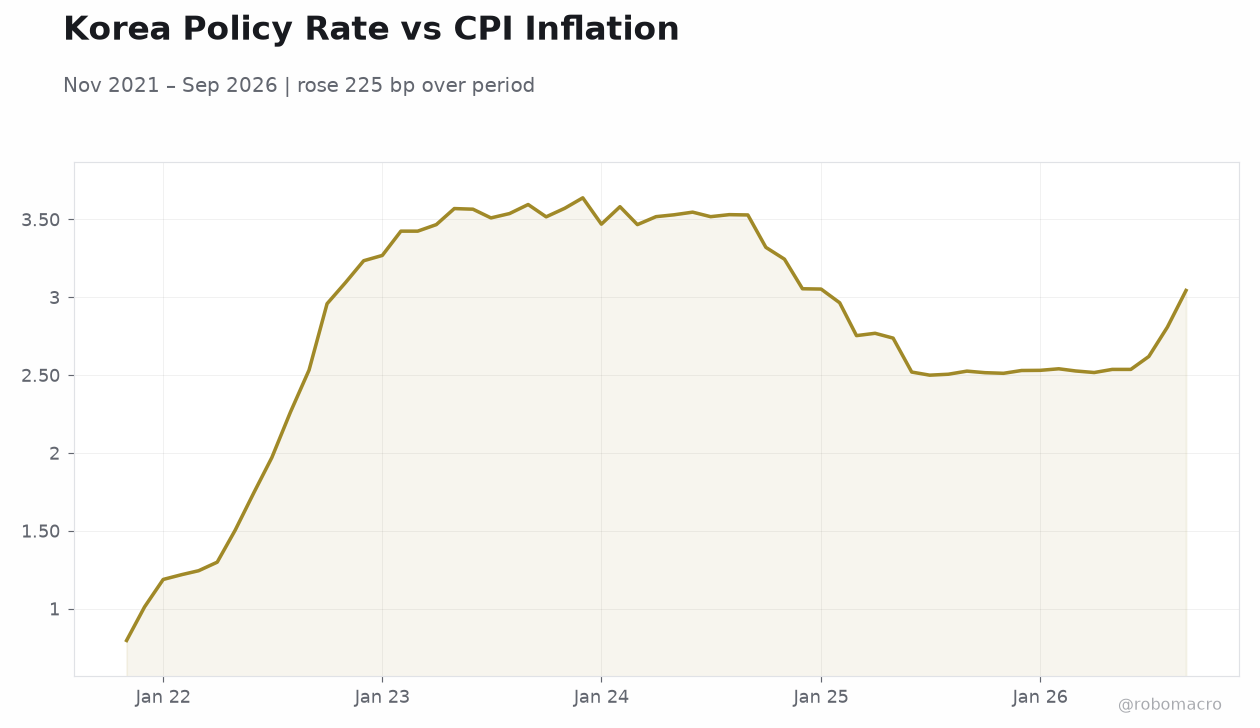
Korea Policy Rate vs CPI InflationKorea Policy Rate vs CPI Inflation | Type: macro_line | Short-term rate (%): 3.044 (2026-09-01) | Range: 0.796–3.639 | Trend(6pt): 0.796,3.269,3.467,2.738,2.62,3.044

Today's Economic Events

Data Prior Cons Time
No events available
  • Won hits fresh two-year high against dollar; USD/KRW at 1,326.19 (-0.54%) even as KOSPI gains 1.76% to 5,768.01
  • Samsung (-2.98%) and SK Hynix (-4.23%) slide despite index strength; battery and auto names offset chip losses
  • BoK signals rate-hike pause with hawkish forward guidance; 3Y and 10Y yields each add 3 bp to 3.88% and 4.21%

Yesterday's Recap

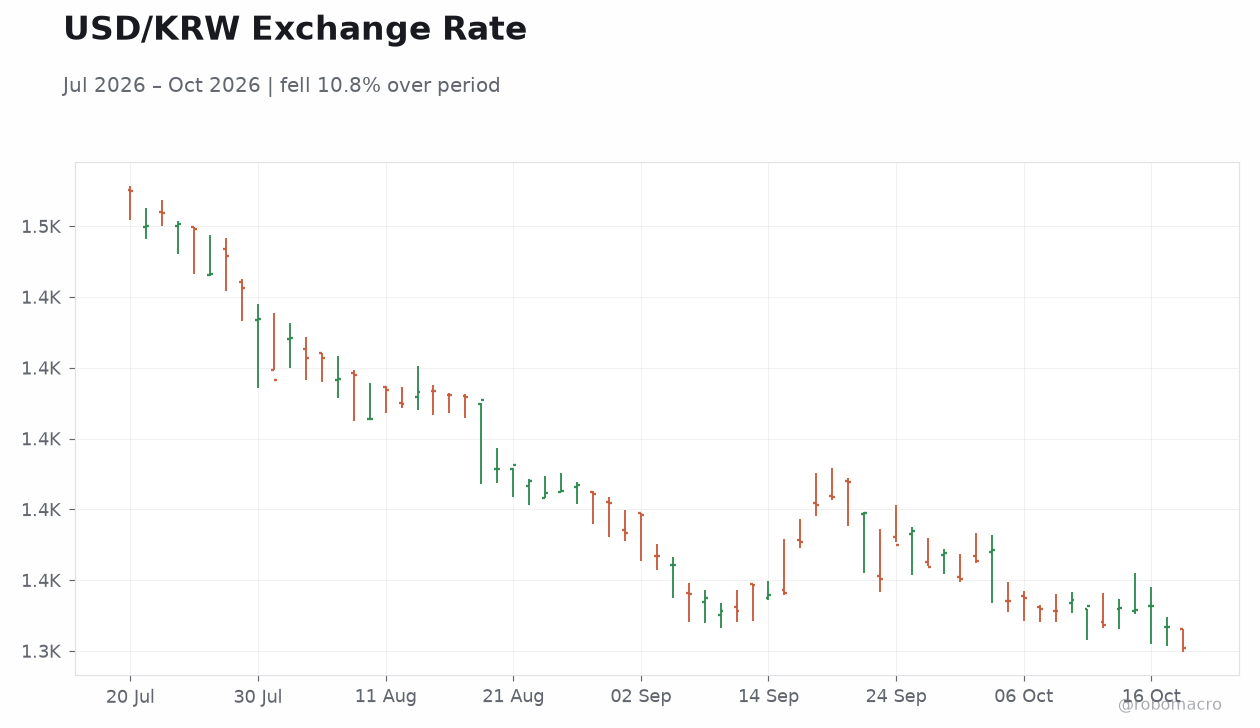
Korean markets delivered a split session on October 19, with the KOSPI closing up 1.76% at 5,768.01 and the KOSDAQ gaining 1.78% to 808.89, though the advance masked sharp weakness in semiconductors. Samsung fell 2.98% to 211,500 won and SK Hynix dropped 4.23% to 1,223,000 won, with battery and auto names providing the offset per market coverage. The won strengthened to a fresh two-year high, with USD/KRW at 1,326.19, down 0.54% on the day.

Rates moved higher across the curve, with the Korea 3Y government yield rising 3 bp to 3.88% and the 10Y adding 3 bp to 4.21%. Brent crude slipped 0.39% to $109.12 while gold eased 0.42% to $4,142.50. No scheduled Korean data releases appeared on the calendar for the session.

The Day Ahead

The Korean calendar is empty for October 20, leaving markets to trade off positioning and offshore cues rather than domestic prints. With no tier-one releases scheduled, attention shifts to the won's persistence near two-year highs and whether intervention rhetoric emerges from authorities. Semiconductor price action remains the key swing factor for the KOSPI given the divergence between index-level gains and chip-sector losses.

Traders will also watch whether the 3Y-10Y curve continues to bear-steepen after the 3 bp moves across both tenors. Absent domestic catalysts, global risk sentiment and dollar direction will dominate the session.

Other Economic Notes

Household financial assets remain heavily concentrated in equities, with roughly one-quarter allocated to stocks, leaving consumer spending exposed to any KOSPI drawdown according to BigGo Finance coverage. Variable-rate loan structures are amplifying the transmission of rate hikes into household repayment burdens, a vulnerability flagged by Chosunbiz as debt-service risk builds. The won's strength to a two-year high complicates the export outlook for margin-sensitive manufacturers even as it supports imported input costs.

Institutionalization of won stablecoins remains delayed, drawing pointed commentary from the U.S. government per Maeil Business reporting. ↓ p.2
Page 1

Korea Macro Daily(Beta Mode)

October 20, 2026 robomacro.com
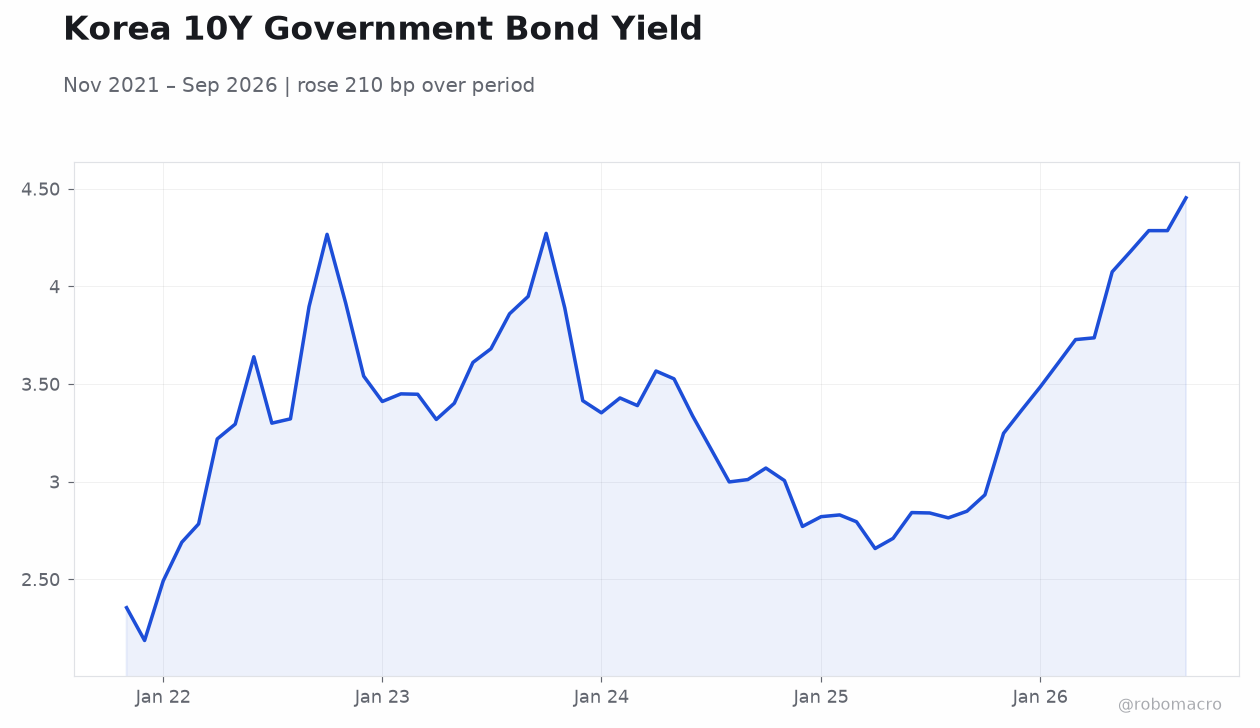
Korea 10Y Government Bond Yield Korea 10Y Government Bond Yield | Type: macro_line | 10Y yield (%): 4.454 (2026-09-01) | Range: 2.187–4.454 | Trend(6pt): 2.355,3.411,3.39,2.71,4.286,4.454
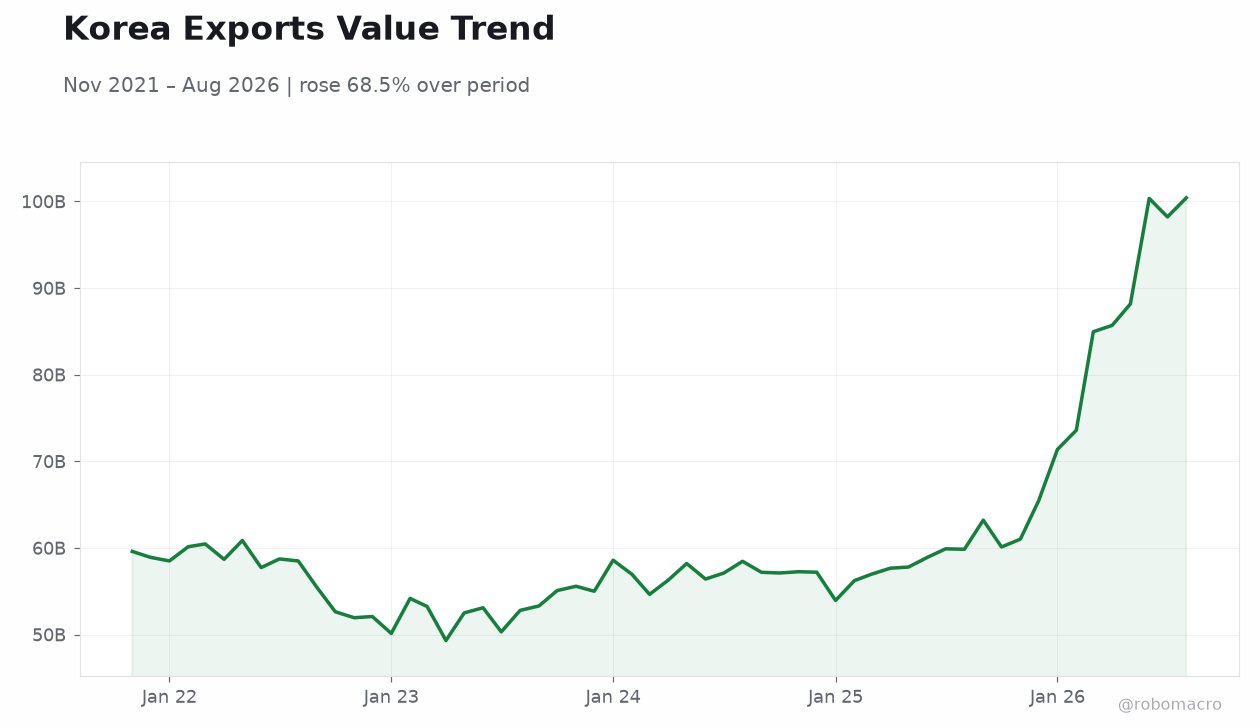
Korea Exports Value Trend Korea Exports Value Trend | Type: macro_line | Exports (KRW): 1.004e+11 (2026-08-01) | Range: 4.933e+10–1.004e+11 | Trend(6pt): 5.96e+10,5.014e+10,5.465e+10,5.78e+10,9.822e+10,1.004e+11
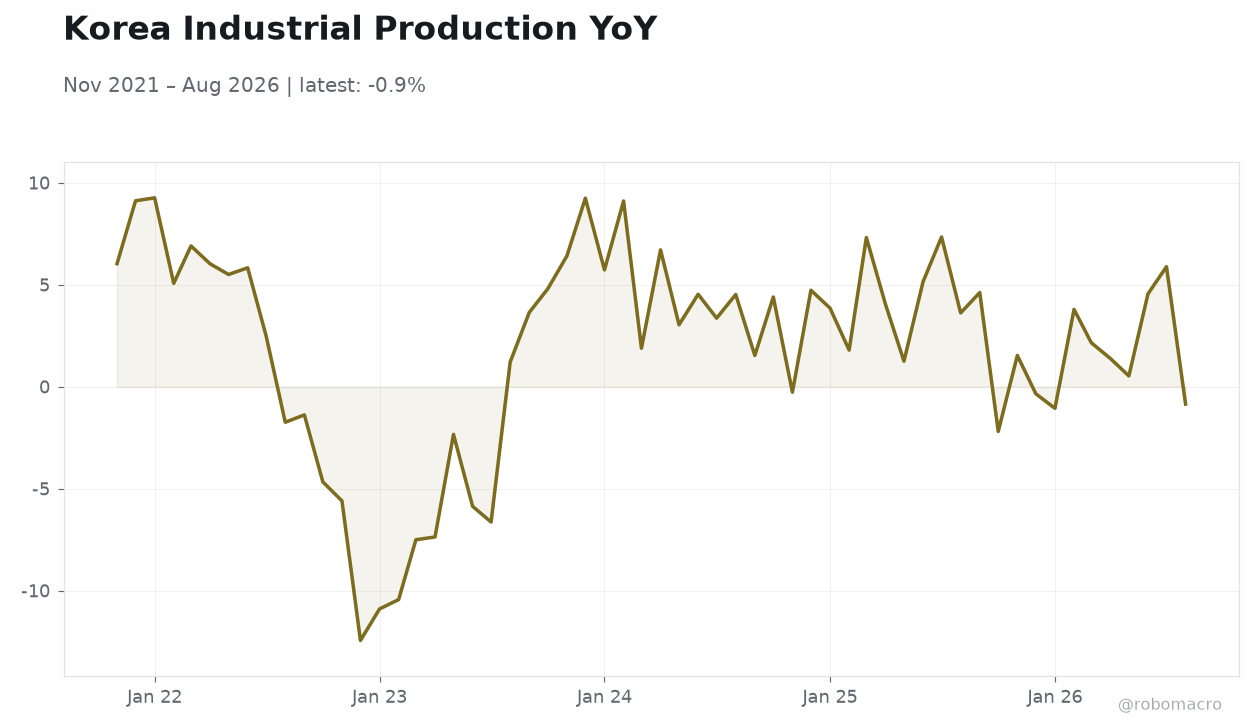
Korea Industrial Production YoY Korea Industrial Production YoY | Type: macro_line | Industrial production YoY (%): -0.8518 (2026-08-01) | Range: -12.45–9.263 | Trend(6pt): 6.034,-10.9,1.887,1.251,5.887,-0.8518
USD/KRW Exchange Rate USD/KRW Exchange Rate | Type: market_hloc | USD/KRW: 1326 (2026-10-20) | Range: 1326–1487 | Trend(6pt): 1487,1417,1373,1362,1341,1326

Other Economic Notes (continued)

The Bank of Korea is expanding tokenization cooperation with the Bank of England, signaling a push on digital settlement infrastructure.

Global Macro News

The dollar's broad softening has driven the won to its strongest level in over two years, a move that cuts across Korea's export competitiveness narrative. Brent crude near $109 keeps energy import costs elevated for a heavily energy-dependent economy, though the 0.39% pullback offered marginal relief. Gold at $4,142.50 reflects persistent demand for hard assets amid an uncertain global rate backdrop.

Bitcoin's 1.15% gain to $82,793 suggests risk appetite remains intact in speculative pockets even as chip equities wobble. U.S. scrutiny of Korea's stablecoin framework delay adds a cross-border regulatory dimension to won-denominated digital asset ambitions.

Global semiconductor demand signals remain the dominant external variable for Korea's trade-dependent growth model. With no domestic data to anchor sentiment, offshore equity and FX flows will set the tone for Korean assets.

BoK Watch

The Bank of Korea is set to pause its rate-hike cycle while hinting at further increases ahead, per Chosun coverage, a hawkish-hold posture that keeps tightening risk alive in forward guidance. The base rate stands at 3.04% as of September 1, and with CPI running at 2.88% year-on-year as of September 30, real policy rates remain only modestly positive, limiting room for complacency. ↓ p.3

Sponsored by Arbitrage Search
Page 2

Korea Macro Daily(Beta Mode)

October 20, 2026 robomacro.com

Continuation

BoK Watch (continued)

The committee's signal of a pause with upside bias suggests the BoK wants to assess the transmission of prior hikes before moving again. Financial stability considerations are central: variable-rate household debt is amplifying repayment risk, and a quarter of household financial assets sit in equities, making the KOSPI a de facto macro variable for consumption. The won's two-year high complicates the inflation picture by cheapening imports, which could argue against aggressive further tightening.

Markets should read the pause-plus-hawkish-guidance combination as a reluctance to declare victory on inflation while acknowledging growth and debt-service fragilities. The 3 bp rise across the 3Y and 10Y curves suggests investors are pricing persistent policy tightness rather than an imminent pivot.

Sponsored by Arbitrage Search
Page 3