Korea Macro Daily(Beta Mode)
BoK Holds Rate Amid Export Surge, Stocks Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| KOSPI | 5,552.74 | -3.73% |
| KOSDAQ | 781.97 | -3.33% |
| USD/KRW | 1,326.26 | +0.18% |
| Samsung | 214,750.00 | -3.91% |
| SK Hynix | 1,218,000.00 | -5.87% |
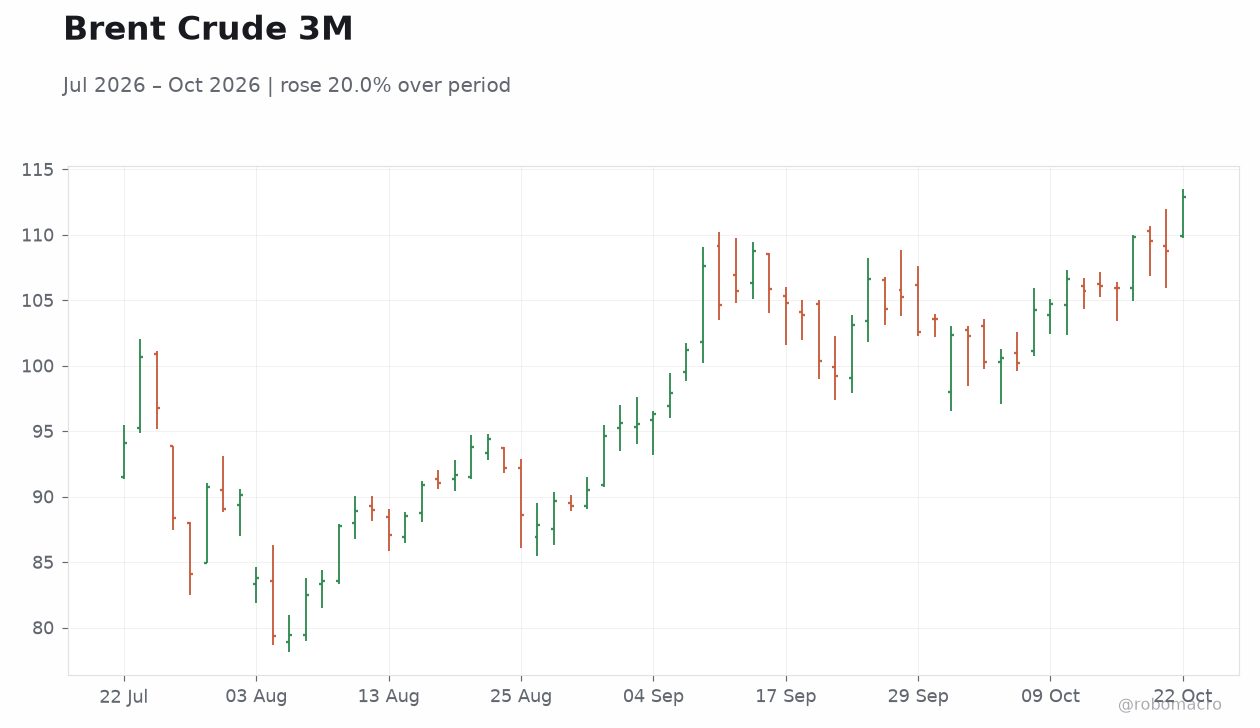
| Brent Crude | 112.87 | +3.72% |
| Gold | 4,039.80 | -2.66% |
| Bitcoin | 81,326.04 | -3.20% |
| Korea 3Y Govt Yield | 3.82% | -2 bp |
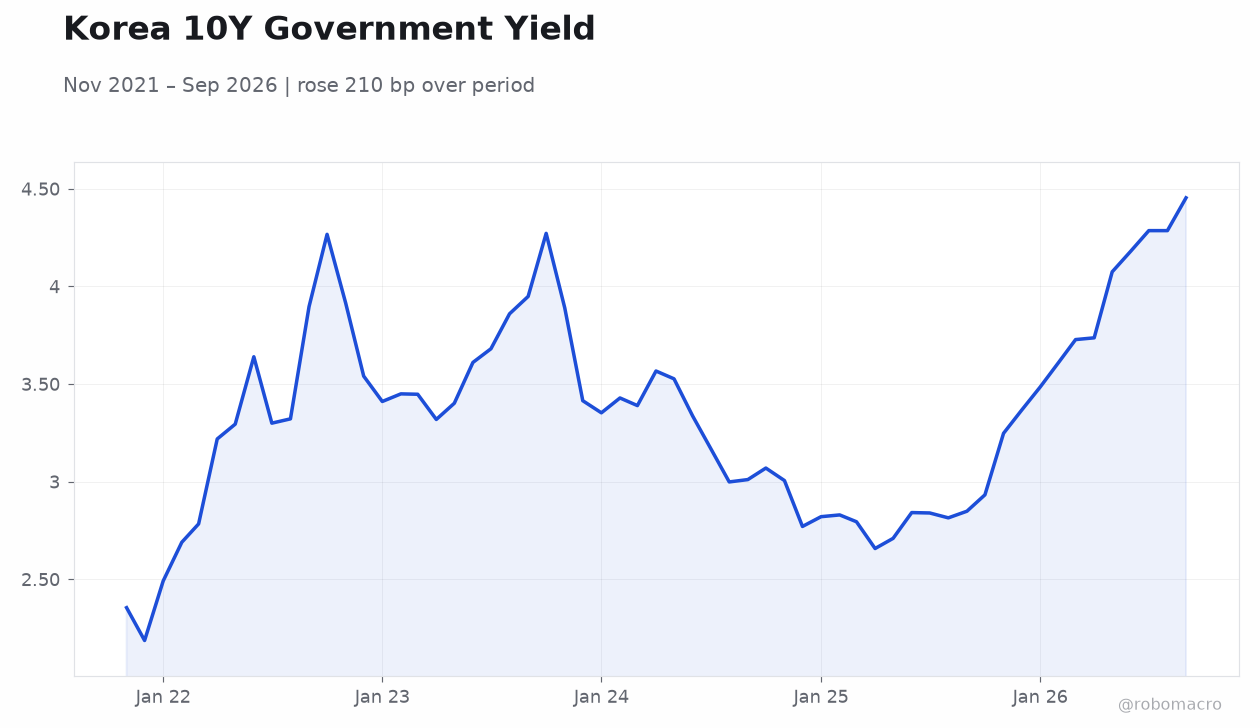
| Korea 10Y Govt Yield | 4.18% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
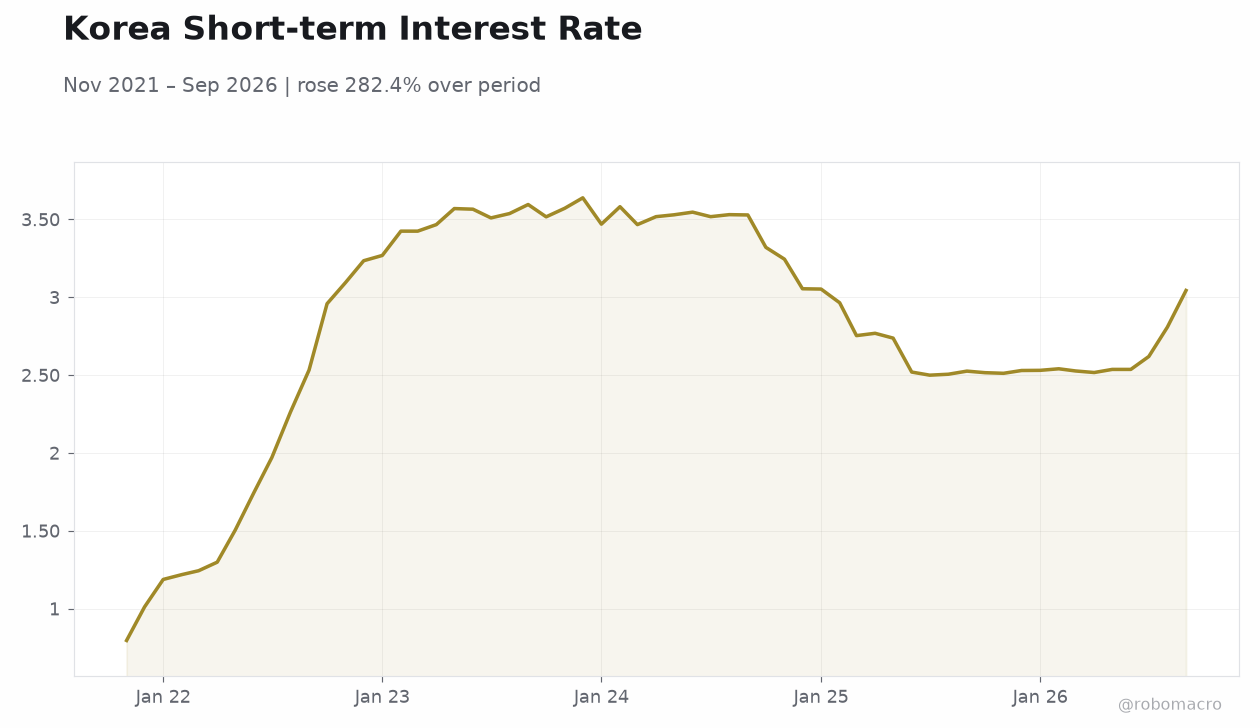 Korea Short-term Interest Rate | Type: macro_line | Short-term Rate %: 3.044 (2026-09-01) | Range: 0.796–3.639 | Trend(6pt): 0.796,3.269,3.467,2.738,2.62,3.044
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Bank of Korea keeps base rate at 3.0% after growth exceeds forecasts
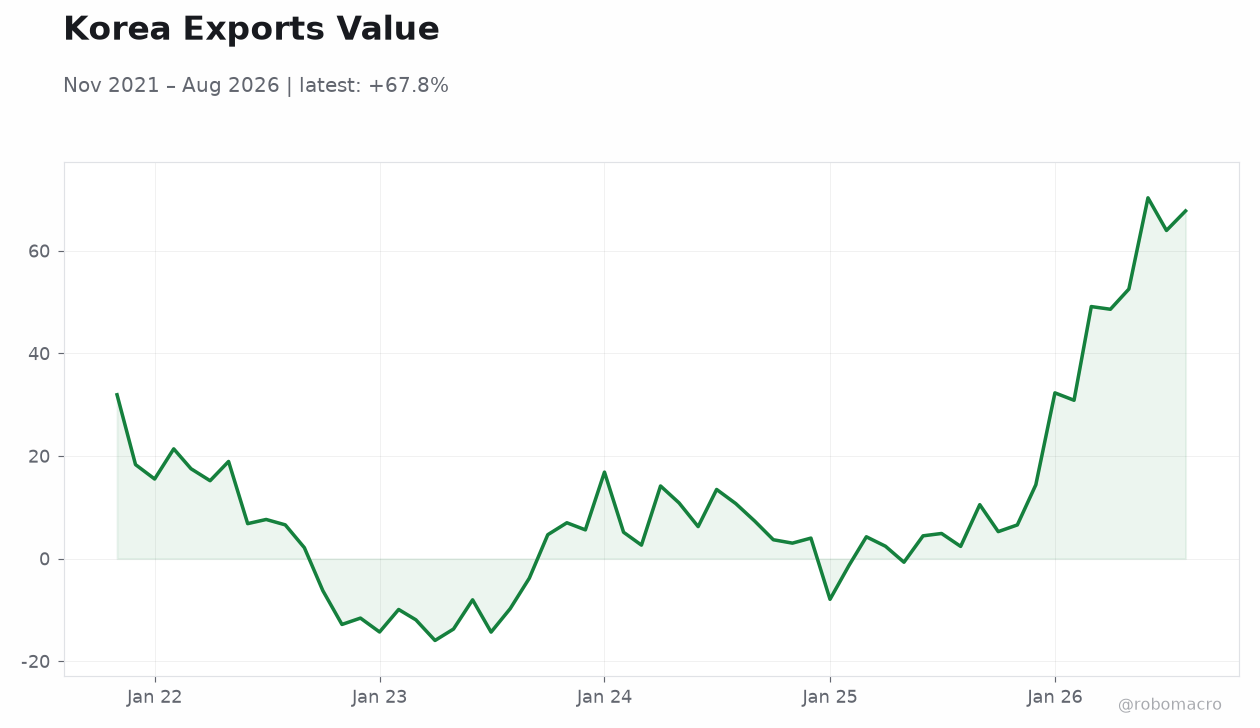
- Exports rise sharply on AI semiconductor demand supporting the won
- KOSPI falls 3.73% to 5,552.74 while 10-year yield eases 3 bp to 4.18%
Yesterday's Recap
The Bank of Korea held its base rate at 3.0% after the committee assessed that growth had beaten forecasts and inflation remained contained near 2.88%. Exports posted a strong increase led by AI chip shipments from Samsung and SK Hynix, reinforcing external demand resilience. The KOSPI dropped 3.73% to 5,552.74 and the KOSDAQ fell 3.33% to 781.97 as investors locked in gains after the recent rally.
The Korean won strengthened against the dollar, closing at 1,326.26 after the rate decision removed near-term easing pressure. The 3-year government yield declined 2 bp to 3.82% and the 10-year yield fell 3 bp to 4.18%, reflecting steady demand for duration. Corporate profit and debt metrics improved in 2025 according to the latest Bank of Korea survey, easing concerns over balance-sheet stress.
KRX activated a buy-side sidecar on the KOSPI during the session’s sharp intraday move.
The Day Ahead
Markets will monitor any follow-up comments from Bank of Korea officials on the growth and inflation outlook after yesterday’s hold. The November National Assembly session is expected to advance legislation on won-backed stablecoins and crypto taxation, with potential implications for capital flows. Export data for October will be watched closely for confirmation that AI chip momentum is broadening beyond memory products.
Analysts at Nomura and JPMorgan remain constructive on Korean semiconductor names despite recent equity volatility. Health insurance income audits and performance bonus flows at major chipmakers may influence near-term consumption and real-estate demand. No major data releases are scheduled for the immediate session.
Other Economic Notes
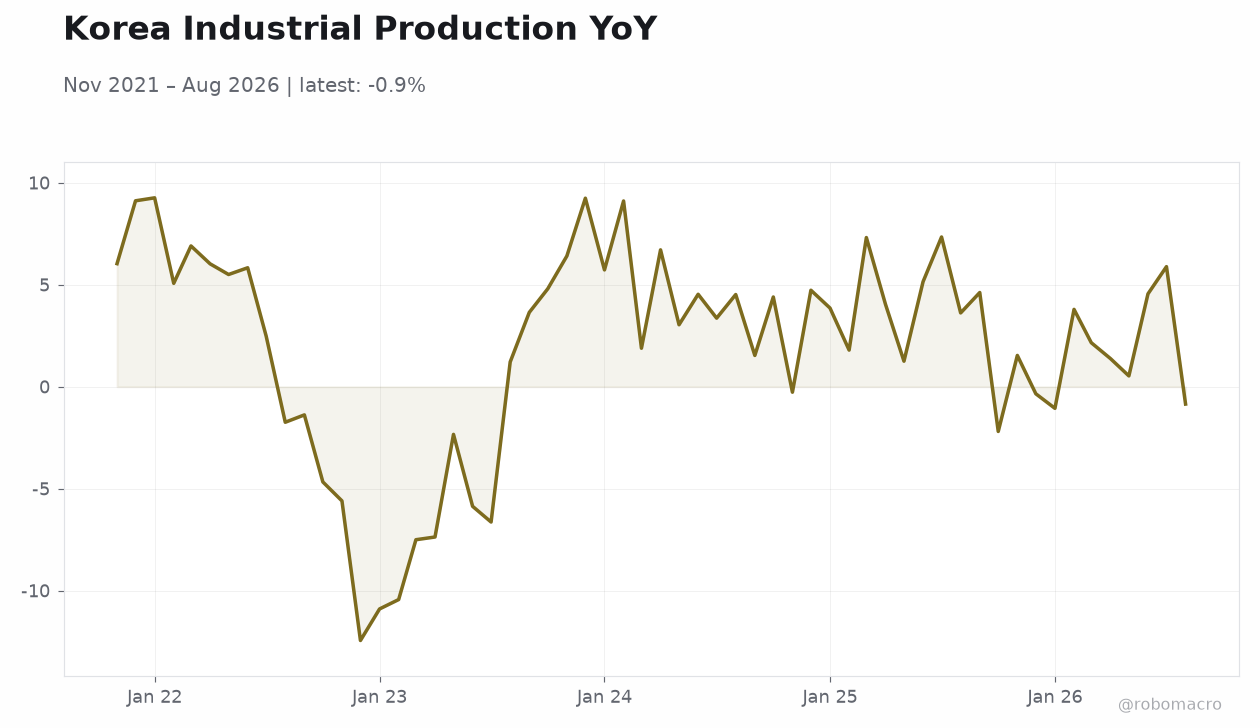
Strong external demand for AI-related components continues to offset softer domestic consumption and construction activity. Corporate balance-sheet repair in 2025 has reduced default risks and supported credit extension by domestic banks. The combination of contained inflation and resilient exports leaves the Bank of Korea with room to keep policy steady through year-end.
Regulatory focus on stablecoins and digital assets may introduce new channels for won internationalization but also adds compliance costs for financial institutions. Performance bonuses exceeding 6 trillion won at Samsung and SK Hynix are likely to support household spending in the fourth quarter.