Korea Macro Daily(Beta Mode)
Chips Slump, Won Slips as CPI Stays Above Target
Market Snapshot
| Asset | Level | Change |
|---|---|---|
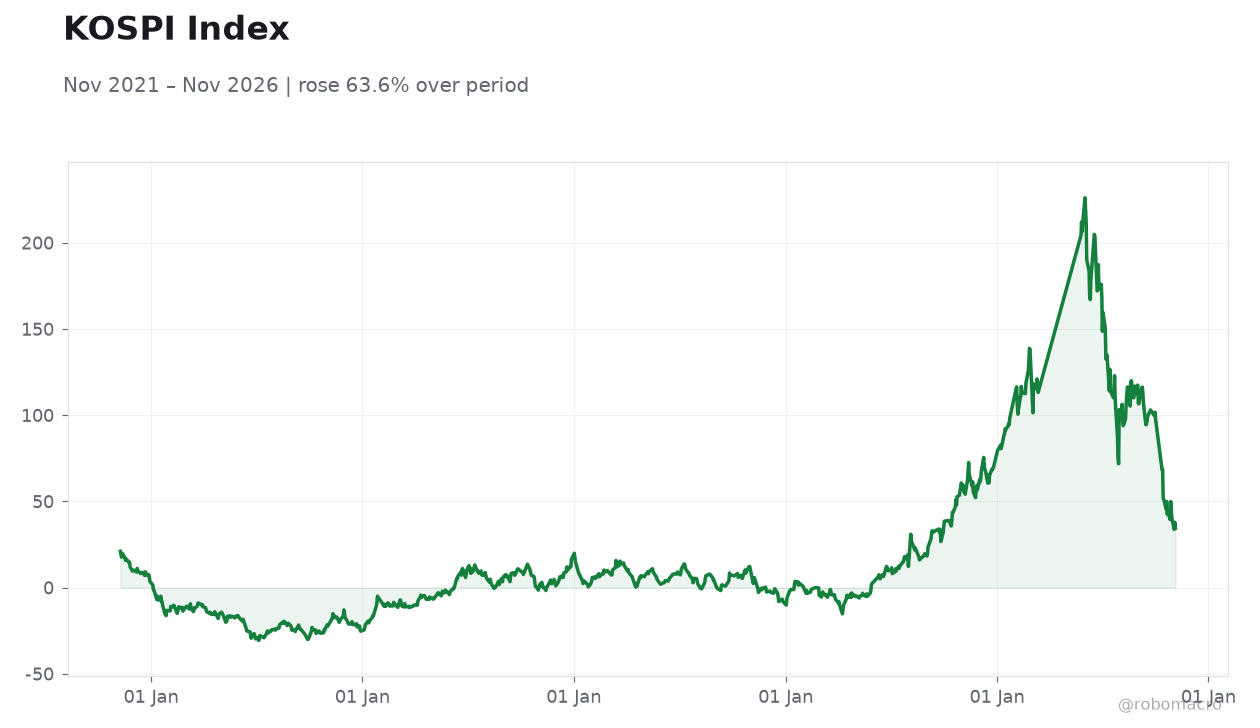
| KOSPI | 5,683.80 | +0.62% |
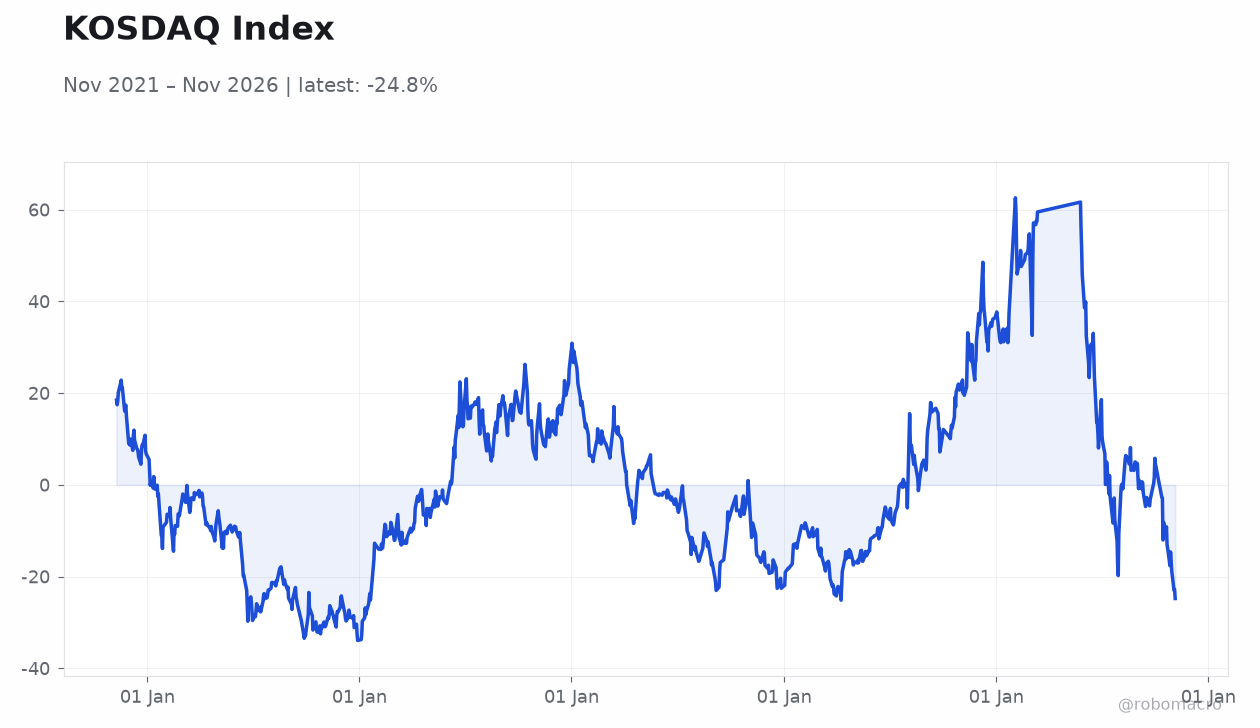
| KOSDAQ | 714.95 | +1.50% |
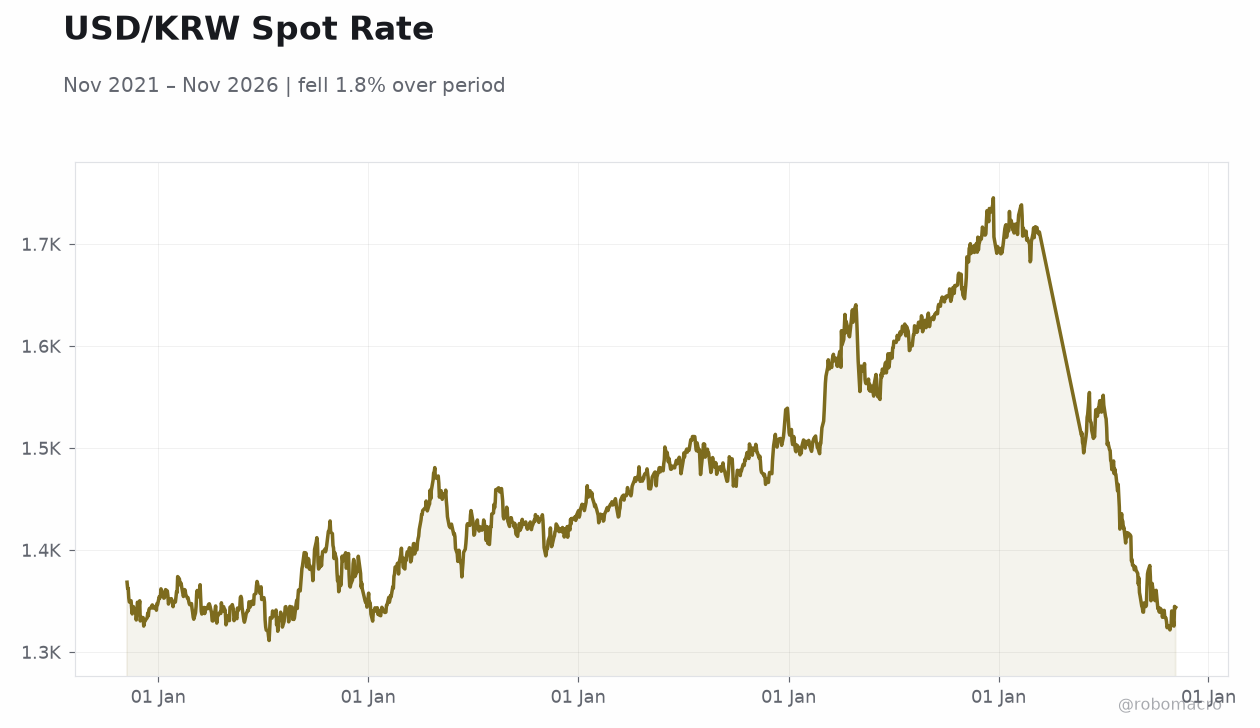
| USD/KRW | 1,356.07 | +0.98% |
| Samsung | 204,500.00 | -6.19% |
| SK Hynix | 1,279,000.00 | -8.38% |
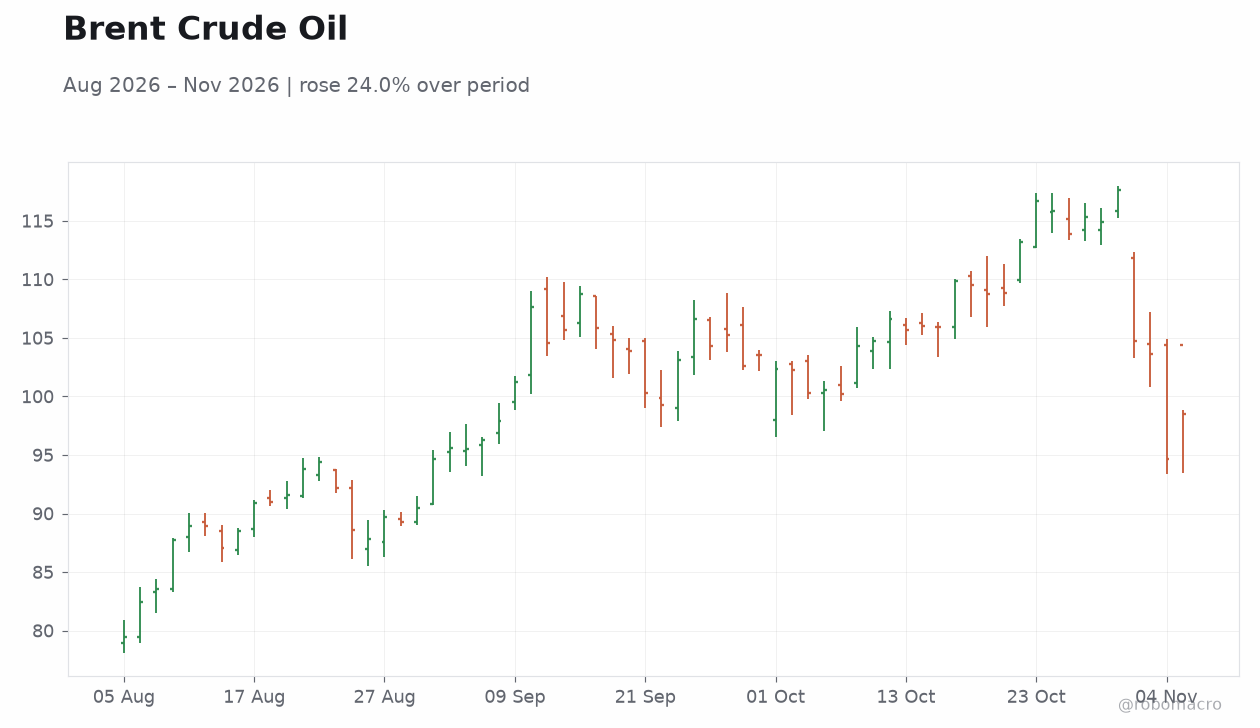
| Brent Crude | 98.46 | +4.06% |
| Gold | 4,100.90 | +0.68% |
| Bitcoin | 75,864.78 | -5.65% |
| Korea 3Y Govt Yield | 3.71% | -3 bp |
| Korea 10Y Govt Yield | 4.00% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 2.90 | 2.90 | 2.80 |
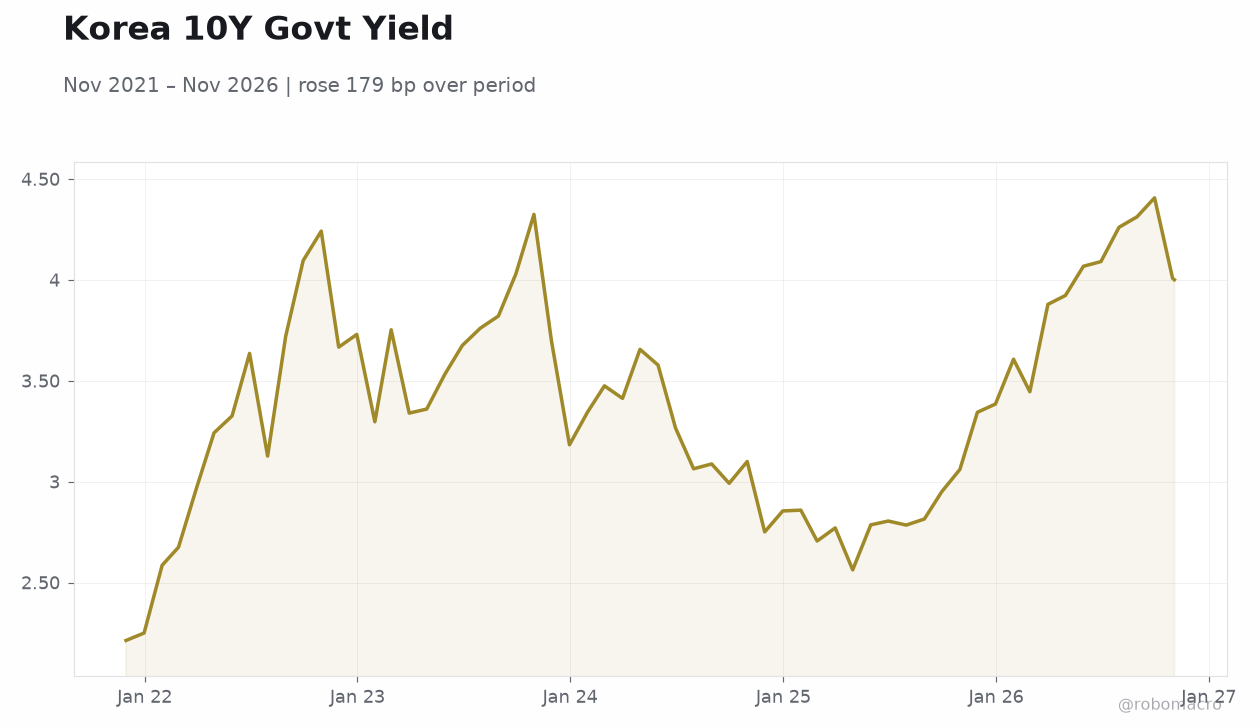 Korea 10Y Govt Yield | Type: macro_line | 10Y Yield (%): 4.001 (2026-11-03) | Range: 2.213–4.407 | Trend(5pt): 2.213,3.753,3.578,2.815,4.001
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Korea's October CPI printed at 2.8% YoY, still above the BoK's 2% target and marginally below both the prior 2.9% reading and consensus of 2.9%.
- KOSPI rose 0.62% to 5,683.80, but Samsung (-6.19%) and SK Hynix (-8.38%) sold off hard on AI-infrastructure concerns tied to the US midterm outcome.
- USD/KRW jumped 0.98% to 1,356.07 even as the 3Y and 10Y yields each eased 3 bp, with Brent up 4.06% to $98.46.
Yesterday's Recap
Korea's October inflation rate came in at 2.8% year-over-year, a touch below both the prior 2.9% reading and consensus of 2.9%, but still comfortably above the Bank of Korea's 2% target. The KOSPI closed up 0.62% at 5,683.80 and the KOSDAQ gained 1.50% to 714.95, though the headline index masked a sharp divergence in large-cap tech. Samsung fell 6.19% to 204,500 and SK Hynix dropped 8.38% to 1,279,000, with press reports attributing the selloff to AI-infrastructure concerns following the US midterm sweep.
The won weakened 0.98% to 1,356.07 against the dollar, a move at odds with Korea Times commentary suggesting the won should strengthen post-midterms. Rates moved the other way: the Korea 3Y yield eased 3 bp to 3.71% and the 10Y fell 3 bp to 4.00%. Brent crude surged 4.06% to $98.46, adding to imported inflation pressure, while gold rose 0.68% to $4,100.90 and Bitcoin dropped 5.65% to $75,864.78.
The Day Ahead
The Korea calendar is empty for both today (November 5) and tomorrow (November 6), leaving markets to trade off external cues and positioning. With no domestic data to anchor sentiment, the won and semiconductor names will likely take their direction from US midterm fallout and global risk appetite. The Brent rally above $98 is worth monitoring for pass-through into Korea's already-elevated headline CPI.
Traders will also begin positioning ahead of the Bank of Korea's next rate decision on November 26, with the 3.00% policy rate currently expected to hold. Absent fresh catalysts, expect range-bound conditions in KOSPI and continued sensitivity in USD/KRW.
Other Economic Notes
The Financial Services Commission finalized a record 3.75 billion won fine on banks and brokers over Hong Kong ELS mis-selling, a reminder of lingering conduct risk in the retail structured-product channel. KakaoBank beat expectations with 141.7 billion won in Q3 net profit and nine-month net profit of 469.8 billion won, up 25%, signaling resilient digital-bank margins. Hanjin KAL's ownership shift, with Hoban overtaking Cho Won-tae as largest shareholder, adds governance noise to the transport-holding complex.
↓ p.2