Korea Macro Daily(Beta Mode)
BoK Flags Consumption Lag as Chip Boom Diverges
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| KOSPI | 5,290.53 | -0.98% |
| KOSDAQ | 699.66 | +0.45% |
| USD/KRW | 1,334.98 | +0.09% |
| Samsung | 206,000.00 | -0.96% |
| SK Hynix | 1,216,000.00 | -3.03% |
| Brent Crude | 95.84 | +0.02% |
| Gold | 3,886.30 | +0.03% |
| Bitcoin | 64,978.41 | +1.33% |
| Korea 3Y Govt Yield | 3.76% | +3 bp |
| Korea 10Y Govt Yield | 4.00% | +6 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Headline Unemployment Rate | 2.60 | - | 2.50 |
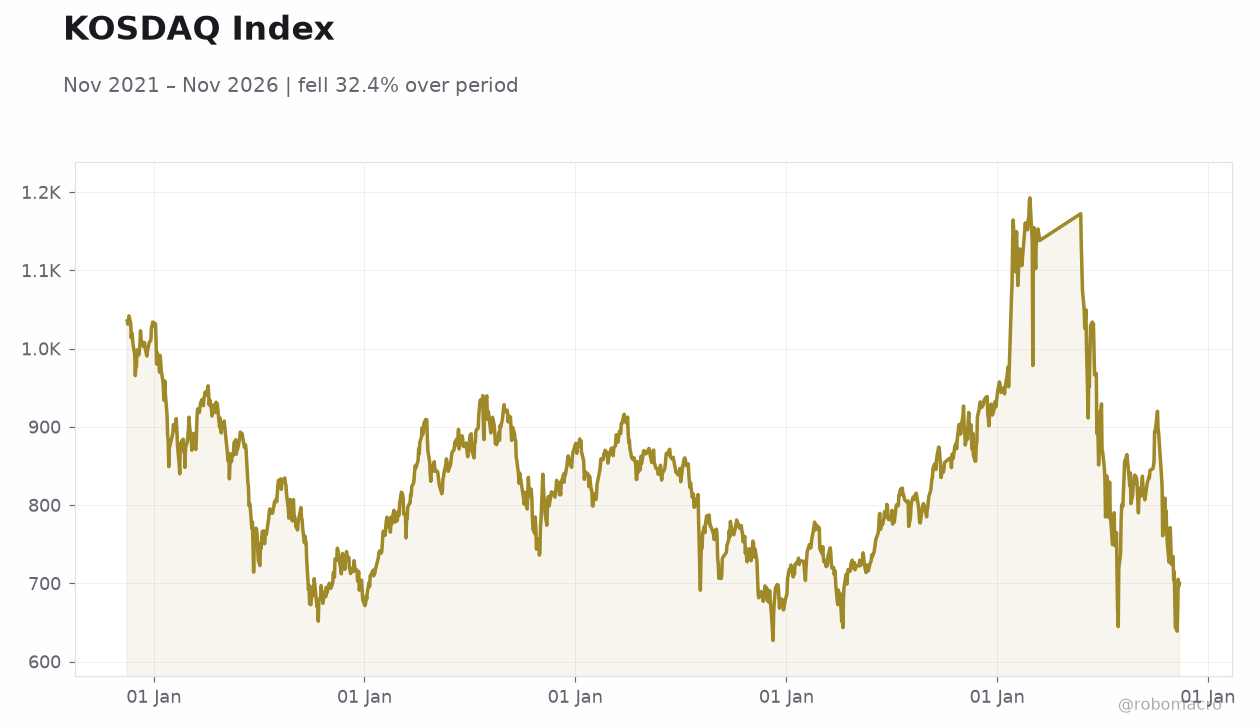 KOSDAQ Index | Type: macro_line | KOSDAQ Index: 699.7 (2026-11-13) | Range: 627–1193 | Trend(5pt): 1035,741.2,872.3,798.2,699.7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Unemployment fell to 2.50% (prior 2.6%), underscoring a tight labor market even as domestic demand lags.
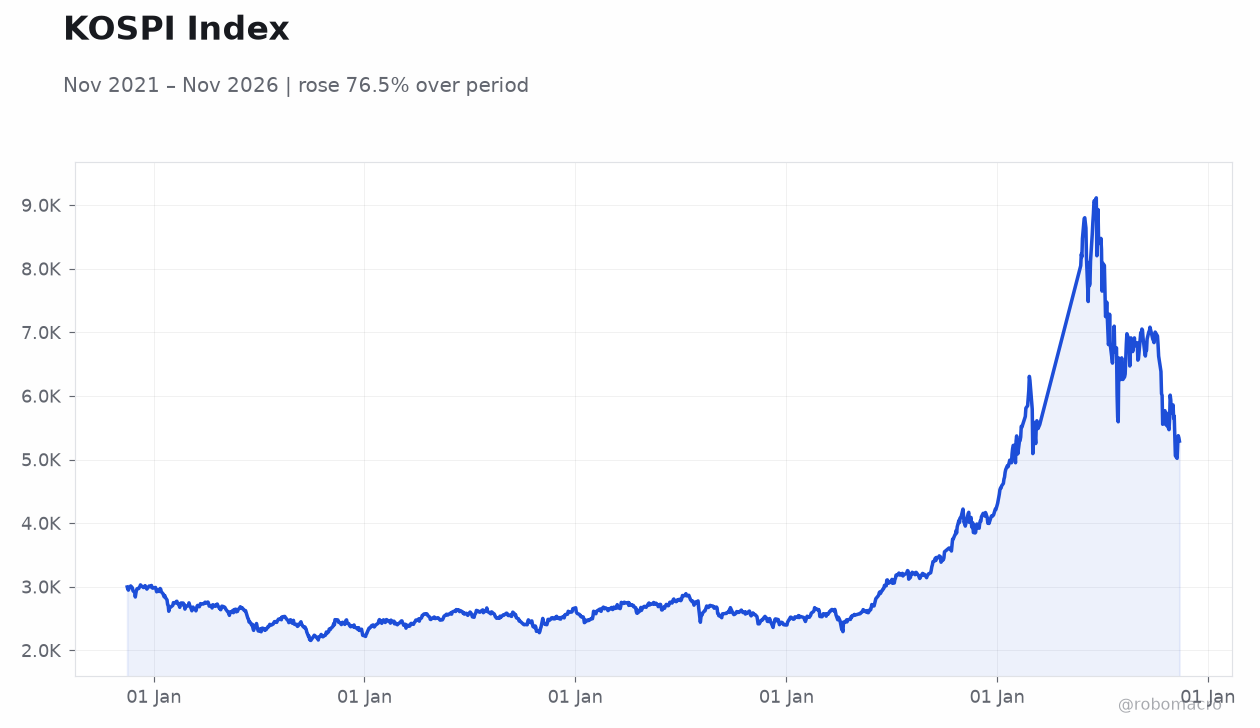
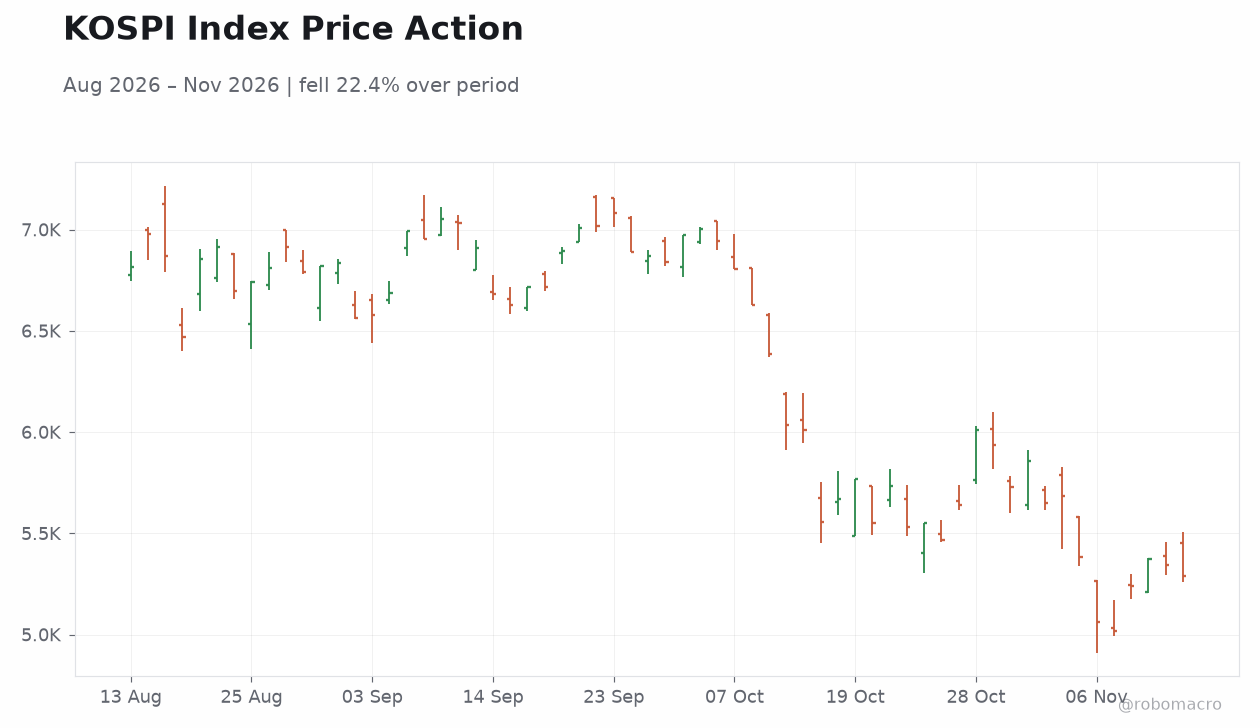
- KOSPI slipped 0.98% to 5,290.53, led by SK Hynix (-3.03%) and Samsung (-0.96%); KOSDAQ gained 0.45%.
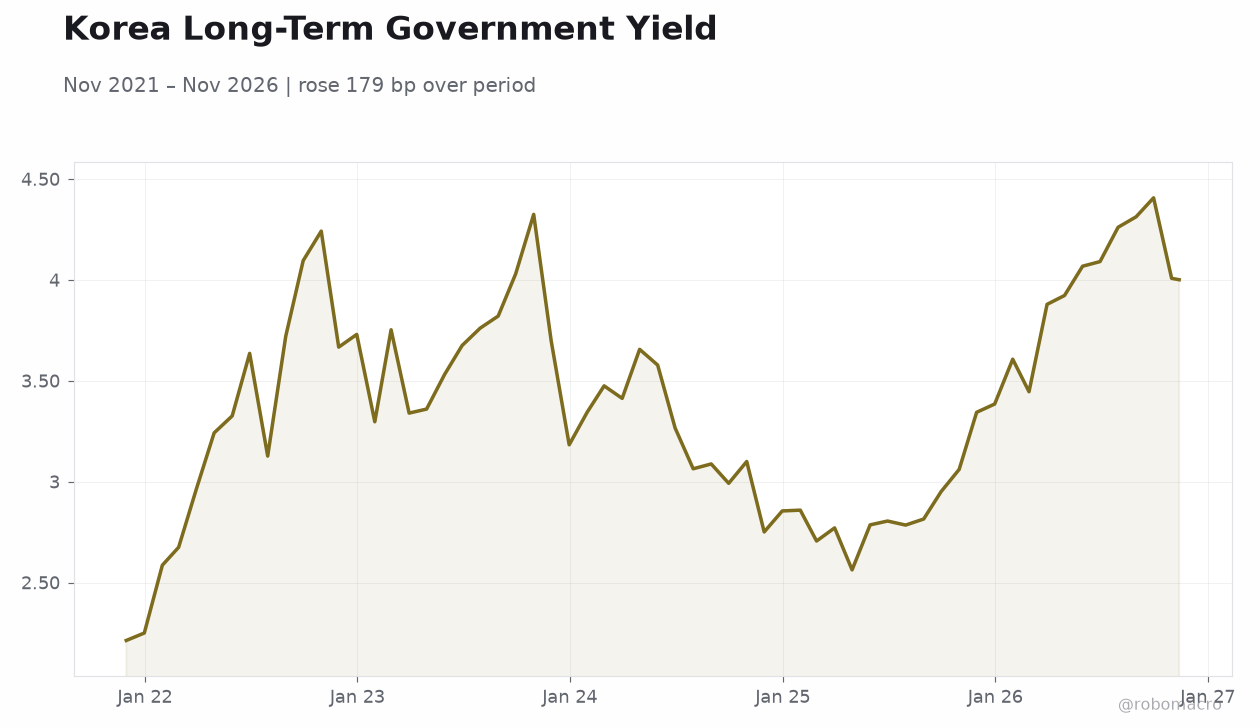
- Korea 10Y yield rose 6 bp to 4.00% and 3Y added 3 bp to 3.76%, steepening on supply and global rate pressure.
Yesterday's Recap
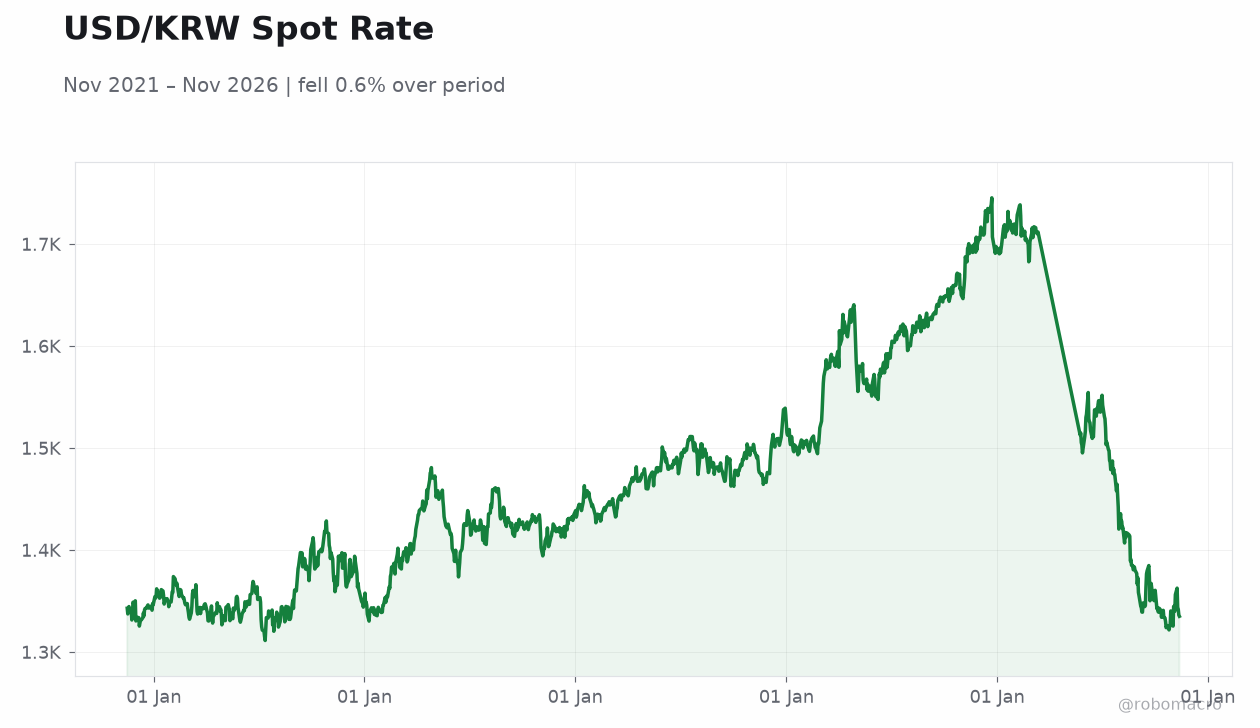
Korea's headline unemployment rate printed at 2.50% for the latest reading, down from the prior 2.6% and confirming labor-market tightness that sits uneasily alongside soft consumption. Equities diverged: the KOSPI fell 0.98% to 5,290.53, dragged by chip heavyweights Samsung (-0.96%) and SK Hynix (-3.03%), while the KOSDAQ rose 0.45% to 699.66 as smaller-cap names outperformed. The won weakened modestly, with USD/KRW at 1,334.98 (+0.09%), pressured by a Brent crude print near $95.84 as oil strength offsets the currency's earlier import-price relief.
Rates moved higher across the curve, with the 3Y at 3.76% (+3 bp) and the 10Y at 4.00% (+6 bp), steepening the curve. October import prices fell again on the stronger won and lower oil prices booked earlier in the month, a disinflationary tailwind for goods prices. September M2 money supply stood at 4,283.9 trillion won, with growth slowing for a third straight month, pointing to restrained credit expansion.
The Day Ahead
The domestic calendar is empty for November 15, leaving markets to trade off global risk sentiment and positioning ahead of the Bank of Korea's November 26 meeting. With no local data to anchor the won, USD/KRW will take its cue from oil and dollar dynamics, and the 10Y's push to 4.00% will be tested by offshore rate moves. Chip names remain the swing factor for the KOSPI given SK Hynix's sharp drop.
Traders will also watch for any BoK commentary on consumption and financial stability ahead of the MPC. Liquidity should be thinner, amplifying moves in rates and FX.
Other Economic Notes
The BoK's latest assessment argues the AI chip boom lifts growth but Korea's consumer rebound will lag Taiwan's, highlighting an uneven export-led recovery. Officials have warned that semiconductor dominance and the stock slump are delaying consumption, a structural concern for domestic demand. A rising potential growth estimate is lifting the neutral rate, which strains debt-laden households as borrowing costs stay elevated.
Money growth slowing for a third month reinforces the picture of cautious credit demand. The BoK has also boosted gold ETF holdings to nearly 500 billion won, a diversification signal for reserve management.