Mexico Macro Daily(Beta Mode)
Superpeso Pressures Exports as Yields Diverge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 63,924.77 | -0.28% |
| USD/MXN | 17.07 | +0.49% |
| EUR/MXN | 19.72 | -0.02% |
| WTI Crude | 103.51 | +3.46% |
| Silver | 63.40 | -1.79% |
| Gold | 4,330.90 | -0.81% |
| Brent Crude | 108.45 | +3.67% |
| Bitcoin | 77,702.06 | +1.12% |
| Mexico Short-term Rate | 5.19% | -3.17% |
| Mexico Long-term Rate | 9.45% | +6.42% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
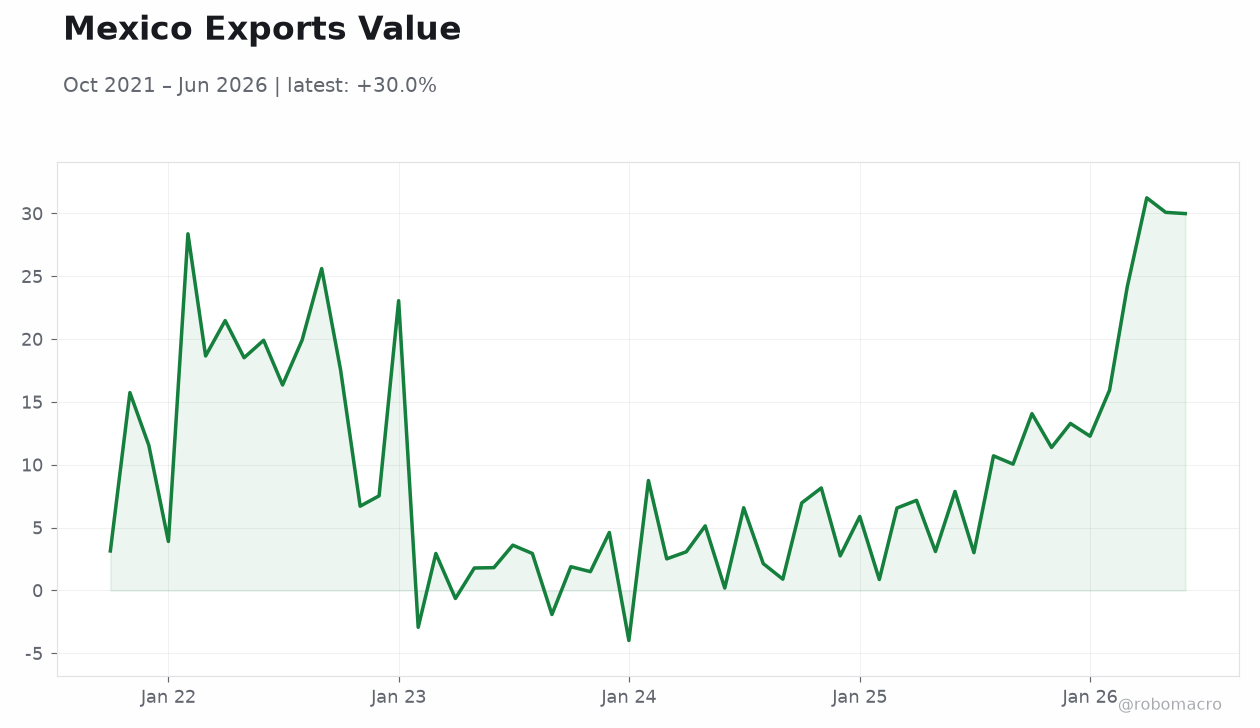
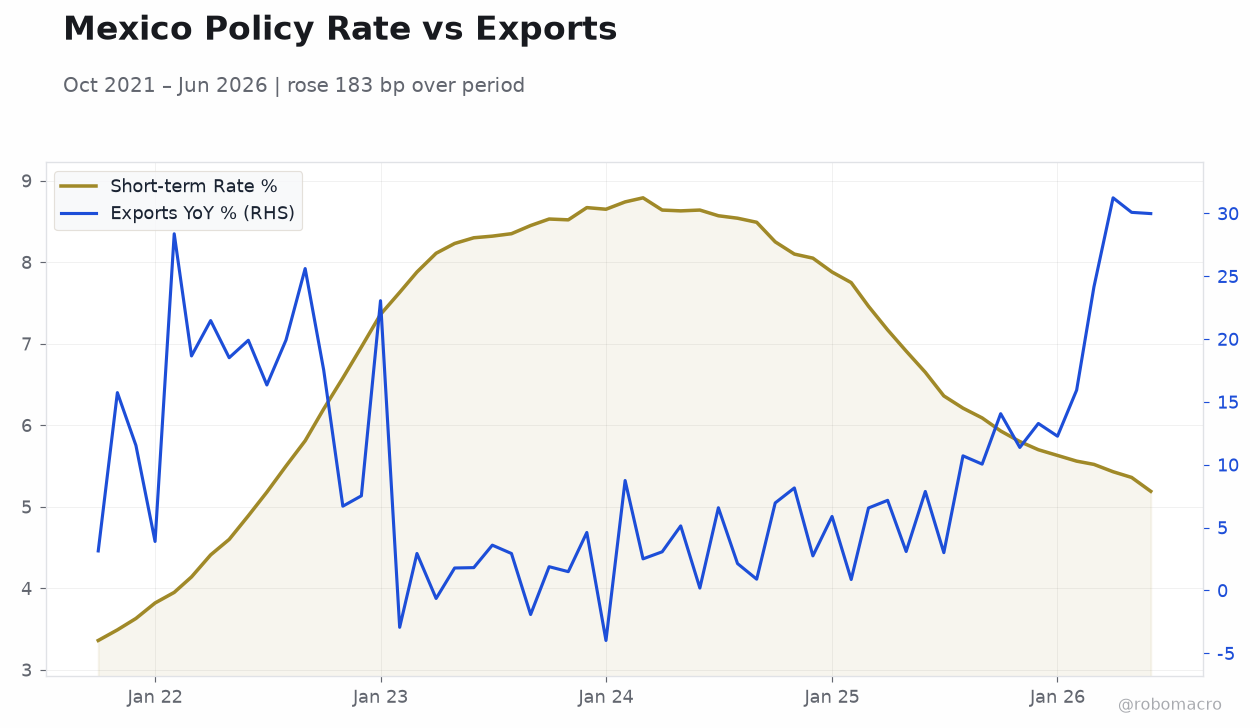 Mexico Policy Rate vs Exports | Type: macro_line | Short-term Rate %: 5.19 (2026-06-01) | Range: 3.36–8.79 | Trend(5pt): 3.36,6.96,8.74,7.17,5.19 | Exports YoY %: 29.99 (2026-06-01) | Range: -3.983–31.24 | Trend(5pt): 3.143,7.528,8.748,7.17,29.99
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- IPC slips 0.28% to 63,924.77 while USD/MXN climbs 0.49% to 17.07
- No data releases or Banxico events scheduled through September 15
- CCE urges rate cut as superpeso appreciation threatens export margins
Yesterday's Recap
Mexican markets posted mixed results on September 13 with limited local catalysts. The IPC Bolsa declined 0.28% to close at 63,924.77. USD/MXN advanced 0.49% to 17.07, while EUR/MXN eased 0.02% to 19.72.
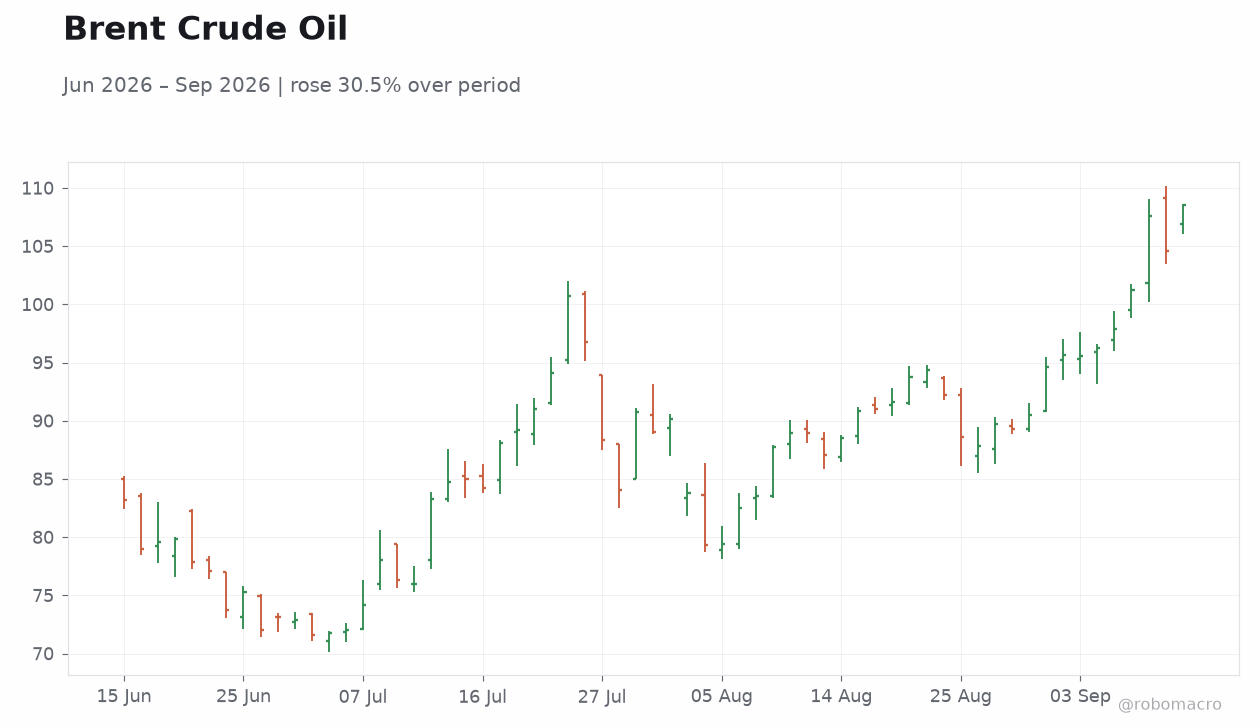
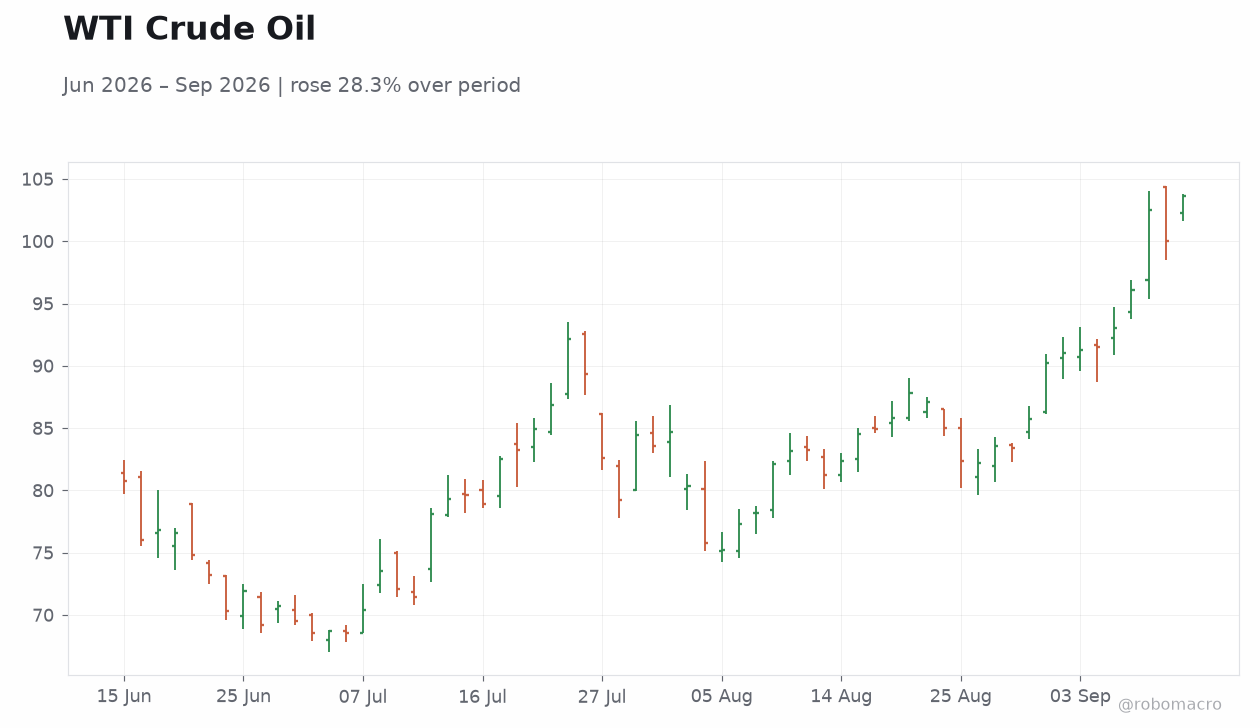
Energy prices surged, with WTI Crude rising 3.46% to 103.51 and Brent Crude gaining 3.67% to 108.45. Precious metals retreated, as Gold fell 0.81% to 4,330.90 and Silver dropped 1.79% to 63.40. Bitcoin rose 1.12% to 77,702.06.
Mbono yields diverged sharply, with the short-term rate falling 3.17% to 5.19% and the long-term rate climbing 6.42% to 9.45%. No economic prints were released, leaving market moves driven by external flows and carry-trade positioning.
The Day Ahead
The calendar remains empty of Mexican data releases, Banxico speeches, or policy minutes through September 15. Traders will monitor global oil prices for further upside given Mexico’s fiscal exposure to energy revenue. USD/MXN direction will hinge on U.S.
data surprises and any shift in carry-trade appetite. Equity flows into the IPC Bolsa may stay light absent fresh nearshoring or USMCA headlines. Attention will focus on any follow-up comments from the CCE regarding peso strength and export competitiveness.
Markets price no change to the 6.50% Banxico policy rate in the near term.
Other Economic Notes
The superpeso, which has appreciated nearly 3% over three months, is squeezing manufacturing margins and prompting the CCE to request a Banxico rate cut. Exporters cite reduced competitiveness against Asian and U.S. rivals amid sustained carry-trade inflows.
Nearshoring momentum remains intact but faces headwinds if peso strength persists without offsetting productivity gains. Remittance inflows continue to provide a buffer for household consumption, though no new monthly figures were released. USMCA trade flows show steady growth in automotive and electronics sectors, yet peso valuation is now the dominant near-term risk cited by industry groups.
Global Macro News
Surging crude prices offer Mexico a fiscal tailwind, with WTI and Brent both posting gains above 3% on supply concerns. ↓ p.2