Mexico Macro Daily(Beta Mode)
Oil Plunge Lifts Mexico 5Y Yield 35bp
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 63,375.93 | -0.78% |
| USD/MXN | 17.19 | +0.16% |
| EUR/MXN | 19.75 | +0.28% |
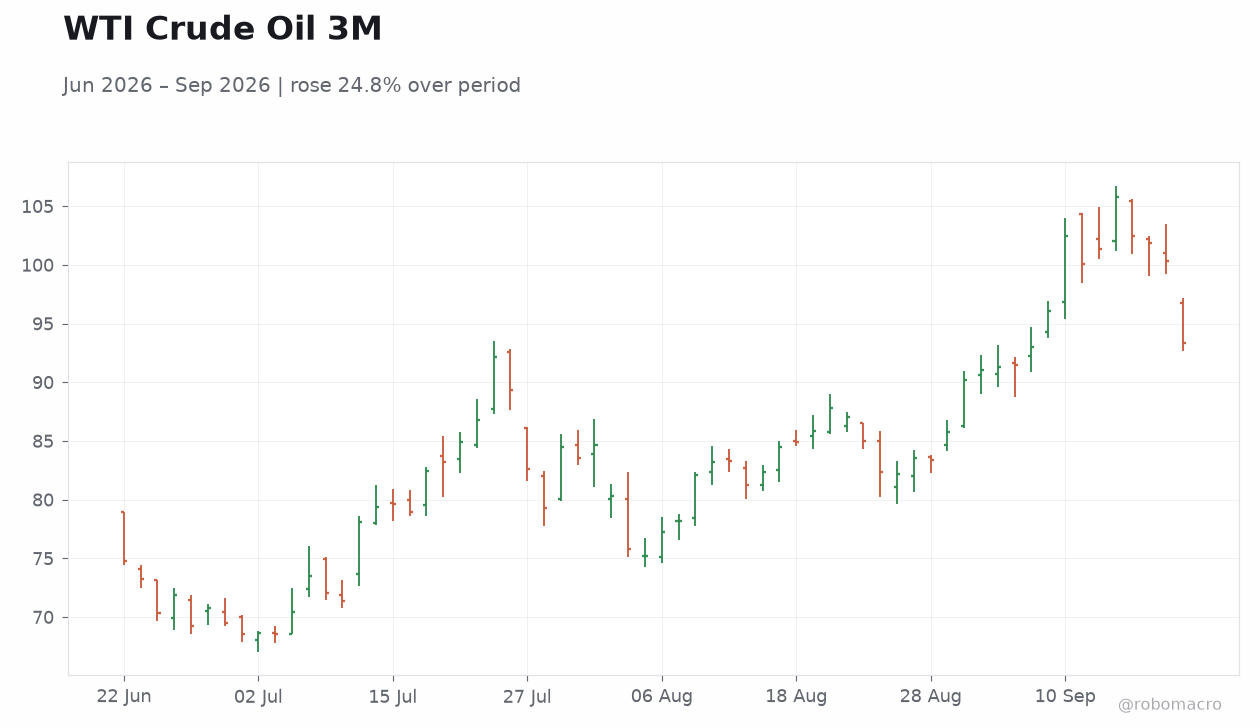
| WTI Crude | 93.56 | -6.72% |
| Silver | 67.12 | +0.85% |
| Gold | 4,403.70 | -0.48% |
| Brent Crude | 97.10 | -6.52% |
| Bitcoin | 84,937.21 | +4.68% |
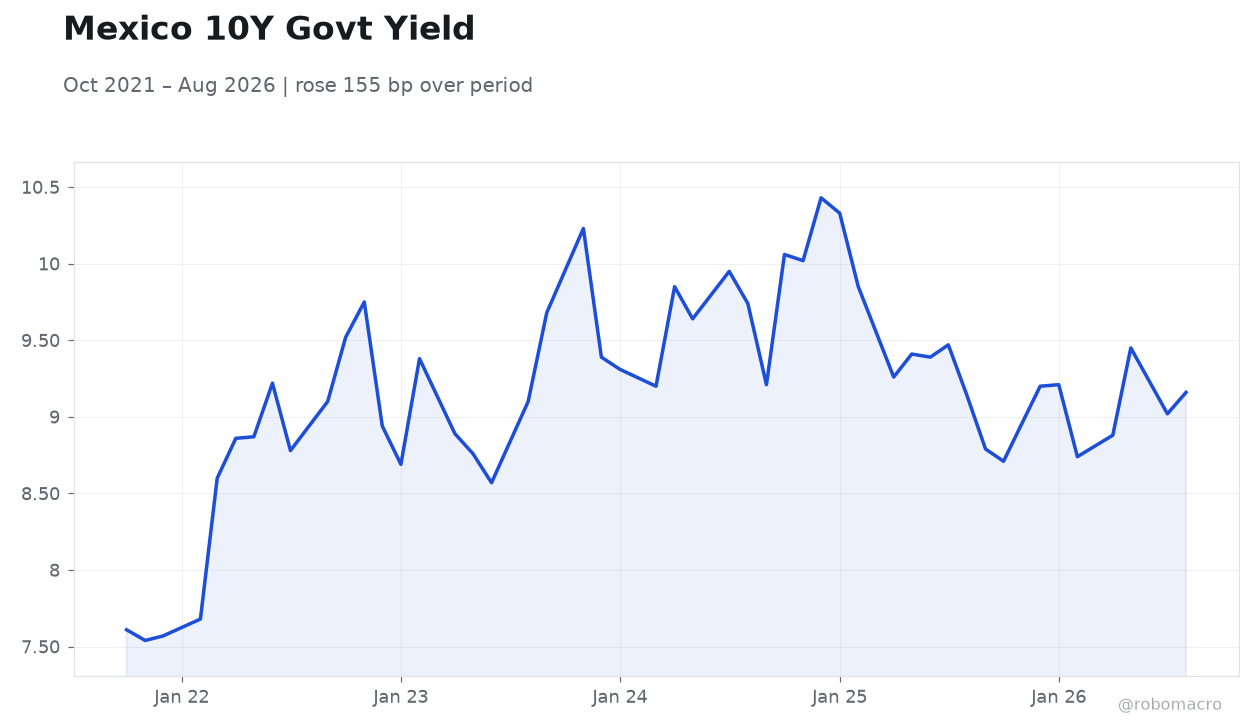
| Mexico 5Y Govt Yield | 9.00% | +35 bp |
| Mexico 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
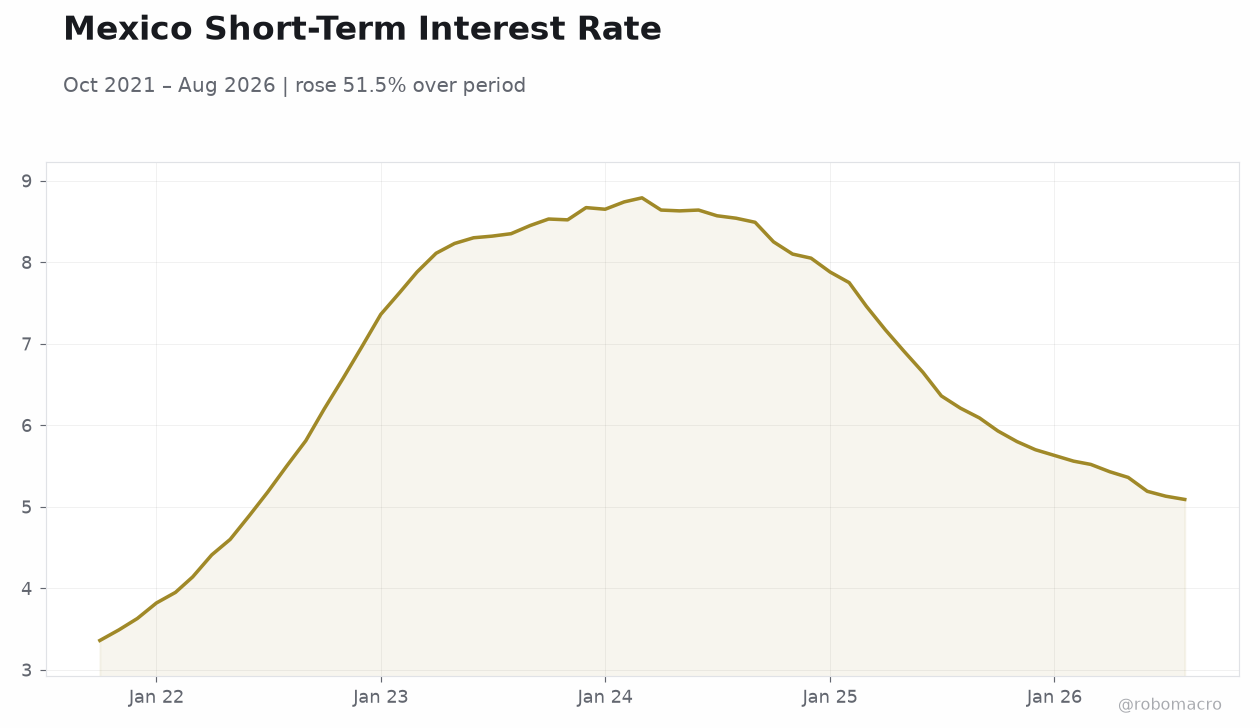 Mexico Short-Term Interest Rate | Type: macro_line | Rate %: 5.09 (2026-08-01) | Range: 3.36–8.79 | Trend(6pt): 3.36,6.96,8.74,7.17,5.19,5.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-09-24) | |||
| Central Bank Interest Rate Decision | 6.50 | 6.50 | 11:00 |
- IPC Bolsa drops 0.78% while Mexico 5Y yield jumps 35 bp to 9.00% on sharp oil decline.
- USD/MXN edges 0.16% higher to 17.19 ahead of Thursday’s Banxico decision.
- Consensus expects Banxico to hold the policy rate at 6.50% with CPI at 3.26% YoY.
Yesterday's Recap
Mexican markets closed mixed on 20 September with no economic data releases. The IPC Bolsa declined 0.78% to 63,375.93 while USD/MXN rose 0.16% to 17.19 and EUR/MXN gained 0.28% to 19.75. WTI Crude fell 6.72% to 93.56 and Brent Crude dropped 6.52% to 97.10, weighing on sentiment.
Silver advanced 0.85% to 67.12 but gold eased 0.48% to 4,403.70. Bitcoin surged 4.68% to 84,937.21. The Mexico 5Y government yield climbed 35 bp to 9.00%, reflecting higher term premia ahead of the central bank meeting.
The peso showed modest depreciation consistent with steady policy expectations priced into Mbonos and FX forwards. No Banxico speakers appeared, leaving market expectations for the central bank unchanged.
The Day Ahead
The sole high-impact event is Banxico’s interest-rate decision scheduled for 24 September at 11:00 ET. Consensus forecasts no change, leaving the policy rate at 6.50%. Markets will scrutinise the statement for any shift in forward guidance on inflation convergence to the 3% target.
Fixed-income and FX desks expect the committee to maintain its data-dependent stance given the 3.26% August CPI print. Any hawkish tilt could support the peso and compress the 5Y yield, while a dovish signal risks further steepening. No other Mexican releases appear on the calendar through mid-week.
Other Economic Notes
JD Sports announced a long-term franchise partnership with Grupo Axo to open more than 140 stores across Mexico, citing strong demand from the country’s young demographic. Capstone Copper agreed to sell its Cozamin copper-silver-zinc-lead mine in Zacatecas to Luca Mining for up to $385 million, unlocking capital for core assets. These transactions underscore ongoing foreign direct investment interest in consumer and mining sectors.
Broader nearshoring momentum and USMCA trade flows remain supportive for medium-term growth despite the absence of fresh data this week. Energy and fiscal developments continue to influence investor positioning in local bonds.