Mexico Macro Daily(Beta Mode)
Banxico Hold Looms as 5Y Yield Climbs 35bp
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 63,536.96 | +0.25% |
| USD/MXN | 17.24 | +0.09% |
| EUR/MXN | 19.75 | -0.11% |
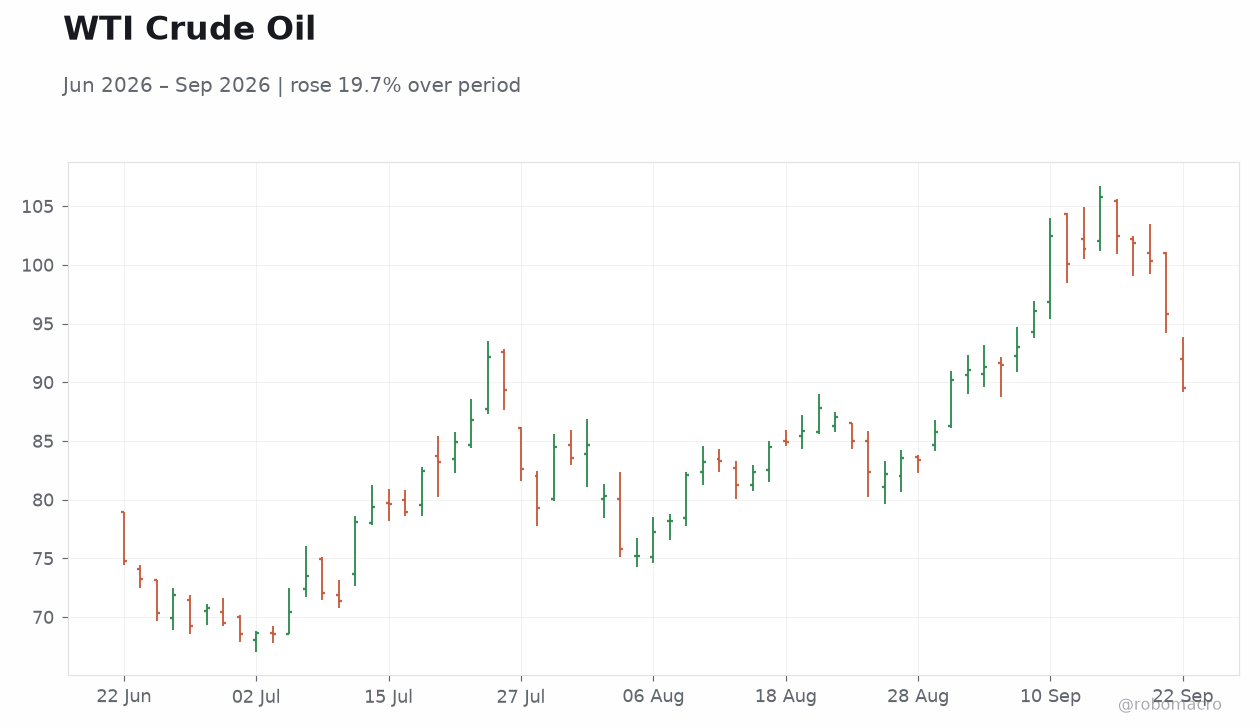
| WTI Crude | 89.51 | -6.55% |
| Silver | 66.47 | +0.99% |
| Gold | 4,378.60 | -0.12% |
| Brent Crude | 98.03 | -2.30% |
| Bitcoin | 85,857.16 | -0.86% |
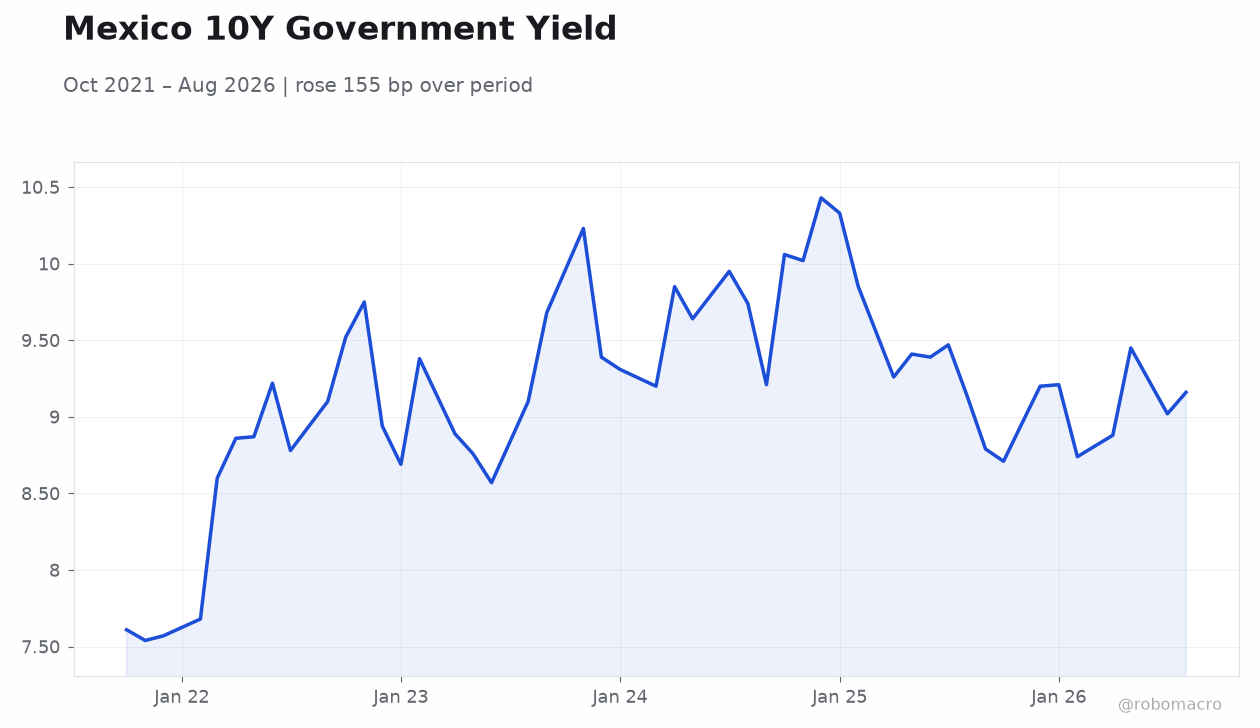
| Mexico 5Y Govt Yield | 9.00% | +35 bp |
| Mexico 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
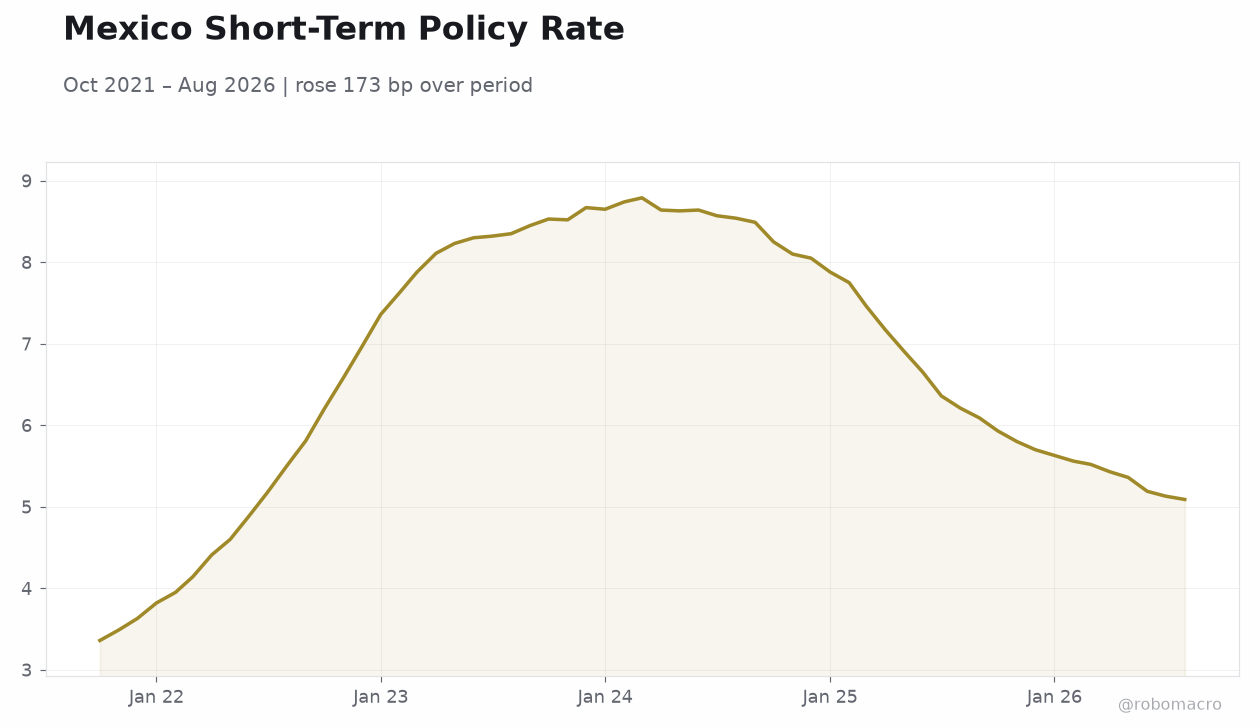 Mexico Short-Term Policy Rate | Type: macro_line | Percent: 5.09 (2026-08-01) | Range: 3.36–8.79 | Trend(6pt): 3.36,6.96,8.74,7.17,5.19,5.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-09-24) | |||
| Central Bank Interest Rate Decision | 6.50 | 6.50 | 11:00 |
- IPC rises 0.25% to 63,536.96 as oil prices fall sharply
- USD/MXN edges 0.09% higher to 17.24 while 5Y yield jumps 35 bp to 9.00%
- Banxico rate decision on 24 September expected to hold at 6.50%
Yesterday's Recap
Mexican markets posted modest gains amid thin data flow. The IPC Bolsa advanced 0.25% to close at 63,536.96. USD/MXN ticked 0.09% higher to 17.24 while EUR/MXN eased 0.11% to 19.75.
WTI crude plunged 6.55% to 89.51 and Brent fell 2.30% to 98.03. Silver gained 0.99% to 66.47 while gold slipped 0.12% to 4,378.60. Bitcoin ended 0.86% lower at 85,857.16.
The Mexico 5Y government yield surged 35 bp to 9.00%. No economic releases occurred on 21 September. Corporate news included JD Sports’ franchise entry via Grupo Axo and Mexico’s push to favor U.S.
suppliers under USMCA rules. TC Energy agreed to sell its Guadalajara-Manzanillo pipeline for $560 million while retaining its broader gas network. Capstone Copper entered a deal to sell its Cozamin mine for up to $385 million.
The Day Ahead
No Mexican data releases are scheduled for 22 September. Attention turns to the Banxico interest-rate decision on 24 September, where consensus points to an unchanged 6.50% policy rate. Markets will parse the accompanying statement for any shift in forward guidance.
The recent 35 bp rise in the 5Y yield suggests investors see limited scope for near-term easing. Broader focus remains on peso stability and USMCA trade flows. Any signals on inflation targeting will influence short-term positioning.
Other Economic Notes
Mexico continues to attract foreign direct investment through targeted partnerships. JD Sports’ long-term franchise deal with Grupo Axo targets the country’s young consumer base. Fibra Educa plans to raise up to $200 million in debt to expand its education-campus portfolio.
TC Energy’s $560 million sale of the Guadalajara-Manzanillo pipeline demonstrates ongoing asset rotation while retaining core gas infrastructure. Capstone Copper’s agreement to divest the Cozamin mine for up to $385 million further illustrates portfolio optimization in the mining sector. These moves underscore Mexico’s appeal for nearshoring and sector-specific capital inflows.